In brief
Article 64 ordinarily restricts assessments after five years from the relevant calendar-year end. Specified twenty-year cases and paragraph (10) agreement need separate analysis; not all VAT history remains within the ordinary period.
ZATCA’s ordinary VAT assessment period runs for five years from the end of the calendar year containing the tax period. It does not run from the return’s filing date, and it does not keep every period since Saudi VAT began open indefinitely. Article 64 also contains a conditional twenty-year period and a separate agreement-based route after the ordinary period. Assess the actual legal basis before deciding whether an older liability can still be assessed.
Calculate the ordinary period from the calendar year
Article 64(3) restricts issuing or amending assessments after five years from the end of the relevant calendar year, subject to paragraph (4). Paragraph (10) separately provides for examination and assessment after the paragraph (3) period with the taxable person’s agreement. The restriction is therefore important, but a date calculation alone does not settle every case.
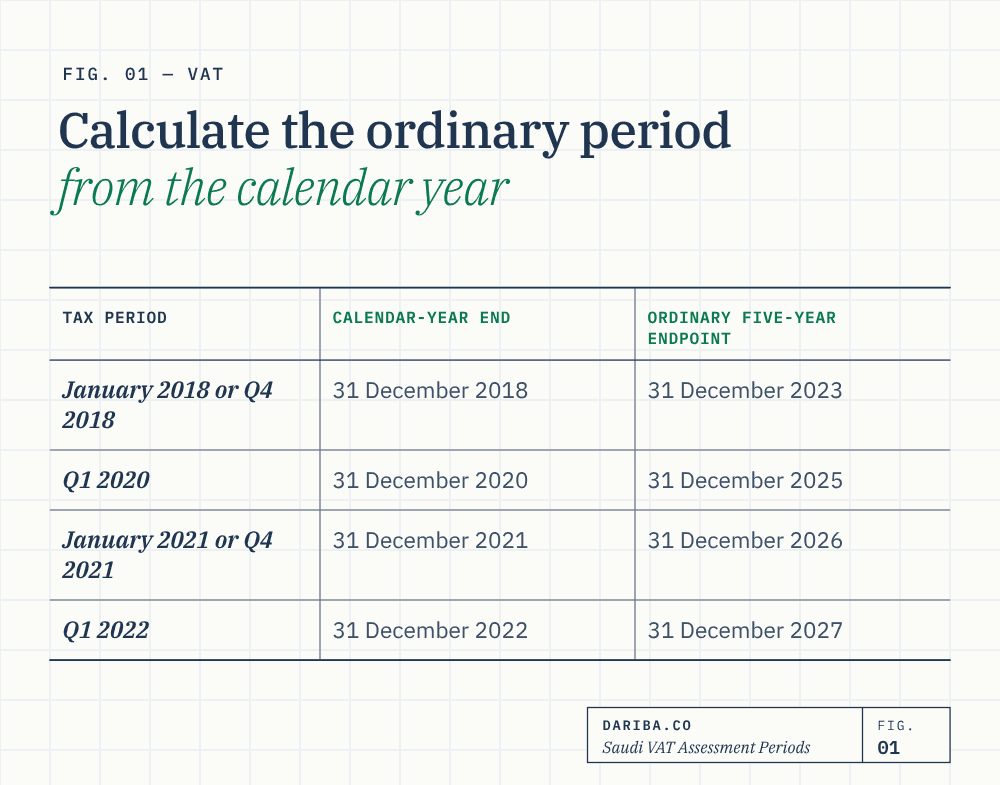
Dariba illustration — ordinary calendar-year calculations, assuming no applicable exception:
| Tax period | Calendar-year end | Ordinary five-year endpoint |
|---|---|---|
| January 2018 or Q4 2018 | 31 December 2018 | 31 December 2023 |
| Q1 2020 | 31 December 2020 | 31 December 2025 |
| January 2021 or Q4 2021 | 31 December 2021 | 31 December 2026 |
| Q1 2022 | 31 December 2022 | 31 December 2027 |
At this article’s October 2026 review, the ordinary period for a 2018 return has already ended. A later filing date is not, in paragraph (3), a substitute starting point. Conversely, all monthly or quarterly periods falling in 2021 share the 2021 calendar-year anchor even though their return deadlines differ.
ZATCA’s dedicated Examination, Assessment, Correction and Objection guideline, version 3 May 2026, section 4.4.1, Example 3, p. 24, gives a directly relevant comparison. Ideal Supplies Co mistakenly zero-rates non-qualifying medical goods in November and December 2020 and January 2021. In a February 2026 examination, the guideline permits an assessment for January 2021 within the ordinary period but excludes the 2020 periods on its non-intentional-breach facts. This illustrates the calendar-year split; it does not decide an independently applicable agreement route under paragraph (10).
Dariba recommends keeping a period-by-period schedule recording the proposed decision, relevant dates and any asserted exception. Calling an entire VAT account “open” can obscure materially different positions across years.
The twenty-year period needs its statutory conditions
Article 64(4) permits issuing or amending assessments for twenty years from the relevant calendar-year end in cases of transactions undertaken with the intention of breaching the Law and Regulations, or noncompliance with registration. It is not a general twenty-year rule for every incorrect return, late payment or arrangement that ZATCA challenges.
Dariba illustration: where paragraph (4) properly applies to a 2018 tax period, the twenty-year calculation reaches 31 December 2038. The same calculation for a 2021 period reaches 31 December 2041. These dates illustrate the arithmetic; they do not establish intentional breach or registration noncompliance in an actual case.
Registration exposure requires reconstructing when registration was required under the applicable rules, rather than treating the date an invoice was issued or a business was incorporated as conclusive. Similarly, an adverse interpretation of an ambiguous supply does not, by itself, prove an intention to breach the rules. Establish the facts, relevant obligation and basis relied on for each affected period. Paragraph (4) should not be paraphrased as extending every future period automatically once an earlier registration failure occurred.
Notice and the assessment’s required contents
Under Article 64(1), ZATCA may assess VAT obligations for one or more tax periods and must notify the taxable person when the assessment is issued. Paragraph (2) requires at least the net tax payable, payment due date, calculation basis and notice of the right to appeal.
For a practical review, connect each adjustment to its period, transaction population, taxable value, rate, deductible input and resulting net amount. An unexplained total is difficult to evaluate against the statutory calculation requirement. Record missing information and request clarification while protecting applicable objection deadlines.
A procedural defect deserves examination. It is not safe to assume that it automatically nullifies the assessment, suspends collection or prevents an objection period from beginning. Those consequences depend on the actual decision, notification and governing procedural rules.
Missing returns and estimated assessments
Article 62(1) addresses an assessment based on ZATCA’s best estimate where a return is not submitted. Article 64(5) permits withdrawal of an assessment issued because of non-filing once the taxpayer or representative submits a complete return for that same period. The provision is permissive; uploading a return does not prove that the assessment and every associated amount have disappeared.
Dariba illustration: an estimated assessment is SAR 2,000,000, while supported records produce net VAT of SAR 400,000. The difference is SAR 1,600,000. Filing the complete return and seeking withdrawal is a sensible response, but that difference is not automatically a cash refund or a cancelled debt. Reconcile the filed return, assessment status, account and any separate penalty decisions.
The same guideline, section 4.3, Example 2, p. 21, describes Al Sunbolah’s quarter ended 31 March 2022. The 20 May estimate is SAR 100,000 net VAT plus a 5% penalty, totalling SAR 105,000. A complete 25 May return reports SAR 50,000 and ZATCA agrees to withdraw the earlier estimate; the example adjusts the penalty to SAR 2,500. Dariba calculates a resulting SAR 52,500 total on those stated facts. The agreed withdrawal and example’s 5% penalty are not a guarantee of every taxpayer’s current penalty rate or automatic withdrawal. Section 4.4, page 22, also explains that an assessment’s payment date does not change the original tax-payment deadline.
An estimate can be higher or lower than the correct liability. The statutory route does not support an assumption that ZATCA estimates always overstate tax. Nor should a pending withdrawal request be treated as an automatic extension of an objection deadline.
Official correction guidance illustrates a different clock
ZATCA’s Amendments to the VAT Implementing Regulations, first issue April 2025, section 2.12, Example 26, p. 43, describes Company B, a legal consultancy, identifying an overstatement in its Q4 2023 return. The guideline permits subsequent-return correction subject to Article 63(4)‘s timeframe. It gives no amount and does not turn correction into an unlimited recovery right.
Dariba analysis: Article 63(4)‘s overstatement-correction limit and Article 64(3)‘s assessment limit both use a calendar-year anchor, but govern different actions. A taxpayer cannot establish a valid correction merely by showing that ZATCA still has time to assess. The later first deduction of an omitted qualifying input, an excess-credit refund request and a correction to an erroneous return also require their own legal analysis.
See the return correction guide before putting an older adjustment into a current return.
Agreement and refund-related examinations remain separate
Article 64(10) allows examination and assessment of a return after the paragraph (3) period with the taxable person’s agreement. It should not be assumed that the ordinary five-year restriction defeats a properly applicable twenty-year basis, or that routine cooperation conclusively establishes the scope of agreement under paragraph (10). See the consent examination guide.
Article 69(7) separately permits examination of a period for which a refund request was submitted within one calendar year from submission, without prejudice to Article 64(3) and (4). It neither promises an audit of every refund nor limits all assessment exposure to one year. The refund guide distinguishes request, approval, payment and examination stages.
Protect the objection route and the evidence
Article 68 refers objections to the applicable Work Rules of the Zakat, Tax and Customs Committees. It does not justify describing every dispute as a new informal administrative layer followed by a guaranteed separate court route. Identify the actual decision and notification and verify the applicable procedural requirements promptly.
Dariba recommends a review file combining the limitation schedule, registration history, original returns, adjustment calculations, assessment notice, supporting records and correspondence. Retention obligations under Article 66 are separate: expiry of an ordinary assessment period is not, on its own, permission to destroy every related document. The records guide explains the different retention periods.
Key takeaways
- Five years runs from the relevant calendar-year end, not from filing; a 2018 period ordinarily reaches 31 December 2023.
- The twenty-year period depends on the statutory intentional-breach or registration-noncompliance conditions, not every return error.
- Paragraph (10) agreement, refund examination, correction, deduction and record-retention rules require separate analysis.
- Assessment notification must include the stated calculation, payment and appeal information; defects do not automatically establish every procedural consequence.
- A complete missing return permits consideration of estimate withdrawal; it does not itself cancel every assessment or penalty.
Sources
- Controlling Arabic VAT Implementing RegulationsTenth edition April 2025. Articles 56,64,68-70; pp. 60,64-74. Arabic controls; applicable conditions and separate deadlines remain.
- ZATCA VAT amendments guidelineFirst issue April 2025. Section 2.12 Example 26, p. 43; designated-person explanation section 2.14, pages 44-46. No invented consent-recovery example.
- ZATCA Examination, Assessment, Correction and Objection guidelineVersion3 May2026. Sections 4.3-4.4.1, Examples 2-3, document pages20-24; sections6-7 pages35-40. Examples preserve actual agreed withdrawal, historic facts and ordinary-limit assumptions.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.