In brief
Identify the person, ownership and activity before computing the relevant Article 6 base. Company, individual, PE, production and gas rules differ; separate-person and company independence remain important alongside ordinary compliance.
Start with the person and the statutory tax route
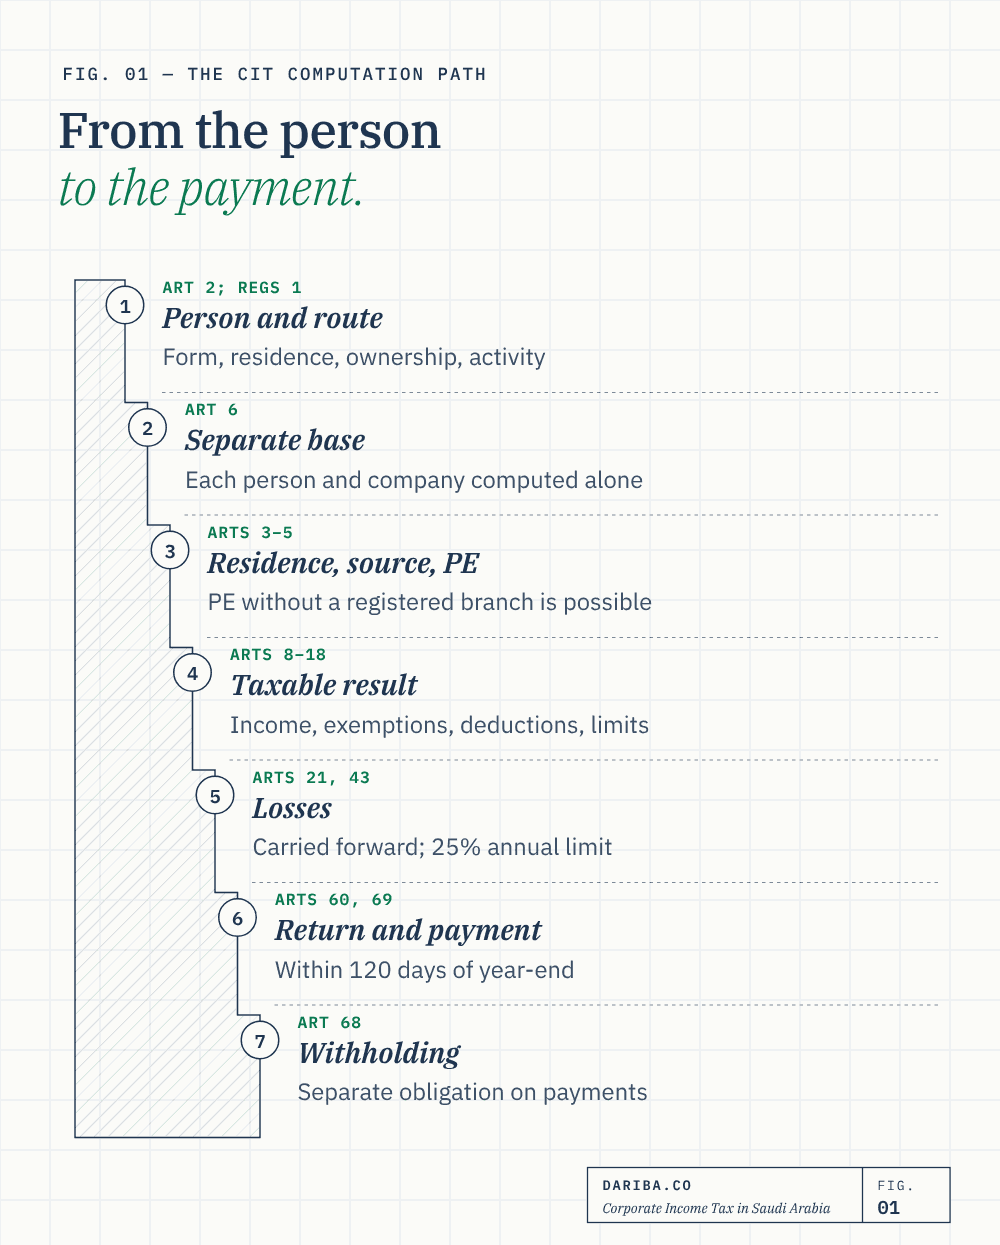
Saudi corporate income tax begins with the taxpayer’s legal form, residence, ownership and activity. Income Tax Law Article 2 and Regulations Article 1 cover resident capital-company interests within the stated ownership rules, non-Saudi resident individuals carrying on activity, non-residents operating through a permanent establishment and non-residents with specified Saudi-source income. Natural-gas, oil and hydrocarbon activities have particular provisions.
The ordinary Article 7(a) rate is 20% for the stated categories, applied to the relevant taxable base. It is not 20% of every receipt earned by every foreign person. ZATCA’s Simplified Guideline for Income Tax, second version May 2026, sections 1–4, provides the overview, subject to the controlling legislation.
Natural-gas activity has a separate statutory route
Law Article 2(e) and Regulations Article 1(3) expressly address natural-gas investment and transportation, including the stated Saudi and non-Saudi persons. Its scope cannot be settled only by applying the ordinary foreign-shareholder description to a company.
Current Article 6(g) requires the gas base to be separate from the person’s other activities, while Article 7(b) states 20% on that base. The amended scope and rate should not be replaced by the former 30% wording or the deleted internal-rate-of-return gas-investment table. Oil/hydrocarbon production has separate Article 7(c) conditions.
Where a taxpayer operates both categories, Regulations Article 57(8) requires one return with separate base and tax details, rather than unrestricted pooling. The natural-gas guide explains the activity boundary, related income, oil/gas cost separation and the limits of the historical material.
Trace ownership and keep the company’s computation separate
Regulations Article 1 addresses direct and indirect non-Saudi ownership and the specified Saudi-market speculative holding exclusion. The Law also contains the particular oil/hydrocarbon producer ownership rules and exclusions. A Saudi-incorporated intermediary does not, by itself, establish that all underlying interests fall outside income tax.
Law Article 6(e) requires a capital company’s base to be calculated separately from shareholders and subsidiaries, even where accounts are consolidated. For mixed ownership, establish the actual CIT and Zakat routes and allocation rather than applying one national label to the whole group. The legal person, ownership chain and relevant year should be documented before the computation begins.
Match the base to the statutory taxpayer category
Article 6 does more than identify a single accounting-profit figure. Its paragraphs distinguish the person, relevant income, ownership interests and separate computation:
| Law provision | Base or separation rule |
|---|---|
| 6(a): resident capital company | The stated non-Saudi shareholder interests and interests of shareholders working in oil/hydrocarbon production, in taxable income from activity from sources in the Kingdom, less permitted expenses. Establish the applicable Article 2 ownership exceptions first. |
| 6(b): non-Saudi resident natural person | Taxable income from activity from sources in the Kingdom, less permitted expenses. Residence alone does not turn every private or exempt receipt into taxable business income. |
| 6(c): non-resident conducting activity through a Saudi PE | Taxable income arising from, or connected with, the PE’s activity, less permitted expenses. Actual connection and attribution require evidence. |
| 6(d): each person | Compute each person’s base independently of any other person. Common ownership alone does not combine taxpayers. |
| 6(e): capital company | Compute its base independently of shareholders, partners and subsidiaries, even where accounts are consolidated with another person. |
| 6(f): oil/hydrocarbon production | Relevant taxable income less permitted expenses, excluding the separate natural-gas investment base. |
| 6(g): natural-gas investment | Relevant taxable income less permitted expenses, with that base independent of the person’s other activities. |
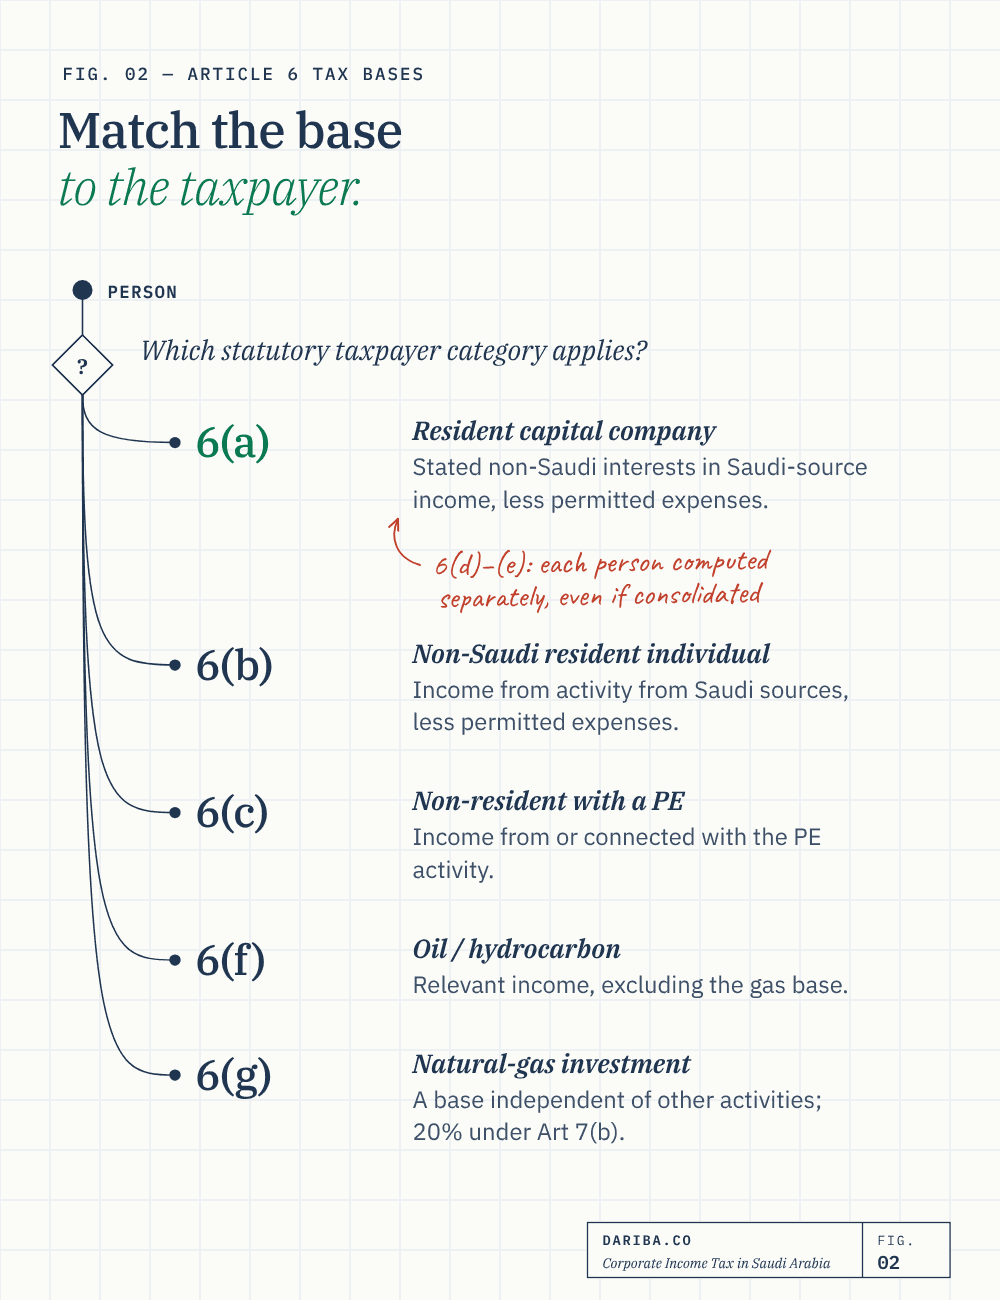
The table preserves Article 6(a)‘s Saudi-source wording. Regulations Article 5(4) separately brings a resident capital company’s income from its own and branch operations inside or outside the Kingdom into its stated rule. Read those provisions together when examining foreign receipts; do not extend the resident natural-person row into a universal worldwide-income statement or use an overseas bank account as a basis for excluding company income. The source guide addresses that distinction. Any exemption, foreign-tax treatment or treaty claim needs its own legal and factual basis.
Dariba analysis: individual ownership, a capital-company interest, a Saudi PE and a separately classified production or gas operation are different computation questions. A group spreadsheet should identify which legal person and base each schedule belongs to before costs, losses or credits are combined. The independent-base guide explains subsidiary control, equity-method results and the separate conditional Zakat group rules.
Source: current Arabic Income Tax Law, Article 6, pp. 7–8, and current Arabic Regulations Article 5(4), p. 5. For production capital bands and the later downstream extension under M/261, use the oil and downstream guide.
Establish residence, source and permanent-establishment exposure
Law Articles 3–5 distinguish residence, permanent establishment and source. Regulations Article 5(4) addresses a resident capital company’s income from operations and branches inside and outside the Kingdom. An overseas bank account does not independently exclude a receipt from the Saudi computation.
A non-resident can have Saudi tax exposure without a registered branch. A fixed place, specified project or dependent-agent activity may establish a PE, while other Saudi-source payments can fall under withholding or the general capital-gain rules. Review the PE guide and taxable-activity guide before deciding how a cross-border contract is taxed. Treaty relief requires the actual agreement and eligibility.
Reconcile accounting profit to the taxable result
Law Article 8 includes operating and incidental income, with Article 10 exemptions considered separately. Law Articles 12–18 and Regulations Articles 9–10 then determine expense relief, financing limitations, provisions, depreciation and restrictions. The accounting profit is the starting reconciliation, not the final tax base.
The deductions guide explains the main tests and links to detailed head-office, employee, bad-debt, financing and asset analyses. The exempt-income guide identifies ZATCA’s May 2026 examples and their limitations. An exempt dividend, a share-disposal gain and an outbound profit transfer require different conclusions.
Losses require eligibility and continuity
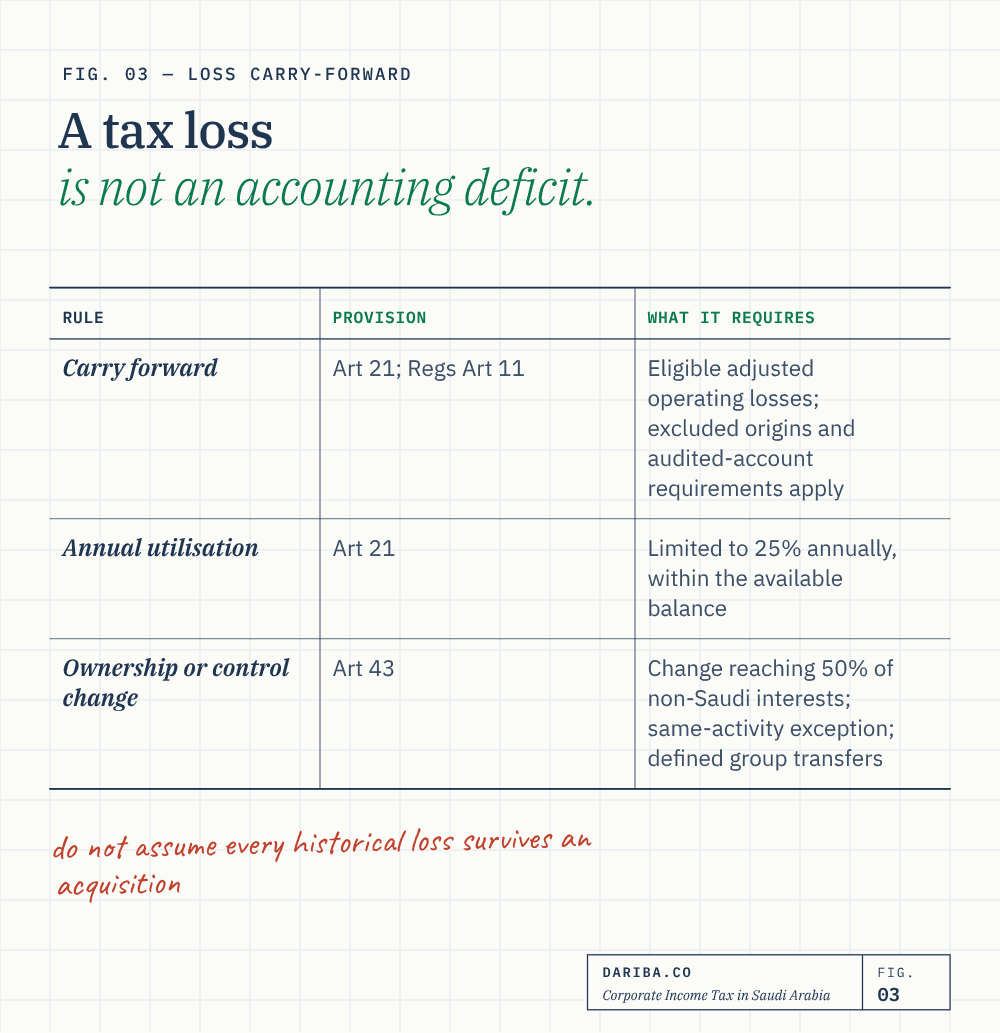
Law Article 21 and Regulations Article 11 permit eligible adjusted operating losses to be carried forward, subject to the 25% annual utilisation limit and the available balance. The tax loss is distinct from an accounting deficit. Excluded origins and audited-account requirements still apply.
Law Article 43 expressly addresses ownership or control changes reaching the stated 50% of non-Saudi interests, with a same-activity exception and defined group-transfer treatment. The loss guide explains that rule. Acquisition pricing and tax forecasts should not assume that every historical loss survives or produces a guaranteed effective tax rate.
Filing and payment need their own timetable
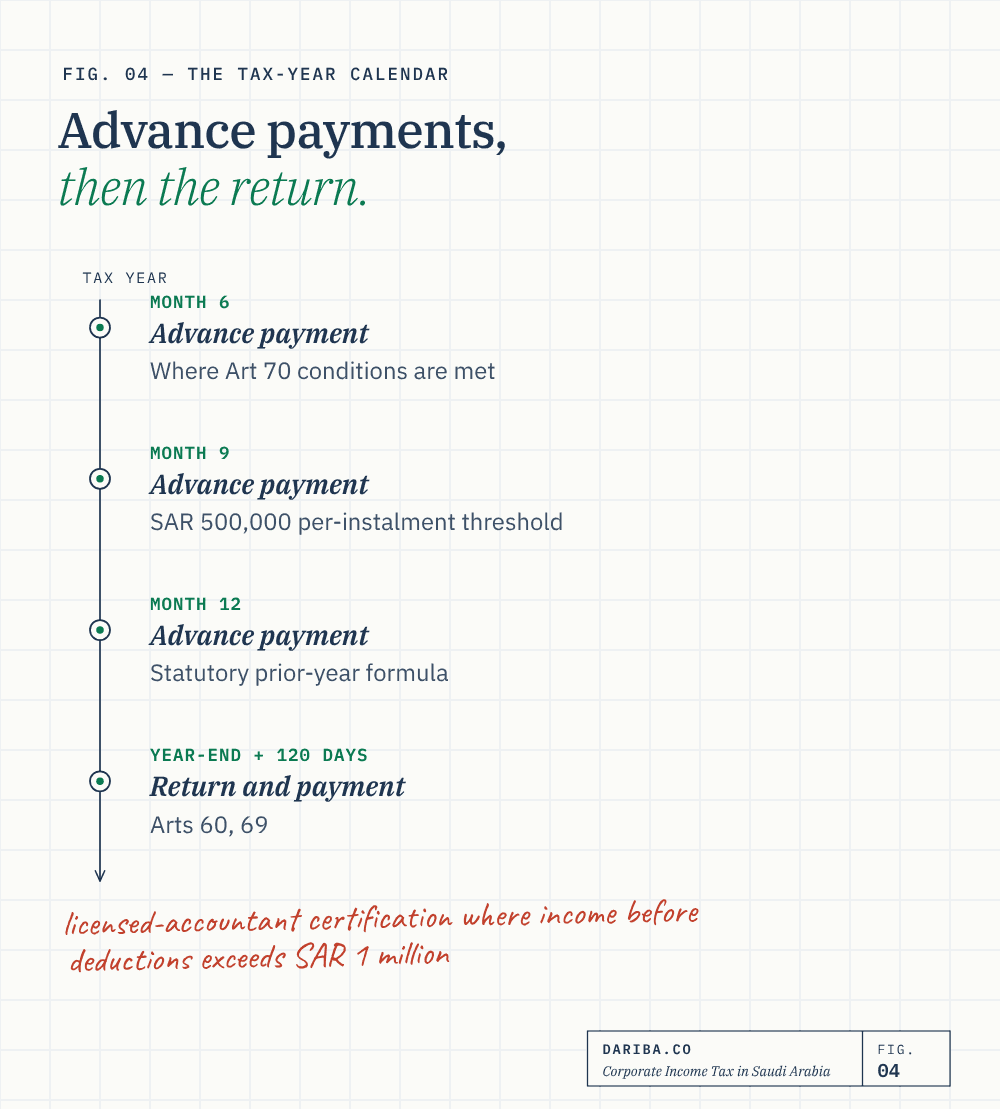
Law Articles 60 and 69 generally require the annual return and payment within 120 days of tax-year end. Cessation and partnership information returns have separate 60-day rules. Regulations Article 57(6) requires licensed-accountant certification where the relevant income before expense deductions exceeds SAR 1 million; it is not a net-profit test or a threshold beginning at exact equality.
Advance payments under Article 70 also have conditions: current-year revenue, the statutory prior-year formula, a SAR 500,000 per-instalment threshold and dates in months 6, 9 and 12. The return guide and advance-payment guide explain the separate obligations and evidence.
Withholding and branch distributions remain separate
Law Article 68 can require withholding by a resident or Saudi PE paying a non-resident from a Saudi source, even where the payer is not itself a CIT taxpayer. Expense deductibility does not automatically remove withholding. Regulations Article 63(6) also includes profits transferred from a PE to related parties within its dividend definition, subject to the particular rules and any actual treaty.
The branch guide explains why profit attribution, head-office costs and distributions should be modelled together. A branch should not be marketed as automatically free of profit-transfer withholding. Equally, a subsidiary’s payment to its parent is not deductible merely because it is invoiced at group level.
Identify the statutory authority and the instrument governing relief
Law Article 56 assigns ZATCA responsibility for income-tax administration, examination, assessment, collection and the statutory penalties. Paragraph (b) provides for a penalty decision by the Governor or a person authorised by ZATCA’s Board. The actual decision and applicable authorisation matter; an informal comment is not necessarily an approved tax outcome.
Article 79 addresses the Minister’s powers to issue the implementing regulations, necessary instructions and measures, change the Article 17 depreciation groups and rates, and write off tax and penalty debts where collection is impossible under the specified regulatory cases. It also addresses the stated employee-award framework. These are defined statutory powers rather than a general entitlement for each taxpayer to choose a preferred rate or relief.
The tax-debt write-off guide explains Regulations Article 70’s four cases and the ministerial-decision requirement. Keep that mechanism distinct from an instalment arrangement, an assessment challenge and a time-limited penalty initiative.
Apply the provision that governs the actual tax year
Law Article 80 distinguishes the original commencement of the Law from the tax years to which it applies. Regulations Article 74 identifies 30 July 2004 as the original commencement date: the Law and Regulations apply to tax years starting after that date, while the withholding provisions apply to amounts paid on or after it. Article 80(b) leaves tax years starting on or before the original effective date under the previously applicable tax rules.
Article 80(c) repeals the earlier enactments identified there: the former income-tax law, the additional income-tax law for oil and hydrocarbon producers, and the former natural-gas investment tax law. These original repeal provisions should not be confused with each later amendment or read as eliminating every present natural-resource tax obligation.
Dariba recommendation: for an old assessment, inherited tax attribute or acquisition, record the tax-year start and the relevant provision’s own commencement terms. Later amendments have their own dates and conditions; the original commencement date is not a universal effective date for every current rule. The loss guide also explains the excluded historical and tax-exemption-period loss origins reflected in Article 81(b)–(c) and Regulations Article 11(2).
Use the guidance as a decision process
Maintain an annual tax file covering ownership, residence, income classification, exemption evidence, deductions, financing, asset pools, losses, controlled transactions, withholding and payment credits. Reconcile it to the return and keep the supporting records accessible under the applicable requirements. The records and contract-disclosure guide addresses obligations that can also reach persons outside ordinary CIT filing.
The practical objective is a defensible conclusion for each material item with the correct provision, facts and period. These linked guides support that work; they do not certify every sector regime, country treaty, incentive or disputed transaction. Where the legislation or arrangement leaves a material question unresolved, document it and obtain specific advice or clarification.
For income recognition, the accounting and inventory guide, contract guide and related-party guide provide the more detailed statutory analysis. The RHQ and special-zone guides identify separate incentive conditions rather than a universal departure from the ordinary framework.
Key takeaways
- Identify the person, ownership, residence and statutory route first.
- The ordinary 20% rate applies to the relevant taxable base.
- The company computation remains separate from consolidated group accounts.
- Loss continuity has an express ownership-change rule.
- Advances have a formula and per-instalment threshold.
- Branch profit transfers can fall within withholding rules.
- Article6 distinguishes the company, resident individual, PE and separate production/gas bases.
- Article6(d) requires each person’s base to be computed independently; Article6(e) adds the capital-company rule.
Sources
- Saudi Income Tax Law, current amended Arabic textFocused Article 6(a)–(g),pp.7–8: company/individual/PE bases, person/company independence and separate production/gas bases. Retained scope, rates, income, deductions, losses and compliance analyses have their own linked guides and qualifications.
- Income Tax Implementing Regulations, current amended Arabic textArticle 5(4),p.5: residentcapitalcompany own/branch operations inside/outside Kingdom. Article 1(1)(c),1(3),57(8) and retained related rules distinguish independent computation, gas scope and reporting.
- ZATCA Simplified Guideline for Income Tax, second version May2026Overview sections1–4. Detailed taxpayer, income-source and base wording follows the controlling Law/Regulations rather than a universal accounting-profit assumption.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.