In brief
Articles 40 and 54 connect supply adjustments and their documents. Required notes are due by the following month’s fifteenth; supplier increases, supplier decreases and customer issuance-period adjustments follow distinct rules.
Credit and debit notes connect an adjustment to the original VAT invoice. Before choosing the document, identify what changed: consideration for an earlier supply, party data, an error in an earlier return, or simply an account balance. Those are different cases, with different consequences for tax and timing.
Articles 40 and 54 must be read together. The required note, its issuance deadline, the supplier’s reporting period and the customer’s input adjustment are related decisions; they are not always the same date.
Identify the event before choosing credit or debit
Article 40(1) addresses cancellation/suspension, a material change in the supply affecting tax, a change to agreed consideration and accepted returns. If an issued invoice’s tax exceeds the resulting tax, Article 54(1) requires a credit note; if it is lower, paragraph (2) requires a debit note.
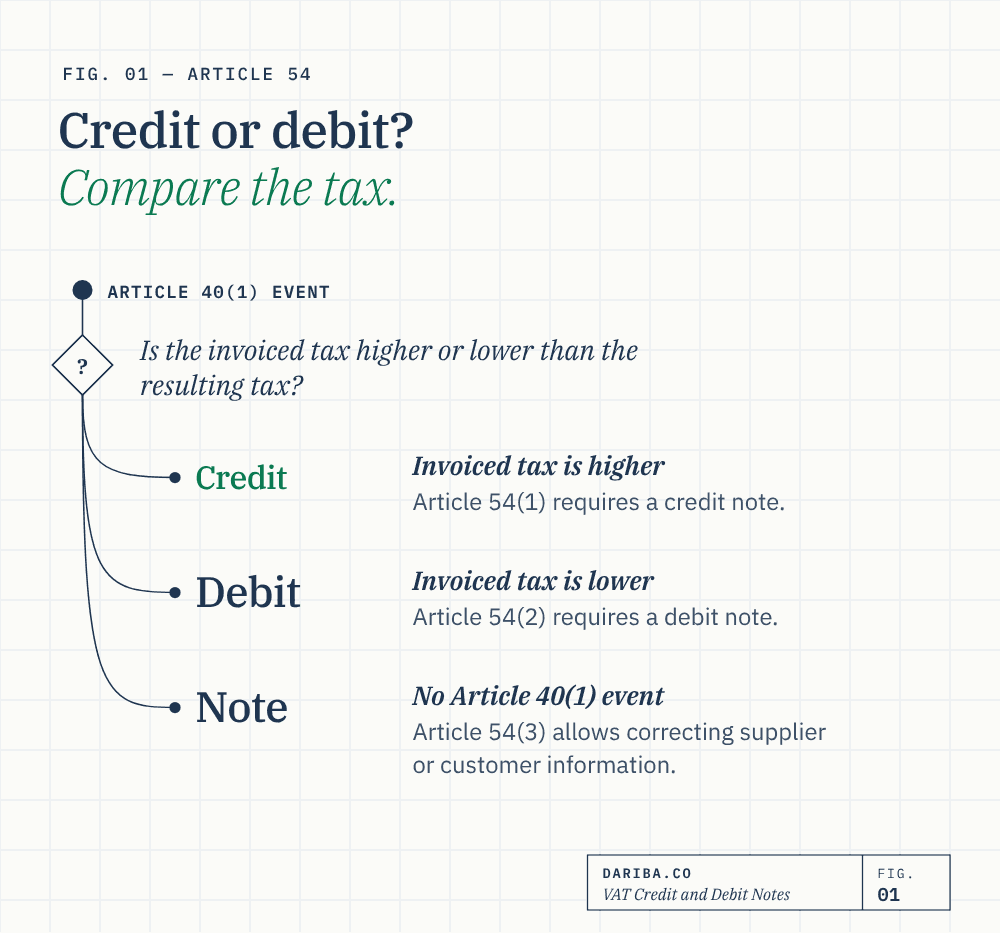
Article 54(3) separately allows a note to correct the supplier’s or customer’s information where the Article 40(1) events do not apply. Retain the original and corrective records. A party-data error does not itself mean the consideration or VAT has changed.
Sources: Arabic Regulations, Article 40, pp. 37–39; Article 54, pp. 58–59.
ZATCA’s examples: cancelled advance and price correction
Example 17, section 7.1 of the Tax Invoicing and Records Guideline, version 3, May 2026, p. 37, concerns a factory’s advance for a warehouse. The contractor issues an invoice for the advance, then withdraws before work starts and the supply is cancelled. A credit note relates back to the earlier invoice. The example confirms that an invoiced advance can need adjustment even before physical construction begins. Read Example 17.
On the same page, Example 18 describes Arab Union discovering in April 2022 that two items on a November 2021 invoice were underpriced. The parties agree a debit note referencing the original invoice and supply date. It explains the document link. It does not give a complete determination of every historical return-correction issue. Distinguish an actual later change in agreed consideration from discovery that the original tax declaration was wrong; the latter may require Article 63 analysis rather than treating every discovery as a new current-period event.
ZATCA’s boundary example: goodwill credit is not necessarily a VAT credit note
Example 19, section 7.1, p. 38, describes Al-Aziz Electronics granting SAR 200 credit to regular customers for Eid. It is not related to a previous supply, so ZATCA does not permit a credit note reducing VAT for it. Read Example 19.
Dariba’s analysis. An accounting label such as “customer credit” does not establish a tax adjustment. Identify the earlier supply and the actual change affecting it. A future promotion, compensation or other payment may need its own VAT classification; Example 19 does not classify every possible loyalty arrangement or compensation payment.
Contents, linked invoices and the issuance deadline
Article 54(4) requires the relevant invoice information according to the original invoice type and a clear reference to the related earlier invoice or invoices. The guideline’s section 7, pp. 36–37, specifies the note type and original invoice serial reference. Electronic requirements remain additional; do not treat a general customer-account credit without a supply link as sufficient.
Section 7.2.1, p. 39, permits one note covering multiple invoices for the same customer where those invoices and the adjusted amount are clearly identified. Example 21 illustrates multiple returned-goods supplies under different invoices consolidated into one credit note. This is not permission to lose the individual supply trail.
Under Article 54(6), required notes must be issued no later than the fifteenth day of the month following the event requiring them. Section 7.2, page 39, confirms that rule. The deadline is distinct from the supplier’s reporting period; delaying a debit note does not necessarily defer the extra output tax.
Sources: Article 54(4)–(6), pp. 58–59; guideline section 7.2 and Examples 20–21, p. 39.
Supplier and customer reporting periods
| Decision | Relevant rule for the described later adjustment |
|---|---|
| Supplier output tax increases | Article 40(4): period in which the triggering event occurs. |
| Supplier output tax decreases | Article 40(5): later of the event period and the period the credit note is issued to the customer. |
| Customer input adjustment | Article 40(6): correction for the relevant adjustment in the period the credit/debit note is issued, subject to the customer’s applicable treatment. |
The statutory customer rule refers to issuance, not a blanket rule that the period begins whenever finance receives the document. Retain issuance and receipt evidence and investigate delays; receipt timing can affect the practical evidence/procedure question, but it should not replace the controlling wording. A debit note also does not guarantee full additional input recovery: restrictions and attribution still apply.
ZATCA’s section 7.1.1, p. 38, also distinguishes documents issued in the same period or before filing the original return from later adjustments. Apply the appropriate return presentation and facts rather than forcing all cases into one later-period instruction. Read section 7.1.1.
Dariba illustration: June event, July note
Assume a monthly filer has already correctly invoiced and declared a domestic 15% supply. An accepted return of goods on 30 June reduces net consideration by SAR 4,000; the supplier issues the credit note on 10 July. The tax reduction is SAR 600 and the gross credit SAR 4,600. Under the described Article 40 adjustment, the supplier’s reduction falls in July, the later period. The customer’s relevant input correction also follows July issuance, with its original recovery treatment taken into account.
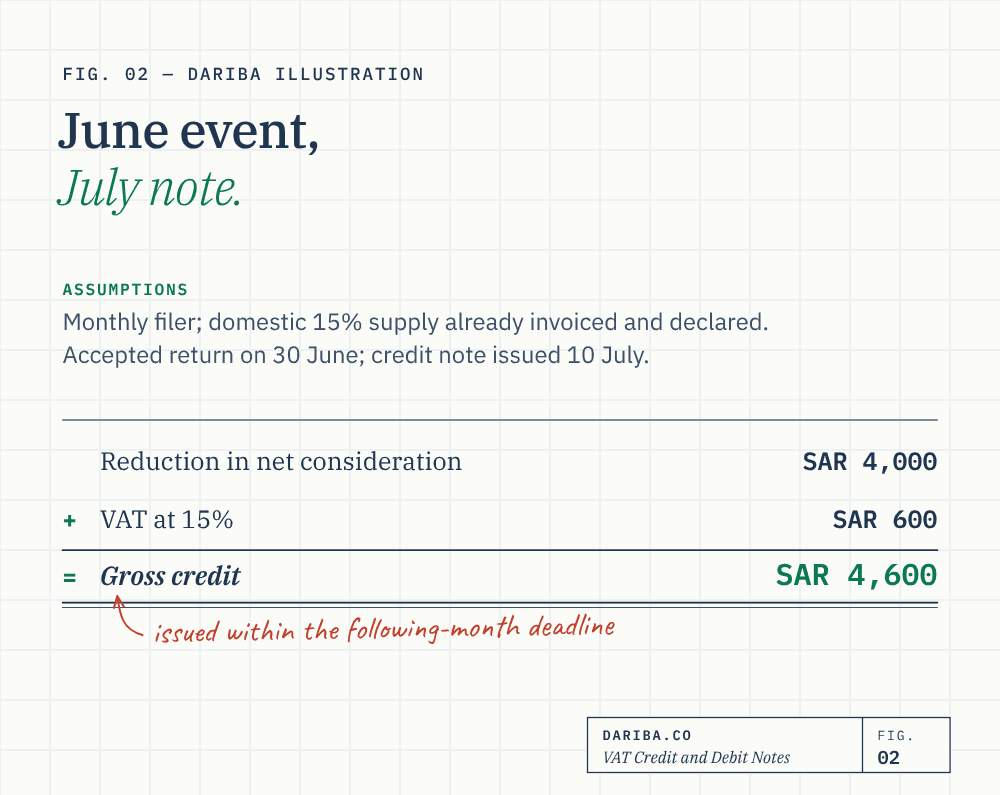
Change the facts to an actual agreed net price increase of SAR 4,000 on 30 June, with a debit note on 10 July. The additional output tax is SAR 600 in the June event period; July issuance does not move the supplier’s increase to July. The note is issued within the following-month deadline. These are Dariba’s original scenarios, not dates or amounts from ZATCA’s examples, and assume a genuine later adjustment rather than an error in the original declaration.
Keep non-payment and electronic procedures separate
Unpaid consideration has its own Article 40 rules. A customer’s input reduction under paragraph (10), any applicable financing exception and later reinstatement under paragraph (11) are not interchangeable with an ordinary credit note. The financing exception has conditions including the licensed provider, qualifying goods/contract, continuing agreement, no relevant judicial dispute and supplier declaration/certification; do not treat all long payment terms as exempt. Applicable time limits remain under paragraph (12).
Supplier bad-debt relief under paragraphs (7)–(9) is also a separate conditional route. Non-payment alone should not be converted into a fictional cancellation or price reduction.
For persons in the applicable electronic integration phase, standard invoices/related notes follow clearance and simplified invoices/related notes follow reporting under the published resolution. Preserve the original record, the note, supply/event evidence and electronic trail. This article does not prescribe a universal correction workflow or certify implementation. Continue to the invoice-type comparison and input claim timing.
Key takeaways
- Credit/debit treatment begins with the actual event; party-data corrections and earlier return errors are distinct.
- Official Examples 17-18 cover a cancelled advance and price correction; Example 19 rejects an unrelated Eid account credit as a VAT reduction.
- A note may adjust multiple invoices to the same customer with clear invoice and amount references; Example 21 illustrates the route.
- Article 54(6) requires notes by the fifteenth of the following month; that deadline does not postpone the supplier’s event-period increase.
- Article 40(6) uses the note’s issuance period for customer input correction, not a blanket receipt-period rule.
- The original SAR 4,000 June/July examples give SAR 600 VAT and SAR 4,600 gross, with distinct supplier timing.
- Non-payment, financing exceptions, bad-debt relief and electronic processes need their separate conditions.
Sources
- ZATCA - VAT Implementing Regulations, Arabic tenth edition, April 2025Controlling Arabic text: Article 49(7) p49; Article 53 pp55-58; Article 54 pp58-59; Article 40 pp37-39.
- ZATCA - Tax Invoicing and Records Guideline, version 3, May 2026Detailed types pp13-15,23-24; standard data pp16-20; timing pp25-27; notes and Examples 17-21 pp36-39; alternative evidence Example 22 p47.
- ZATCA - Published E-Invoicing Implementation Resolution, English translationClauses First/Second pp1-4; Annex 1 field1.2 p17. Current legislation page links this resolution; Arabic version prevails. No software/integration-date certification.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.