In brief
Article 53(2) permits self-billing subject to ZATCA approval, prior agreement and VAT registration of both parties. Supplier acceptance and prevention of duplicate invoices are essential.
Self-billing allows a customer to issue a tax invoice on a supplier’s behalf. Under Article 53(2), this depends on ZATCA’s approval, a prior agreement and VAT registration of both parties. It changes who prepares the invoice; the supplier still has a supply to report, and the customer’s input-tax entitlement still requires a separate assessment.
The arrangement can be useful where the customer holds the information needed to calculate the price, such as measured quantities or a contractual commission. Commercial convenience alone does not establish a compliant self-billing arrangement.
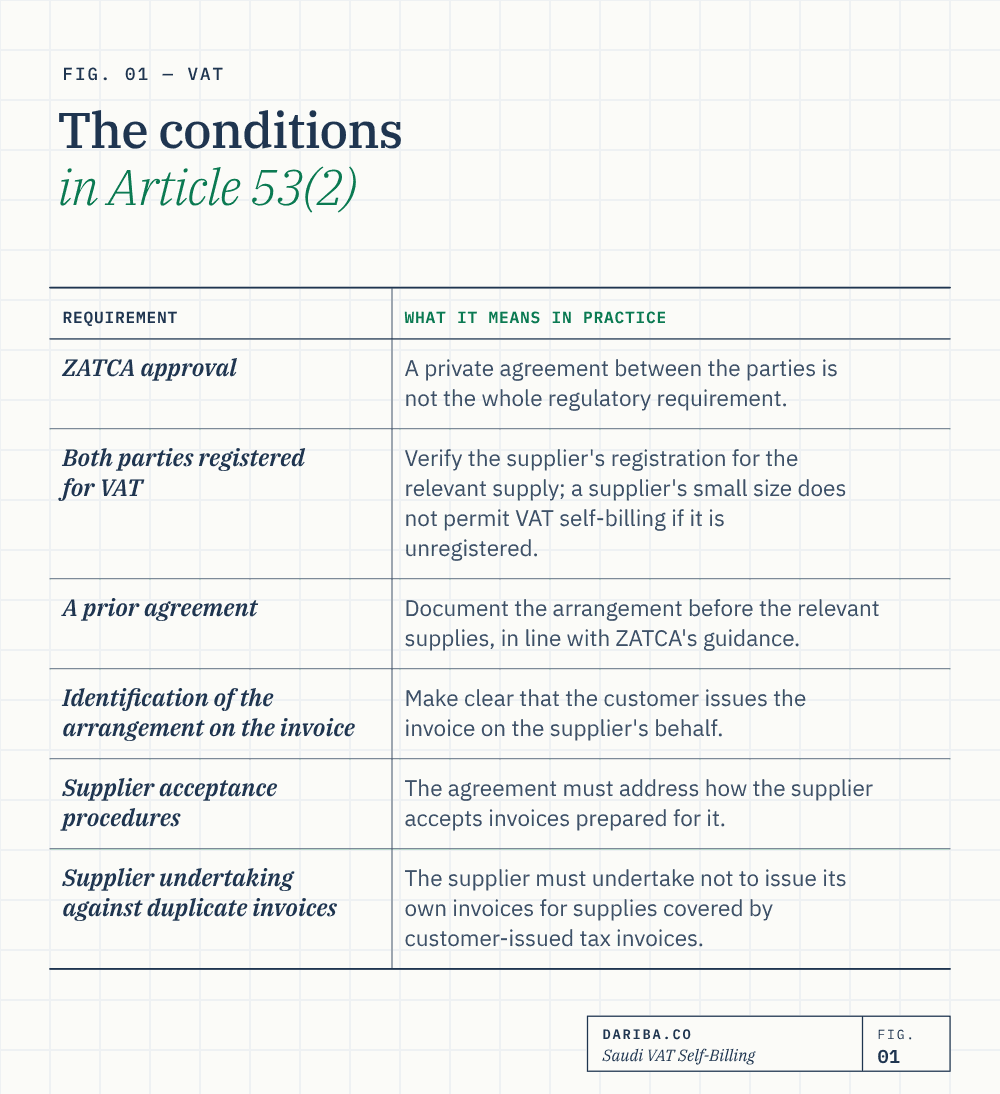
The conditions in Article 53(2)
The provision should be read as a set of cumulative requirements:
| Requirement | What it means in practice |
|---|---|
| ZATCA approval | A private agreement between the parties is not the whole regulatory requirement. |
| Both parties registered for VAT | Verify the supplier’s registration for the relevant supply; a supplier’s small size does not permit VAT self-billing if it is unregistered. |
| A prior agreement | Document the arrangement before the relevant supplies, in line with ZATCA’s guidance. |
| Identification of the arrangement on the invoice | Make clear that the customer issues the invoice on the supplier’s behalf. |
| Supplier acceptance procedures | The agreement must address how the supplier accepts invoices prepared for it. |
| Supplier undertaking against duplicate invoices | The supplier must undertake not to issue its own invoices for supplies covered by customer-issued tax invoices. |
Source: VAT Implementing Regulations, Article 53(2), Arabic consolidated text, printed page 49.
How ZATCA’s guidance explains the arrangement
Section 5.1 of the May 2026 Tax Invoicing and Records Guideline describes notification of the agreement to ZATCA under the procedures it specifies, alongside the approval requirement. It says that if ZATCA rejects the notification, the customer must refrain from issuing the invoices. The examples also refer to notification and approval.
Do not infer a universal approval timetable, an automatic approval rule or a particular submission route from that description. The parties should establish the procedure and conditions applicable to their arrangement and retain the resulting correspondence.
The guidance also requires a taxable supply by a taxable supplier, issuance within the applicable invoicing timetable, identification of the invoice as self-billed and the content required for a standard tax invoice. Self-billing cannot be used to turn an unregistered supplier’s commercial receipt into an invoice charging Saudi VAT.
Source: Tax Invoicing and Records Guideline, section 5.1, pages 27-29.
What the agreement should cover
ZATCA’s section 5.1.1 calls for a documented agreement retained in the parties’ records. It should identify the relevant supplies and duration, confirm the parties’ VAT registration details, contain the supplier’s undertaking against duplicate tax invoices and establish the invoice-acceptance process.
As a practical drafting matter, also identify who handles quantity disputes, corrections, credit notes and changes to registration details. Those additional controls help operate the arrangement; they should not be confused with a quoted statutory list.
Invoice content and e-invoicing
The invoice represents the supplier’s supply. Identify that supplier and its VAT registration number correctly, together with the applicable customer details. The parties’ identifiers must correspond to their respective roles in the transaction. A rule preventing an unrelated billing agent from substituting its own supplier identity does not mean that a self-billing customer’s required details should disappear.
Use the required self-billing identification and comply with the standard invoice content requirements together with the applicable electronic invoicing requirements. The e-invoicing implementation resolution restricts the self-billing option to cases where both parties are VAT registered and excludes it from simplified tax invoices.
Before implementation, check the applicable electronic invoice specifications and integration obligations for the parties. An Article 53 agreement is not, by itself, evidence that the software workflow complies with those requirements.
A separate numbering series is a useful operational control for distinguishing purchase-side self-billing from the customer’s own sales invoices. Article 53(5)(b) requires a sequential number uniquely identifying the invoice; the separate-series recommendation should not be presented as the wording of Article 53(2).
Source: E-Invoicing Implementation Resolution, Annex 1, field 1.2, p. 17. ZATCA’s current legislation page links this resolution; the English text is a translation and the Arabic version prevails. This article does not certify a complete electronic implementation or a taxpayer’s integration date.
ZATCA’s example: the hotel and laundry supplier
Example 10 in section 5.1.1 of the Tax Invoicing and Records Guideline (version 3, May 2026, page 29) describes a three-year laundry contract between Al-Saah Laundry Company and Al-Jaber Hotel. Following ZATCA notification and approval, the hotel issues monthly invoices for the laundry company using agreed item prices. The laundry company checks them against its records and accepts them. This is a paraphrase of the official example, with its core facts retained. Read ZATCA’s example.
The significance is the supplier’s continuing involvement. Customer preparation is followed by supplier verification; the example is not a model in which the supplier abandons responsibility for the document. Read with section 5.1.1, it supports an acceptance process that connects the customer’s calculation to the supplier’s records and tax reporting.
Dariba’s analysis. A business considering self-billing should evaluate whether both parties can operate that process reliably throughout the contract. For example, an agreed price per item is useful only if the parties can reconcile the relevant quantities and correct differences. We recommend defining the records used, the person responsible for review and how discrepancies are resolved. These are practical ways to implement the acceptance requirement, rather than additional prescribed conditions or an official ZATCA contract template.
The example does not create a right to defer the statutory tax point or invoicing timetable while an internal approval remains outstanding. Those questions still require the applicable timing rules. Nor does a three-year agreement establish that registration details can go unchecked for three years: the registration conditions continue to matter for the supplies covered.
Dariba illustration: applying the framework to component purchases
Assume a Saudi manufacturer purchases components from another Saudi business. Both are VAT registered. The manufacturer measures accepted quantities, while the supplier checks those quantities against dispatch records. Before the covered supplies, the parties document the arrangement, satisfy the applicable ZATCA approval and notification requirements, and agree how the supplier accepts each invoice.
The manufacturer can then prepare the self-billed invoice under that arrangement. The supplier checks it and reports the output tax. The manufacturer assesses input-tax recovery under the ordinary entitlement and evidence rules. Self-billing does not guarantee recovery.
This is Dariba’s original illustration, extending the same contractual and acceptance framework to different facts; it is not another ZATCA example or evidence of approval for a particular manufacturing arrangement.
Change one fact: the component supplier is not VAT registered. The manufacturer cannot use this arrangement to issue a VAT tax invoice charging tax on that supplier’s behalf. The registration condition has failed, even if the commercial purchase itself is valid.
ZATCA’s barter example: preserve both supplies
In Example 12, section 5.1.1, pp. 29–30, Al-Rashid Petrochemicals and Al-Fajr exchange products used in each other’s production. Under the stated approved/notified self-billing arrangement, Al-Rashid issues its sales invoice and the self-billed invoice for its purchases. ZATCA requires the invoices to reflect the market value of each supply separately, rather than the net set-off. Each party declares its own supply and tests the conditions for deducting the other’s VAT. Read Example 12.
The implication is that a commercial net settlement does not collapse two supplies into one. Dariba’s original numerical illustration: assume both supplies are ordinary domestic standard-rated transactions and their correctly determined values are SAR 20,000 and SAR 12,000, exclusive of VAT. The invoices show SAR 3,000 and SAR 1,800 VAT respectively, with gross amounts of SAR 23,000 and SAR 13,800. A commercial set-off could leave SAR 9,200 to settle, but it would not justify recording only SAR 8,000 of taxable supplies and SAR 1,200 VAT as the entire transaction. Those figures are Dariba’s, not figures stated in Example 12. Input recovery remains a separate entitlement decision for each party.
Supplier responsibility and third-party invoicing
ZATCA’s guidance keeps responsibility with the supplier for checking the information and declaring the tax. Duplicate documents should be investigated and corrected through the applicable process; their existence should not be described as automatically creating two separate supplies or doubling the underlying tax.
Article 53(3) separately addresses invoicing through a third party, subject to ZATCA’s approval and compliance with the legal requirements. An outsourced billing provider and a customer acting under a self-billing agreement have different roles. In either case, establish the supplier’s reporting responsibilities rather than assuming that outsourcing the document transfers them.
For the wider requirements, see VAT invoicing in Saudi Arabia.
Key takeaways
- Article 53(2) makes self-billing subject to ZATCA approval and VAT registration of both parties.
- The agreement must establish supplier acceptance procedures and an undertaking against duplicate invoices.
- Follow ZATCA notification procedures and stop issuing if the notification is rejected.
- The supplier retains responsibility for checking information and declaring output VAT.
- Self-billing does not establish the customer's input-tax entitlement.
- Check standard invoice and applicable electronic invoicing requirements; simplified tax invoices cannot use the self-billing option.
- ZATCA's Example 12 preserves each barter supply separately; net settlement does not replace gross supply invoicing.
Sources
- ZATCA - VAT Implementing Regulations, Arabic consolidated edition (April 2025)Controlling Arabic text; check the cited article and applicable transaction period.
- ZATCA - Tax Invoicing and Records Guideline, version 3, May 2026Sections 5.1, 5.1.1 and 5.2, pages 27-30; Example 10 in section 5.1.1 on page 29.
- ZATCA - E-Invoicing Implementation Resolution, English, 19 May 2023Annex 1, field 1.2, page 17: self-billing flag and registration restrictions. Check applicable later technical specifications before implementation.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.