In brief
VAT filing and payment retain their date on non-working days under Article 74(1). The next-working-day route for other obligations, the Friday/Saturday/holiday definition and express business-day periods require separate analysis.
Saudi VAT filing and payment are separate obligations with the same ordinary deadline: the last day of the month following the tax period. Importantly, Article 74(1) requires those obligations by their prescribed date even when that date is a non-working day. A weekend does not automatically move them to the next working day.
The return must also use the correct tax period, classification, output tax and deductible input amounts. Filing an accurate-looking total in the wrong period, omitting required disclosures or assuming every foreign invoice is fully recoverable can produce an incorrect self-assessment.
The deadline and the weekend rule
Articles 62(1) and 59(1) establish the ordinary filing and payment deadlines respectively. Article 74(1) expressly applies those dates whether working or non-working. Paragraph (2)‘s next-working-day treatment concerns other obligations outside paragraph (1); it is not a general VAT-return/payment extension.
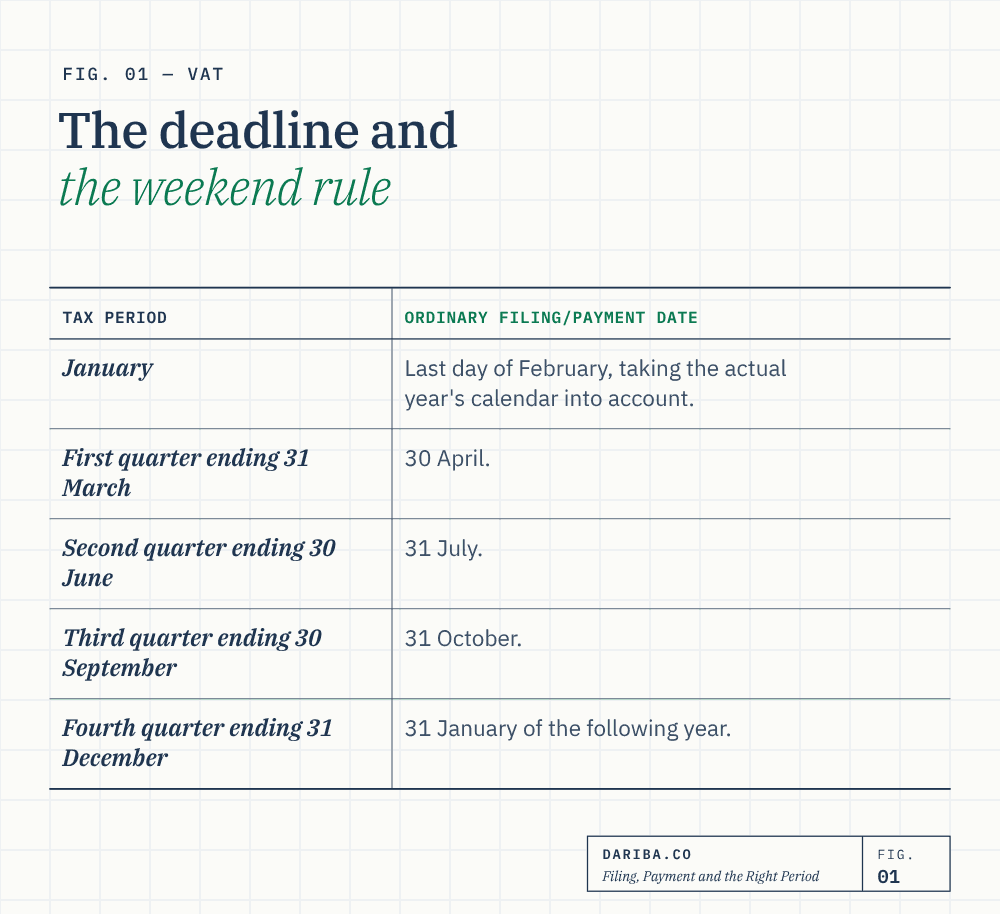
| Tax period | Ordinary filing/payment date |
|---|---|
| January | Last day of February, taking the actual year’s calendar into account. |
| First quarter ending 31 March | 30 April. |
| Second quarter ending 30 June | 31 July. |
| Third quarter ending 30 September | 31 October. |
| Fourth quarter ending 31 December | 31 January of the following year. |
Current-period official example. In its 20 October 2026 announcement, ZATCA confirms 31 October 2026 for the September monthly and third-quarter returns it describes. That date is a Saturday. This directly illustrates why the article must not advise waiting until the following working day solely because of the weekend. Read the official announcement. Any specific valid extension must be assessed on its own terms; a weekend by itself is not one.
Sources: Arabic VAT Regulations, Articles 59 and 62, pp. 61 and 63; Article 74, p. 78.
Working days and calendar days are different clocks
Article 74(3) defines a working day as a day other than Friday, Saturday or an official state holiday. Paragraph (2) addresses an obligation outside paragraph (1) that falls on a day when both the taxable person and ZATCA are not working: performance on the next working day is treated as timely under that rule. Do not omit the condition concerning both parties or apply the rule to the filing and payment obligations expressly addressed in paragraph (1).
Dariba illustration: assume an obligation covered by paragraph (2) falls due on Friday 19 June 2026, both parties are not working on that date, Saturday is also excluded, Sunday 21 June is a working day and no other applicable rule changes the result. Performance on Sunday meets the described next-working-day rule. These are Dariba’s assumed facts, not an actual ZATCA notice or confirmation of every holiday applicable to a particular taxpayer. The example does not move the separate 31 October 2026 VAT-return/payment deadline discussed above.
The unit used by each provision also matters. Article 63(1)‘s twenty-day correction requirement is not written as twenty business days, while Article 70(15)‘s designated-person evidence response expressly uses twenty business days. Article 74(2)‘s treatment of an endpoint does not rewrite every day within a calendar-day period as a working day. Objections under the committee framework have their own procedural time rules and must be checked separately.
Sources: Article 74(1)–(3), p. 78; Article 63(1), pp. 63–64; Article 70(15), p. 74.
Establish the correct monthly or quarterly period
Article 58 uses taxable annual supplies over the preceding twelve months. Where they exceed SAR 40 million, the ordinary period is monthly; other taxpayers ordinarily use three-month periods. Exactly SAR 40 million does not exceed that threshold.
An eligible taxpayer can apply to use monthly periods, but the request is not itself the effective change. The approval/notification and effective period matter. A monthly filer seeking quarterly treatment must satisfy the applicable two-year and supply-value conditions, and ZATCA can also direct a period by notice. Do not switch the return frequency in a spreadsheet without matching the authorised position.
Source: Article 58(1)–(7), pp. 60–61.
Build a return from classified transactions
Article 62(2) identifies the required information, including taxable supplies/output tax, received goods/services and deductible input tax, nominal supplies, reverse-charge supplies, relevant intra-GCC/import information, exempt supplies and applicable adjustments/corrections. The current form should be populated from that legal classification rather than treating every cash receipt as taxable sales or every expense as fully deductible purchases.
An exempt amount is not simply a zero-rated amount. A correctly issued simplified invoice can support otherwise eligible input evidence under Article 49(7)(a); it should not be excluded merely because it is simplified. Conversely, a standard invoice cannot establish recovery of a blocked cost or an exempt-use input.
Tax points also matter. Invoice-based reporting does not mean using only the day a document enters the ledger. Earlier supply, invoice or advance events and special/continuous rules require their own analysis. If the taxpayer validly uses cash accounting, apply its actual conditions and payment-based treatment consistently rather than selecting it informally because customers pay slowly.
Source: Article 62, p. 63; Tax Invoicing and Records Guideline, version 3, May 2026, sections 9–10, pp. 44–49.
ZATCA’s reverse-charge example: reporting is not automatic full recovery
Example 7, section 6.3 of the Imports and Exports Guideline, second edition, May 2026, pp. 32–33, concerns Al-Safaa Bank’s SAR 100,000 British legal-services invoice in June 2018. The example uses the historical 5% rate and 70% entitlement on non-attributable costs. ZATCA shows the 30% non-deductible portion through the Field 9 adjustment, giving SAR 1,500 net VAT payable. Read the official example.
The SAR 1,500 is the net result, not the total reverse-charge output. The historical output calculation is SAR 5,000 and the deductible amount SAR 3,500. Those arithmetic steps explain the official result; the 5% rate belongs to its 2018 facts, not a current-rate instruction.
Dariba’s original current-rate extension: on an assumed otherwise comparable SAR 100,000 taxable service at 15%, output is SAR 15,000, 70% input recovery is SAR 10,500 and the net is SAR 4,500. Actual recipient, place-of-supply, exemption and use conditions must first be established. A foreign invoice alone does not prove that reverse charge applies, and a recovery restriction does not eliminate the output obligation.
Distinguish payment difficulty from permission to file late
Filing and payment should each be completed by the applicable deadline. Article 60 concerns an application to pay in instalments, supported by the required facts; it is not a general extension to file the return. An application or internal cash-flow difficulty does not itself suspend either obligation.
Where no return is filed, ZATCA can issue a best-estimate assessment while the filing obligation remains. Article 64(5) permits withdrawal of the relevant estimate after a complete return for the same period is filed; withdrawal is not an automatic consequence to assume without checking the account and decision.
Source: Articles 60 and 62, pp. 62–63; Article 64(5), p. 65.
Reconcile, submit and preserve the evidence
Dariba recommends a reconciliation from classified sales/purchases to the return, including imports, reverse charge, restricted/direct/shared inputs, adjustments and tax-account credits. Review unexpected zero or missing figures rather than assuming a pre-filled value establishes the correct law.
Separate an ordinary later input deduction, a genuine later supply adjustment and correction of an incorrect earlier return. Article 63’s less-than-SAR-15,000 exception uses the discovery-period return, not any convenient next filing. The correction guide explains the distinction.
Retain the submitted return, acknowledgement, payment evidence, reconciliations and supporting records. A refund position is a further procedural step under Article 69, not proof that every input amount is recoverable. Continue to refund claims and the assessments overview.
Key takeaways
- Article 74(1) preserves VAT filing/payment deadlines on non-working days; paragraph(2)’s next-working-day rule excludes those obligations.
- ZATCA’s 20 October 2026 announcement confirms 31 October 2026 for the described September monthly and third-quarter returns.
- Taxable supplies exceeding SAR 40 million over the preceding twelve months ordinarily require monthly periods; changes require the applicable approval/notice.
- A foreign invoice does not automatically create reverse charge or full input recovery; actual taxable nature, place and use control.
- Official Example 7 uses 2018’s 5% rate and 70% recovery to produce SAR 1,500 net; Dariba’s assumed 15% extension gives SAR 4,500 net.
- Article 60 concerns payment instalments, not an automatic filing extension. Missing-return estimates and later withdrawal require their own conditions.
- Article74(3) excludes Friday, Saturday and official state holidays; paragraph(2)’s separate other-obligation rule requires its actual conditions.
Sources
- ZATCA - VAT Implementing Regulations, Arabic tenth edition, April 2025Current Arabic Article 74(1)–(3), p.78: distinct filing/payment and other-obligation rules, and working-day definition; Article 63(1) calendar-day wording versus70(15) express business days. Existing filing, input and example qualifications retained.
- ZATCA - Tax Invoicing and Records Guideline, version 3, May 2026Sections 9-10 pp44-49; filing and credit/refund explanation p49. Primary legislation controls the detailed routes.
- ZATCA - Imports and Exports Guideline, second edition, May 2026Section 6.3 Example 7 pp32-33 preserves historical2018 rate; section10.5 p60 supports recurring exporter credit/refund explanation.
- ZATCA - Input Tax Deduction Guideline, third version, May 2026Evidence, restrictions, attribution and later first deductions remain separate from refund/correction procedures.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.