In brief
Article 58 uses preceding-twelve-month taxable supplies and specific approval/direction rules. Monthly filing can affect claim timing but does not guarantee refunds or replace transaction tax points and ordinary deadlines.
Article 58 determines whether a taxable person uses monthly or quarterly VAT periods. The main threshold is the value of annual taxable supplies during the preceding twelve months, with specific application and notification rules for changes. Filing frequency affects the compliance timetable; it does not change the tax rate, create input entitlement or guarantee a faster refund.
Apply the SAR 40 million threshold to the right measure
Article 58(1) requires monthly periods where annual taxable supplies exceed SAR 40,000,000 during the previous twelve months. Paragraph (2) sets a three-month period for other taxable persons, subject to the applicable change/direction rules.
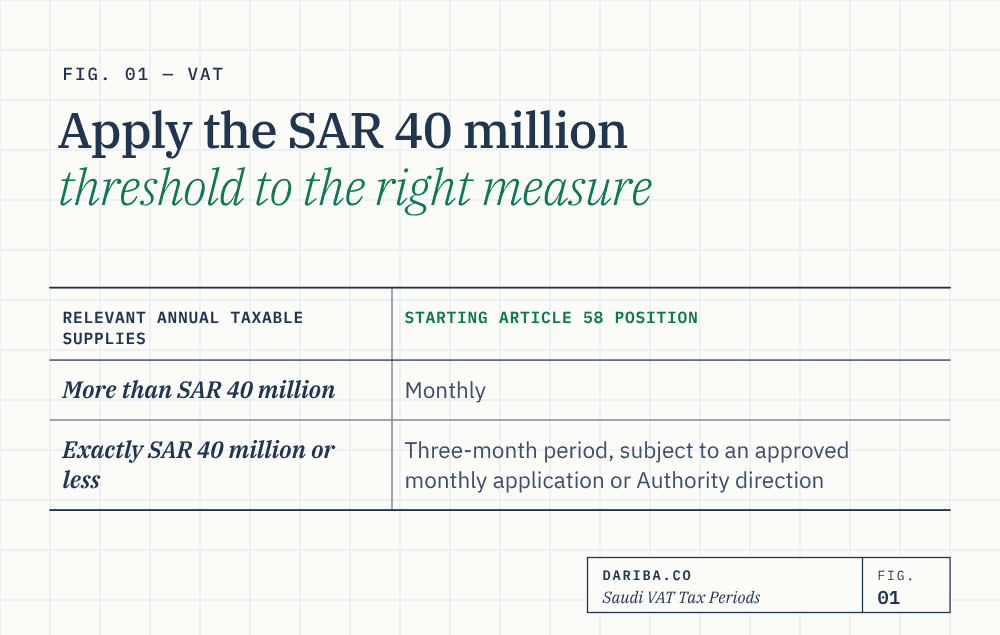
| Relevant annual taxable supplies | Starting Article 58 position |
|---|---|
| More than SAR 40 million | Monthly |
| Exactly SAR 40 million or less | Three-month period, subject to an approved monthly application or Authority direction |
Use taxable supply values, including qualifying zero-rated supplies, rather than treating the bank balance, total cash receipts or every accounting revenue item as the statutory measure. Exempt supplies are different. This threshold also differs from the SAR 375,000 mandatory-registration threshold; crossing one test does not mean both tests have the same consequence.
Dariba illustration — original assumptions: a business has SAR 35 million taxable supplies and SAR 25 million exempt supplies in the relevant twelve months. Its SAR 60 million combined income does not make its taxable supplies exceed SAR 40 million. Conversely, SAR 40.1 million of qualifying taxable supplies exceeds the period threshold even if most are zero-rated.
Monitor the preceding twelve months and actual notifications
The statutory test is not simply the previous audited calendar year’s total. Keep a supported preceding-twelve-month schedule, with the classification of relevant supplies and reconciliation to returns/accounts. Do not invent a rule that changes only when the auditor signs annual statements.
If the mandatory condition changes, reconcile the correct period with ZATCA’s account and any notification promptly. Do not assume a mismatch permits continued quarterly reporting indefinitely or permits filing overlapping monthly and quarterly returns for the same supplies. Preserve the applicable start/end dates and resolve discrepancies through the available Authority process.
Article 58(7) requires a notification identifying the effective date where ZATCA directs a particular period. That is a separate power; it is not evidence that every threshold crossing follows a universally identical administrative sequence or that the direction power is rarely exercised.
Applying for monthly filing below the threshold
Article 58(3) permits a person not exceeding the threshold to apply for monthly periods. Paragraph (4) provides for ZATCA’s approval notification and an effective date at the beginning of the tax period following the period in which approval is granted. The application itself does not change the period immediately.
ZATCA’s Examination, Assessment, Correction and Objection on VAT Decisions guideline, version 3 May 2026, section 4.1.1, pp. 13–14, explains the application and notes its potential benefit for persons regularly in a refundable position. That is guidance on possible commercial benefit, not an assurance of monthly cash repayment.
Dariba analysis: compare the timing of a valid claim with the cost of preparing additional reconciliations. Monthly filing may bring forward an opportunity to request a refund, but the actual credit, supporting evidence, Article 69 review/approval and other liabilities still matter. Do not model the filing date as a guaranteed bank-credit date.
Moving from monthly back to quarterly
Article 58(5) permits an application after using the monthly period for two years, provided annual taxable supplies during the last twelve months do not exceed SAR 40 million at the application date. Both conditions matter; being below the threshold alone does not automatically change the existing monthly account.
Paragraph (6) requires the approval notification and its effective date at the start of the tax period following the approval period. Keep filing under the applicable current schedule until the authorized change takes effect. A submitted request, expected approval or commercial preference is not the same as the notification.
The examination guideline section 4.1.1, p. 14, confirms the two-year condition and the supply-value test. A later change in supplier status, group membership or business structure may require its own analysis; it should not be treated as an automatic shortcut around the actual period conditions.
Separate the period from filing and payment deadlines
Articles 59(1) and 62 generally require payment and filing by the last day of the month following the tax period. A monthly period and quarterly period can therefore produce the same calendar deadline for different covered months.
For example, September 2026 monthly and July–September 2026 quarterly liabilities share an ordinary 31 October 2026 deadline. Article 74(1) specifically addresses filing/payment deadlines; do not automatically roll this Saturday deadline to the next working day using the different rule for other obligations. Check any actual official extension or specific notice rather than creating one from the calendar.
The return-filing guide explains the current deadline position and official announcement. A valid nil or refundable position does not itself remove the duty to file the applicable return.
Do not let filing frequency replace transaction tax points
Monthly or quarterly filing groups the reportable transactions; it does not replace their legal tax points. Ordinary supplies, advances, continuous supplies, value adjustments and corrections retain their actual rules.
Changing period does not permit deferring three months of imported-service reverse charge into an annual journal or claiming input tax solely when convenient. Nor does a quarterly period require every invoice from that quarter to be deducted regardless of evidence and entitlement. See the continuous-supplies and reverse-charge return guides.
Document transactions falling around a period change carefully so the final old-period return and first new-period return form a continuous, non-overlapping record. Carry-forward credits, unpaid balances and correction history should reconcile across the change.
Compare the operational cost with the actual cash-flow case
Dariba illustration: over a full ordinary year with no special first/last period or change, monthly filing means twelve returns and quarterly filing four. That is eight additional submissions, but quarterly filing still benefits from a monthly internal close and transaction review.
A payment business should forecast the actual tax points and due dates, not assume a permanent cash advantage from quarterly status. A refundable business should forecast eligible credits, claim preparation and possible review rather than assuming three times faster refunds. Both need reliable invoice, reverse-charge and input-attribution processes.
Period choice does not guarantee stronger compliance. The quality of the underlying records and reconciliations matters more than a claim that monthly filers always detect errors earlier.
Keep a period-change evidence file
Retain the twelve-month taxable-supply calculation, current account periods, application, supporting documents, approval/direction notice and effective date. Reconcile the closing and opening returns, credits, payment references and outstanding corrections.
Article 66 records requirements remain separate from period choice, while Article 63 governs actual errors. If the account and legal calculation disagree, resolve the discrepancy with evidence rather than submitting an unsupported return or silently changing periods. The objective is a defensible timetable tied to the actual Article 58 conditions.
Key takeaways
- More than SAR 40 million of preceding-twelve-month taxable supplies triggers the monthly Article 58 position; exactly SAR 40 million differs.
- Exempt income and accounting receipts are not interchangeable with taxable supply values.
- Below-threshold monthly applications and quarterly reversion require their actual conditions and approval dates.
- The quarterly reversion application requires two years of monthly use and the supply-value condition.
- Monthly filing does not guarantee immediate cash refunds or change individual tax points.
- Filing/payment deadlines and other obligation deadlines have different Article 74 treatment.
Sources
- Controlling Arabic VAT Implementing RegulationsTenth edition April 2025. Article 24 pp. 24–25; Articles 49-52 pp. 48–54; Article 58 pp. 60–61; Articles 59,61-63,66,69,74 for actual timing, evidence and procedure.
- Official Arabic VAT LawArticle 27 tax periods and reasoned Authority change power; Article 9 own-name agency read with actual marketplace provisions.
- ZATCA Examination and Assessment guidelineVersion3 May2026, sections4.1-4.1.1 pp. 13–14: monthly/quarterly threshold, applications, two-year condition and Authority notifications.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.