In brief
Apply Article 51 to eligible shared costs after restrictions and non-economic use. The default method uses prior-calendar-year supply values, with a current-year reconciliation and specific exclusions.
Input VAT apportionment begins with identifying how costs are used. A turnover ratio is applied to the eligible shared-cost pool after restricted, non-economic and directly attributable items have been dealt with. Applying one percentage to the entire purchase ledger can both deny valid recovery and create overclaims.
Article 51 provides the taxable/exempt allocation framework. The first three paragraphs distinguish full attribution to qualifying taxable supplies, direct attribution to exempt supplies and costs requiring proportional deduction. The remaining paragraphs address the calculation, annual adjustment, alternative methods and specified incidental activities.
Separate the costs before calculating the fraction
| Cost classification | Recovery approach |
|---|---|
| Article 50 restriction applies without an exception | Exclude the restricted input tax; the turnover ratio does not cure the restriction. |
| Wholly non-economic activity | No deduction for that use. If a cost also serves the business, identify a reasonable economic-use allocation first. |
| Exclusively and directly attributable to qualifying taxable supplies | Deduct in full, subject to the other entitlement and evidence conditions. |
| Exclusively and directly attributable to exempt supplies | No deduction under Article 51(2). |
| Eligible shared costs serving taxable and exempt activities | Apply the relevant proportional deduction method. |
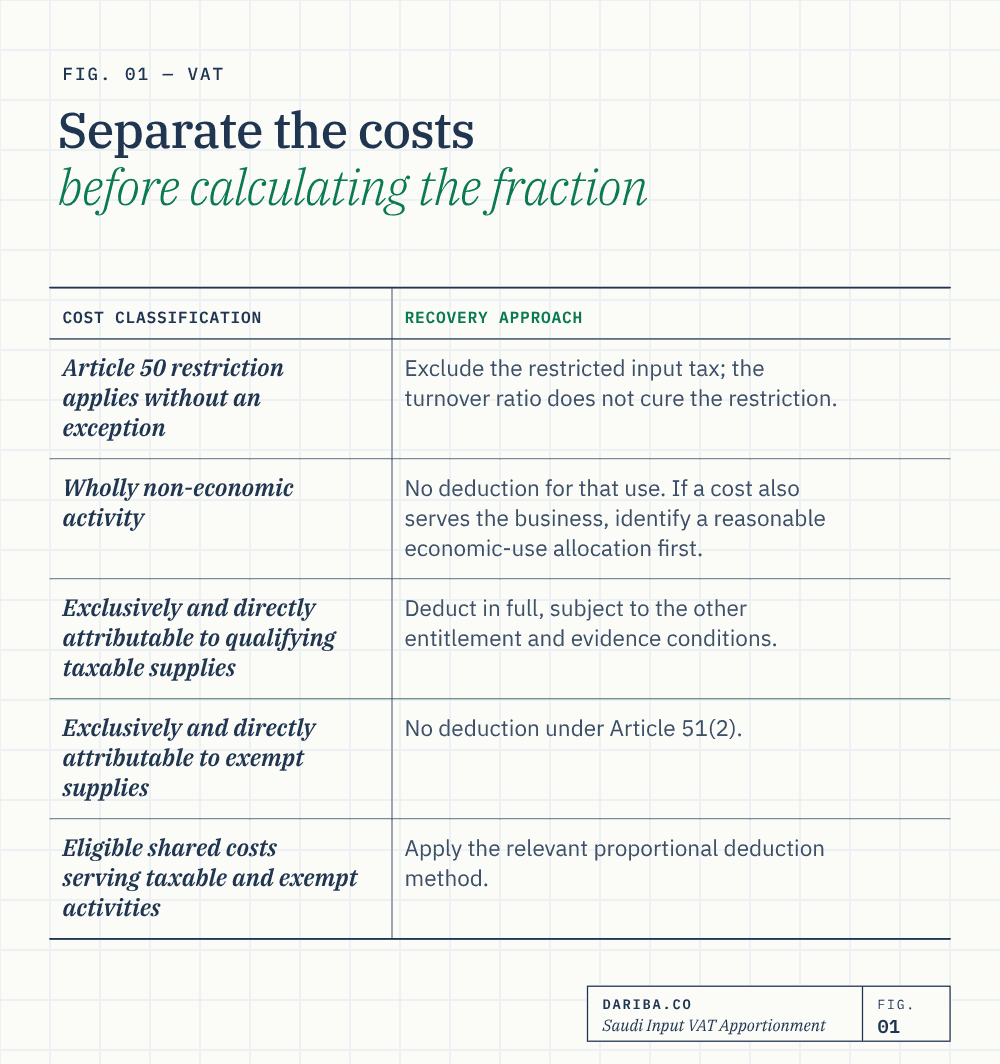
ZATCA explains the separate economic/non-economic step in section 12.1 and the taxable/exempt step in section 12.2 of the Input Tax Deduction Guideline, third version, May 2026, pages 47-49. Costs and their use must be classified; the presence of taxable turnover does not make all costs deductible. Read the framework.
Commercial and exempt residential leasing provide a useful mixed-business example. Do not assume that whole sectors such as healthcare or education are exempt for this purpose: classify the actual supplies under the relevant rules. Similarly, employees’ salaries do not themselves carry input VAT, although VAT-bearing services used by the finance team can be shared costs.
The default calculation in Article 51(4)
For an existing registrant using the default method, the starting fraction is:
Prior-calendar-year qualifying taxable supplies / prior-calendar-year taxable and exempt supplies.
Apply that fraction to the eligible residual input tax. The calendar-year basis is distinct from a company’s financial reporting year. A new registrant with no registration in the previous calendar year uses estimated current-year values under paragraph 6, followed by the required annual comparison.
The fraction requires a tax classification of the supplies, not simply a total taken from the revenue account. Under paragraph 4(c), relevant supplies outside Saudi Arabia are classified by how they would be treated if made in the Kingdom. Paragraph 5 excludes capital-asset supplies and supplies taking place outside the Kingdom from an establishment of the taxpayer outside the Kingdom.
ZATCA’s section 12.3, pages 52-53, illustrates the distinction between supplies from the Saudi business and those from an overseas establishment. Example 31 expressly assumes an end to the GCC transitional arrangements for part of its scenario. Preserve that assumption when using the example; it is not evidence that the transitional arrangements have in fact ended for the transaction being reviewed. See the default-method guidance.
Dariba’s analysis. Prepare a reconciliation from accounting revenue to the statutory numerator and denominator. Separately identify asset disposals, overseas establishments and relevant incidental events. This makes the exclusions explainable and avoids treating a large cash receipt as turnover merely because it appears in the ledger. It also avoids excluding an ordinary business supply simply because it is large or unusual.
ZATCA’s example: a new registrant’s estimate changes at year-end
In Example 32, section 12.4, pages 54-55, Al Madar starts with an estimated 75% recovery percentage for shared costs. Actual full-year commercial and residential rental values produce an 80% percentage. ZATCA illustrates a final-quarter deduction based on the actual percentage, together with an additional deduction for the first three quarters. Read the official example.
The example concerns 2018 and uses SAR 10,000 VAT on SAR 200,000 of quarterly costs, reflecting the historical 5% rate. The principle illustrated is estimation followed by annual reconciliation; those VAT amounts must not be copied into a current 15% illustration without being changed and labelled.
The important management implication is that provisional restrictions are not necessarily the final irrecoverable amount for the year. Article 51(7) requires the default-method calculation to be reconciled to actual full-year supply values in the final return for that calendar year. A higher actual fraction can create an additional deduction; a lower fraction can require a reduction.
Dariba illustration: showing attribution and the annual adjustment together
Assume an otherwise eligible Saudi business has taxable commercial rental and exempt residential rental. It uses a provisional default fraction of 75%, has no non-economic use and has already removed blocked costs. Figures below are Dariba’s original illustration; the dates and amounts are not ZATCA’s Example 32.
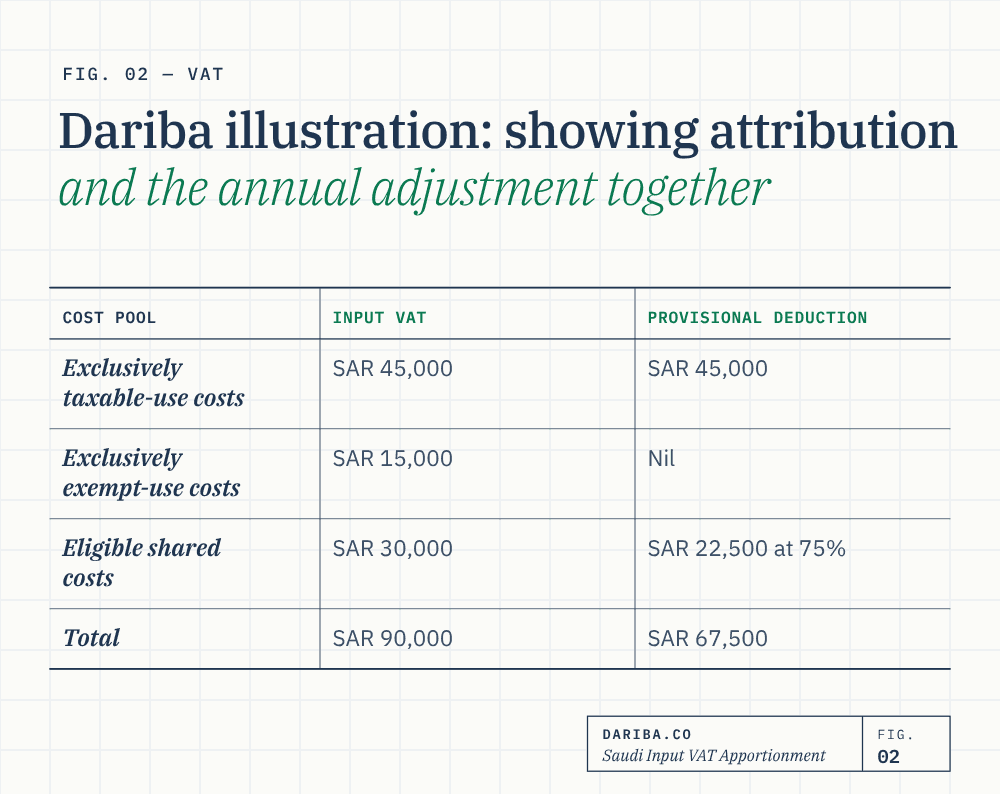
In one quarter, the following VAT is incurred:
| Cost pool | Input VAT | Provisional deduction |
|---|---|---|
| Exclusively taxable-use costs | SAR 45,000 | SAR 45,000 |
| Exclusively exempt-use costs | SAR 15,000 | Nil |
| Eligible shared costs | SAR 30,000 | SAR 22,500 at 75% |
| Total | SAR 90,000 | SAR 67,500 |
Applying 75% to all SAR 90,000 would happen to produce SAR 67,500 here, but only by coincidence: the errors on the two directly attributable pools offset. It would still be the wrong method. If either pool changes, that coincidence disappears. Retain the classification even where the total looks plausible.
Now assume shared-cost VAT is SAR 30,000 in each quarter, and actual annual supplies are SAR 4 million taxable and SAR 1 million exempt. The final fraction is 80%. Correct annual shared-cost recovery is SAR 96,000: SAR 120,000 multiplied by 80%. If the first three quarters each deducted SAR 22,500, the final-quarter shared-cost deduction is SAR 28,500, comprising SAR 24,000 for that quarter and SAR 4,500 to reconcile the earlier quarters.
The annual calculation does not change the directly taxable or directly exempt treatment merely because the business-wide ratio changed. Asset adjustments may require their own Article 52 review.
Alternative methods: a supported application, not an informal override
Article 51(8) allows an application where an alternative more accurately reflects use. Paragraph 9 provides for approval or rejection by notification and a specified use period of up to five years; a fresh application is required for renewed approval. Paragraph 10 allows ZATCA to direct another method and specify its period, notwithstanding prior approval.
Sections 13.1-13.3, pages 56-58, discuss verifiable alternatives, including transactions, inputs, employees, floor space and sectoral methods. These are possible approaches, not pre-approved safe harbours. A more favourable result is not, by itself, evidence that a method is more accurate. Read the alternative-method guidance.
For an application, we recommend comparing the default result with the proposed method, explaining the cost drivers, data source, attribution controls and why the proposed measure better represents use. Confirm the approval, effective period and conditions before relying on it in returns. See alternative apportionment methods for a focused discussion.
Paragraph 11: incidental events require their own analysis
Article 51(11) addresses specified costs connected with raising capital for an ongoing taxable activity, an outside-scope business transfer under Article 17, an incidental exempt real-estate supply meeting paragraph 11(c), and other qualifying one-off events. It makes the overall proportion of the qualifying business relevant rather than automatically denying the costs because the immediate event is outside scope or exempt.
In Example 33, section 14, page 60, Al Barakah raises new share capital to expand its fully taxable equipment business. ZATCA allows VAT on related advisory and legal costs under the provision. The use of funds and ongoing activity are material facts. The example is not a blanket allowance for investment costs or a regularly conducted exempt activity. Read Example 33 and section 14.
The guidance also explains the fraction treatment of qualifying incidental supplies. Establish that an event satisfies the provision before excluding a value or treating its costs as overheads. Keep that assessment distinct from paragraph 5’s explicit exclusions. For a business with recurring property or investment transactions, the boundary between incidental and ordinary activity deserves a fact-based review.
The year-end decision
Maintain the cost classification, fraction reconciliation and annual adjustment as separate workings. This allows the reviewer to see whether a change comes from a corrected supply classification, a different use of a cost, a year-end true-up or an approved method. Each has a different justification and should not be presented as an unexplained percentage change.
Primary source: VAT Implementing Regulations, Article 51, Arabic tenth edition, April 2025, printed pages 45-47.
Key takeaways
- Allocate restricted and non-economic use before the taxable/exempt shared-cost calculation.
- Direct taxable and exempt costs are classified separately; do not apply one percentage to the entire purchase ledger.
- The default fraction requires tax classification, statutory exclusions and the relevant calendar-year values.
- Annual reconciliation can increase or reduce recovery; provisional irrecoverable amounts are not always final.
- Alternative methods require a supported application and the relevant ZATCA approval or direction.
- Article 51(11) incidental events require their own conditions and should not be treated as ordinary exempt activity automatically.
Sources
- ZATCA - VAT Implementing Regulations, Arabic tenth edition, April 2025Article 51; controlling Arabic text.
- ZATCA - Input Tax Deduction Guideline, third version, May 2026Sections 12-14; Example 32, pages 54-55 (2018 historical figures); Example 33, page 60.
General information only. The treatment depends on the facts, applicable period and controlling Arabic legislation. Dariba analysis and practical recommendations are identified separately from official examples. Seek advice for a specific or disputed position.