In brief
Article 52 monitors initial recovery against actual use. Calculate annual adjustments from total VAT and the original recovery baseline, use the asset-specific review periods, and distinguish sale from withdrawal.
A capital-asset deduction reflects intended use when the asset is acquired. Article 52 then requires that deduction to be monitored over the relevant adjustment period. Changes can produce additional recovery as well as reductions, so the exercise is not simply a search for tax to repay.
The calculation needs four separate figures: total VAT incurred, initial recovery percentage, applicable adjustment period and actual use for the relevant twelve months. Confusing the VAT originally incurred with the smaller amount originally deducted can materially understate an adjustment.
Identify the asset and initial entitlement
ZATCA’s Capital Assets Guideline, version 2, May 2026, section 4.1, pages 16-17, describes tangible and intangible business assets held for long-term use. Inventory held for sale, manufacturing materials and consumables are not treated as capital assets merely because the invoice is large. The cost classification and intended use need to be established before opening an adjustment schedule.
Article 52(3) bases the initial deduction on intended use. Article 50 restrictions and the general entitlement conditions still apply. Capitalising a private cost or a restricted vehicle does not, by itself, make the input tax recoverable.
In Example 4, section 5.3, page 27, ZATCA considers computers acquired by a business with different divisions. Computers allocated exclusively to its fully taxable travel division give full recovery of SAR 60,000 VAT. A separate purchase for an investment division with 40% taxable use gives SAR 12,000 recovery from SAR 30,000 VAT. Read the official example.
The example supports analysing the asset’s actual intended use, rather than applying the same business-wide percentage to every purchase. It does not automatically approve divisional methods for shared assets: the allocation and any required method approval still need support.
Six or ten years, with a separate twelve-month reporting cycle
| Asset category | Ordinary Article 52(2) adjustment period |
|---|---|
| Movable tangible capital assets | Six years |
| Intangible capital assets | Six years |
| Immovable capital assets permanently attached to land or real estate | Ten years |
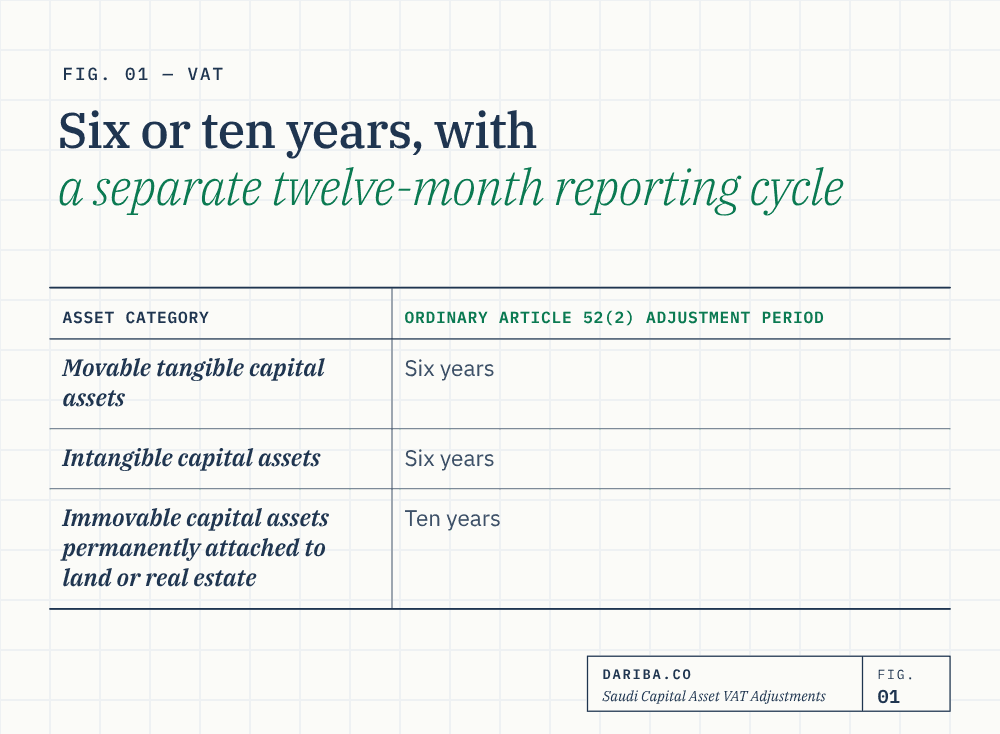
If the asset’s life under the taxpayer’s accounting practice is shorter, that life is used, with a part-year counted as a whole year. An accounting useful life should be supportable; it is not simply a choice to shorten the VAT monitoring period for convenience.
Distinguish paragraph 2’s purchase-date reference from paragraph 5’s review cycle. The first twelve-month review period starts at the beginning of the tax period in which the asset was acquired. The adjustment is reported in the return for the last tax period falling within that twelve-month period. It is not invariably a December adjustment.
Example 5, section 6.2, page 31, illustrates a facility bought on 20 July 2020 with a five-year accounting life. Its schedule starts the first review year on 1 July 2020 and ends it on 30 June 2021. The example therefore shows both the shorter-life rule and the period-start convention. Read Example 5.
Calculate the annual change using both sides of the comparison
Sections 6.3.1-6.3.2, pages 34-35, set out the calculation:
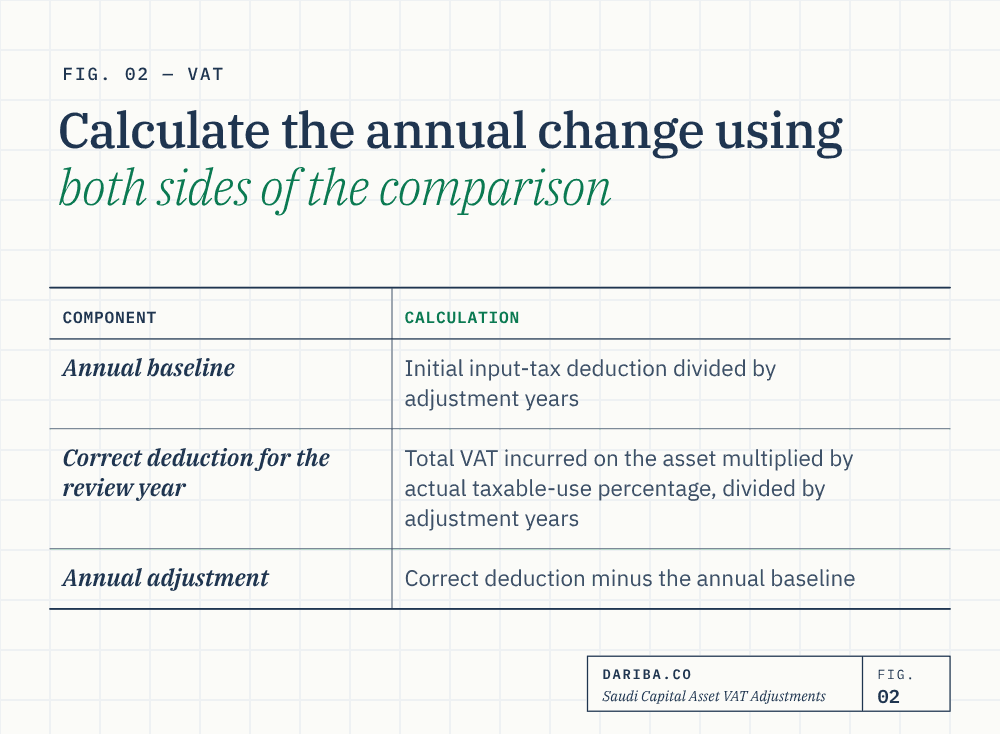
| Component | Calculation |
|---|---|
| Annual baseline | Initial input-tax deduction divided by adjustment years |
| Correct deduction for the review year | Total VAT incurred on the asset multiplied by actual taxable-use percentage, divided by adjustment years |
| Annual adjustment | Correct deduction minus the annual baseline |
Equivalently, where the initial deduction equals total VAT multiplied by the initial recovery percentage, the adjustment is total VAT / adjustment years x (actual taxable-use percentage minus initial recovery percentage). A positive result adds to deductible tax; a negative result reduces it. Use percentages as decimals in the calculation. See the official formula table.
The annual baseline is not then multiplied by the percentage-point change as a second reduction. That shortcut can produce an incorrect answer where initial recovery was below 100%.
ZATCA’s example: initial recovery of 45%
In Example 7, section 6.3.2, pages 36-37, ZATCA uses a building bought in April 2019 with SAR 350,000 VAT, 45% initial recovery and a ten-year adjustment period. The initial deduction is SAR 157,500, giving an annual baseline of SAR 15,750. Read the complete example.
| Review-year taxable use | Correct annual deduction | Adjustment against SAR 15,750 baseline |
|---|---|---|
| 45% | SAR 15,750 | Nil |
| 40% | SAR 14,000 | SAR 1,750 reduction |
| 58% | SAR 20,300 | SAR 4,550 additional deduction |
These are the official example’s historical figures, independently recalculated. They illustrate the adjustment mechanism, not the VAT treatment of acquiring an office building today. Apply the rules for the transaction’s actual period when assessing initial entitlement.
Dariba’s analysis. Compare each review year’s actual use with the initial recovery percentage, rather than simply with the previous year’s percentage. In the example, the 58% year is compared with 45%, not 40%. A schedule that carries forward last year’s adjustment as the new baseline can compound the error.
Dariba illustration: a partly deductible shared system
Assume a qualifying movable capital asset is acquired in January 2026 with SAR 90,000 VAT, a six-year adjustment period and 60% initial taxable use. The initial deduction is SAR 54,000 and the annual baseline is SAR 9,000. During the next review year, actual taxable use rises to 80%.
Correct annual deduction is SAR 90,000 x 80% / 6 = SAR 12,000. The additional deduction is therefore SAR 3,000. Multiplying the SAR 9,000 baseline by the 20-percentage-point difference would produce SAR 1,800, which is wrong. If actual use instead fell to 40%, the calculation would produce a SAR 3,000 reduction. These are Dariba’s own assumed facts, not another ZATCA example.
If actual use remains equal to initial use, Article 52(6) requires no adjustment for that review year. ZATCA’s Example 8, section 6.4, page 38, illustrates unchanged fully taxable computer use. Keep evidence of the comparison and continue monitoring; no adjustment is different from no review.
Improvements have their own monitoring period
Article 52(3) treats qualifying construction, enhancement or improvement expenditure on an existing asset as acquisition or additional acquisition expenditure. The adjustment period for the additional expenditure starts on completion of the works. This does not automatically restart the original asset’s entire period.
Example 6, section 6.2, page 32, shows equipment bought in March 2020 and upgraded in works completed on 23 May 2021. ZATCA applies a separate six-year period to the upgrade. The purchase figures include the historical VAT rate; the point is the separate expenditure and completion date. We recommend recording the original asset and later capital projects separately so their VAT, initial-use percentages and review dates can be traced.
Sale within the period: adjustment and output VAT are distinct
Article 52(7) addresses permanent adjustment on sale or disposal. ZATCA’s section 6.5 assumes a taxable sale and treats remaining use as 100% taxable. The permanent adjustment is based on the change from initial recovery for the remaining period; the sale also requires its own output-VAT analysis.
Example 9, section 6.5, pages 39-40, involves a server acquired with SAR 36,000 VAT and 50% initial recovery. It is sold in May 2024 within its six-year period. The guidance counts three remaining years, including the sale year, and calculates an additional SAR 9,000: SAR 36,000 x (100% - 50%) x 3 / 6. It does not also make a separate annual adjustment for the pre-sale part of that year. Read the disposal example.
If initial recovery was already 100%, the same taxable-sale formula can give a zero additional adjustment. “A sale must be reviewed” does not mean every disposal necessarily creates a repayment. Do not apply the taxable-sale assumption to an exempt transaction without examining its own treatment.
Permanent withdrawal and exceptional events
Article 52(8) provides a nominal-supply route for the permanent cessation it describes. ZATCA’s sections 6.6-6.6.1, pages 41-42, discuss permanent removal from economic activity. The stated nominal-supply value uses purchase value, initial recovery percentage and remaining useful life divided by the adjustment period; the applicable output VAT is then assessed on that value. That calculation is distinct from the annual adjustment to deductible tax.
The remaining-life convention also needs care: paragraph 8 refers to part or full years of use, while the taxable-sale example expressly includes the disposal year in the remaining period. Do not reuse one schedule mechanically for both events.
The guidance excludes a nominal supply where no initial input tax was deducted and where an idle asset remains available for economic activity. It also addresses theft and required destruction. Article 52(7) contains the exceptions to remaining-period adjustment for destruction, theft or premature end of useful life. Retain evidence of the event; a routine sale is not converted into an exception by calling it a write-off.
A permanent switch to wholly exempt use within a continuing business requires particular care in selecting the route under paragraphs 1 and 8. The Arabic provision and the guidance’s economic-activity explanation should be read together on the actual facts. Do not assume either annual-only adjustment or a nominal supply solely from a general ledger label. Establish the nature and permanence of the change and seek clarification where the treatment remains unresolved.
The practical register should retain total VAT, original deduction, initial-use percentage, acquisition period, useful-life basis, each review period, actual use, improvements and disposal or withdrawal events. That provides a defensible calculation and identifies additional recovery as well as exposure.
Primary source: VAT Implementing Regulations, Article 52, Arabic tenth edition, April 2025, printed pages 47-48.
Key takeaways
- The ordinary periods are six years for movable tangible and intangible assets, and ten years for qualifying immovable assets, subject to the shorter-life rule.
- The first twelve-month review cycle starts at the beginning of the acquisition tax period; adjustment is not invariably made in December.
- Correct annual deduction is based on total VAT and actual use, less the annual share of the original deduction.
- Compare actual use with the original recovery percentage, not simply the previous year.
- Later improvements have a separate adjustment period; they do not automatically restart the original asset period.
- A taxable sale, permanent withdrawal, theft and destruction require different treatment and evidence.
Sources
- ZATCA - VAT Implementing Regulations, Arabic tenth edition, April 2025Article 52; controlling Arabic text.
- ZATCA - Capital Assets Guideline, version 2, May 2026Capital Assets Guideline sections 5.3 and 6; Examples 4-9, pages 27-40; nominal supplies, pages 41-42.
General information only. The treatment depends on the facts, applicable period and controlling Arabic legislation. Dariba analysis and practical recommendations are identified separately from official examples. Seek advice for a specific or disputed position.