In brief
ZATCA’s Arabic classification guide sets different e-invoicing schedules for integration, sharing and other failures. Warning, recurrence, incident evidence and the current Article 45 waiver exclusion must be examined separately.
An e-invoicing penalty review should start with the actual violation, applicable integration date, prior notice and repetition history. ZATCA’s Simplified Guideline for the Classification of General VAT Violations, second edition, May 2024, sets out distinct e-invoicing categories and escalation schedules. A single generic fine range does not explain those rules.
The same review must separate remediation from waiver eligibility. ZATCA’s current 29 June 2026 waiver announcement expressly excludes fines imposed under VAT Law Article 45. A December 2026 initiative deadline should not be presented as a blanket opportunity to clear e-invoicing fines without payment.
Identify the obligation and its effective date
The E-Invoicing Regulation and the implementation controls establish the invoice, solution, record and integration obligations. Some requirements applied from the generation phase; others apply from the particular taxpayer’s integration date.
The classification guide’s e-invoicing table, items 8–18, identifies the relevant conduct and timing. Check the actual notification, invoice type, affected solution and breached requirement. A taxpayer who has not yet reached its Phase Two date is not in the same position as one continuing with an unintegrated solution after that date.
For standard Tax Invoices, implementation controls Clause Two(3)(a) require clearance before sharing with the customer. Simplified Tax Invoices follow the reporting route within no more than 24 hours of generation under Clause Two(3)(b). Establish the document category and actual response rather than assume every invoice follows one process.
Apply the current category-specific escalation schedule
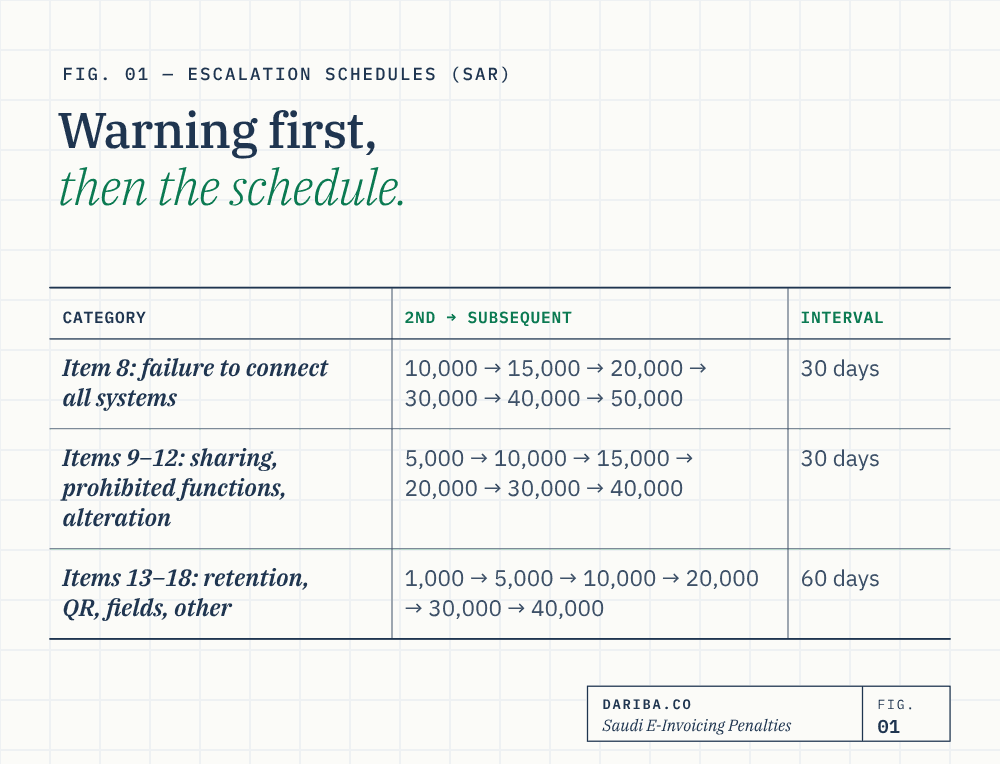
The guide starts the listed general violations with a warning and explanation, together with the appropriate correction period. The e-invoicing rows specify the following schedules. Amounts below are Saudi riyals; the sequence starts at the second occurrence, following the initial warning.
| Guide category | Second, third, fourth, fifth, sixth, then subsequent occurrence | Specified interval |
|---|---|---|
| Item 8: failure to connect all relevant systems from the integration date, subject to its stated Authority-system-fault qualification | 10,000 → 15,000 → 20,000 → 30,000 → 40,000 → 50,000 | 30 days |
| Items 9–12: specified sharing or issuance failures, prohibited functions, and deletion or alteration after issue | 5,000 → 10,000 → 15,000 → 20,000 → 30,000 → 40,000 | 30 days |
| Items 13–18: specified retention, incident-notification, QR, data-field, customer-sharing and other requirement failures | 1,000 → 5,000 → 10,000 → 20,000 → 30,000 → 40,000 | 60 days |
Each row retains its own wording and effective date. Item 9, for example, includes the required sharing format and timing, incident-notification facts and the stated Authority-system-fault qualification. It should not be replaced by an unconditional charge for every rejected invoice.
These are category and repetition rules, not compound interest. Do not multiply a maximum amount by the number of months or every invoice without establishing the actual provision, occurrence and assessment basis. Item 18 expressly addresses separate treatment of each breached requirement; that does not create an unrestricted per-invoice formula for every category.
Preserve warning, recurrence and elapsed-time evidence
The guide’s closing repetition rule uses a twelve-month boundary for the same violation and explains when a later occurrence is treated as new and begins with a warning. It refers to detection and prior penalty-decision timing; retain both dates, the conduct identified and the relevant notification.
A new-violation treatment does not cancel an earlier penalty already imposed. Nor is the initial warning a permission to delay compliance until the next inspection. It provides a defined opportunity to correct the identified failure within the applicable process.
Prepare a chronology for each category: first discovery, warning, required correction, remediation, later discovery and penalty decision. That evidence is more useful than a general assertion that the taxpayer has never previously paid a fine.
Learn from the actual ZATCA restaurant examples
Under Illustrative examples of e-invoicing violations, first example, failure to connect all systems, Mohammed owns a restaurant with three cash registers. Two have been connected and the third has not. The official example begins with a warning, requires the relevant systems to be connected and describes a SAR 10,000 fine if the violation recurs after 30 days.
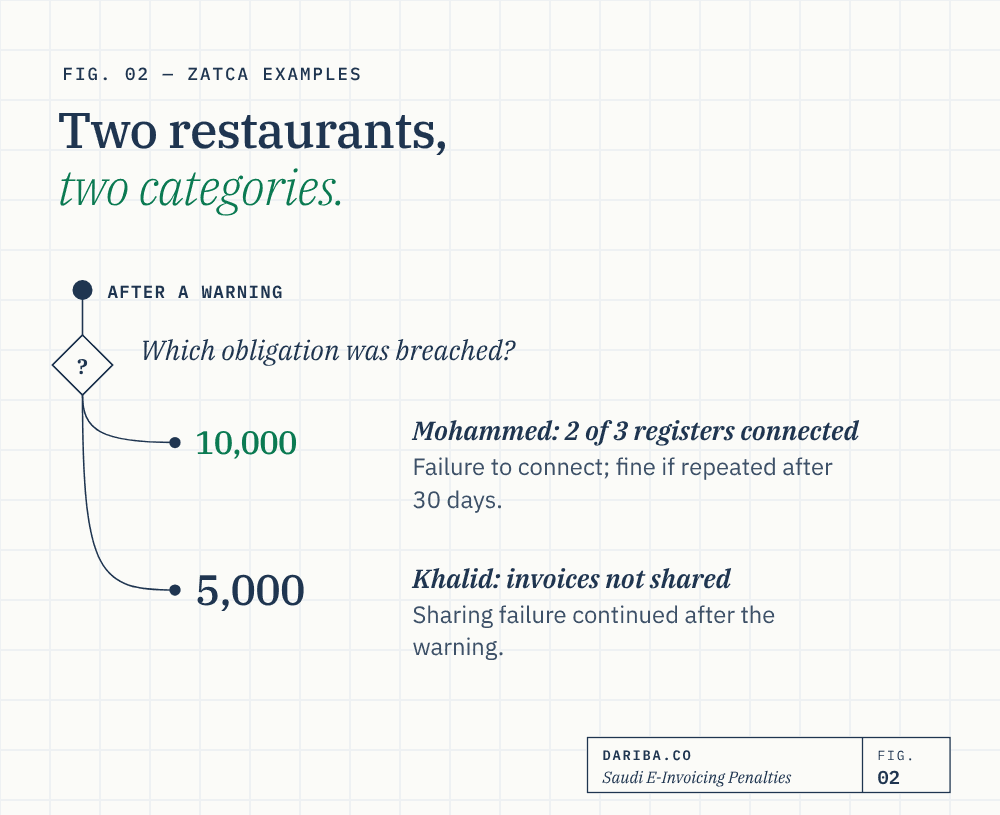
The practical lesson is to reconcile all systems actually used to issue invoices with the integration inventory. One successful connection does not prove that the remaining issuance channels comply. This example should not be turned into a universal certificate-per-screen rule; the technical architecture determines where invoicing and signing occur.
In the second example, failure to share invoices and notes, Khalid’s restaurant issues simplified invoices and continues the identified sharing failure after the earlier warning. The guide applies SAR 5,000 on the stated subsequent occurrence. That amount belongs to the sharing category and its facts, rather than the different integration schedule.
Distinguish outages, notification and ordinary vendor failures
Item 8 recognises evidence that non-connection results from a technical fault in the Authority’s systems. Other rows contain their own incident and notification wording. A vendor delay or an internal network failure should not automatically be described as a ZATCA-system outage.
Implementation controls Clause Seven(5) require notification through the Authority’s specified means of incidents, technical errors or emergencies hindering generation or integration, notification of recovery, and prompt resumption of the required electronic generation and sharing. The relevant procedure depends on the actual incident and Authority instructions.
Retain incident times, affected systems, error responses, support records, the official notification and recovery reconciliation. A support ticket sent only to the software supplier is not evidence that the Authority received the required notification. Correct the backlog through the applicable procedure while preserving issued records.
Assess the current waiver and underlying VAT separately
ZATCA’s 29 June 2026 extension announcement expressly excludes Article 45 fines. Earlier announcements referring to field or e-invoicing penalty relief concern earlier terms and should not override the current exclusion. The current penalty-waiver guide explains Resolution 1117, the return cutoff and permitted payment routes.
An e-invoicing defect, an incorrect VAT return and a late tax payment can raise different issues. Analyse each legal basis. VAT Law Article 46 also preserves collection of the underlying tax despite a penalty. Correcting the software does not itself settle unpaid tax, and paying tax does not itself cure every invoicing failure.
Likewise, do not declare every buyer deduction invalid solely because the supplier has received a system penalty. Establish the actual invoice, applicable requirements and input-tax conditions. The invoice-requirements guide addresses the document evidence.
Remediate the cause and verify continuing compliance
Match the notified violation to a corrective action: connect the missing issuing system, restore timely reporting, remove a prohibited function, correct document fields or recover the required archive. Preserve the generated invoice and use the lawful credit/debit-note process where applicable, rather than deleting the evidence.
Test the corrected scenario and monitor subsequent transactions. Maintain a person responsible for incident notification, response deadlines and account reconciliation. Where a penalty decision is disputed, establish the applicable objection route and deadline from the actual decision; remediation should not be assumed to preserve an appeal automatically.
The solution-requirements guide and Phase Two guide connect the legal duties to operating controls. A useful review ends with the particular category, supported amount, correction evidence and any unresolved classification, rather than an unsupported total based on a generic maximum.
Key takeaways
- The current published Arabic guide gives category-specific schedules for items 8–18.
- The first occurrence begins with a warning under the listed classification framework.
- Integration, sharing and other failures have different repeat amounts and intervals.
- Official restaurant examples illustrate missing-system and invoice-sharing failures.
- An outage requires its actual cause, applicable qualification and notification evidence.
- The current waiver announcement excludes Article 45 fines; principal tax remains separate.
Sources
- ZATCA Simplified Guideline for Classification of General VAT Violations, second edition, May 2024E-invoicing table items 8–18, recurrence rule and restaurant examples: category-specific warning, intervals, escalation and system-fault qualifications.
- ZATCA e-invoicing implementation controls, current Arabic publicationClauses Two, Three, Five and Seven and Annex One: document routes, security, retention, integration and incidents; controlling Arabic text.
- ZATCA English publication of e-invoicing implementation controlsReading aid for the controlling Arabic controls and annexes; standard clearance and simplified reporting distinguished.
- Saudi VAT Law, controlling Arabic textArticles 45–46: general VAT contraventions and preservation of principal-tax collection; current initiative Article 45 exclusion read with June announcement.
- ZATCA penalty-waiver extension announcement, 29 June 2026Current extension ends 31 December 2026 and expressly excludes VAT Law Article 45 fines; earlier e-invoicing relief is not assumed to continue.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.