In brief
Saudi VAT uses distinct registration, classification, liability, deduction, adjustment and procedural rules. This overview links the detailed provision analyses and identifies the factual and source limits of a general guide.
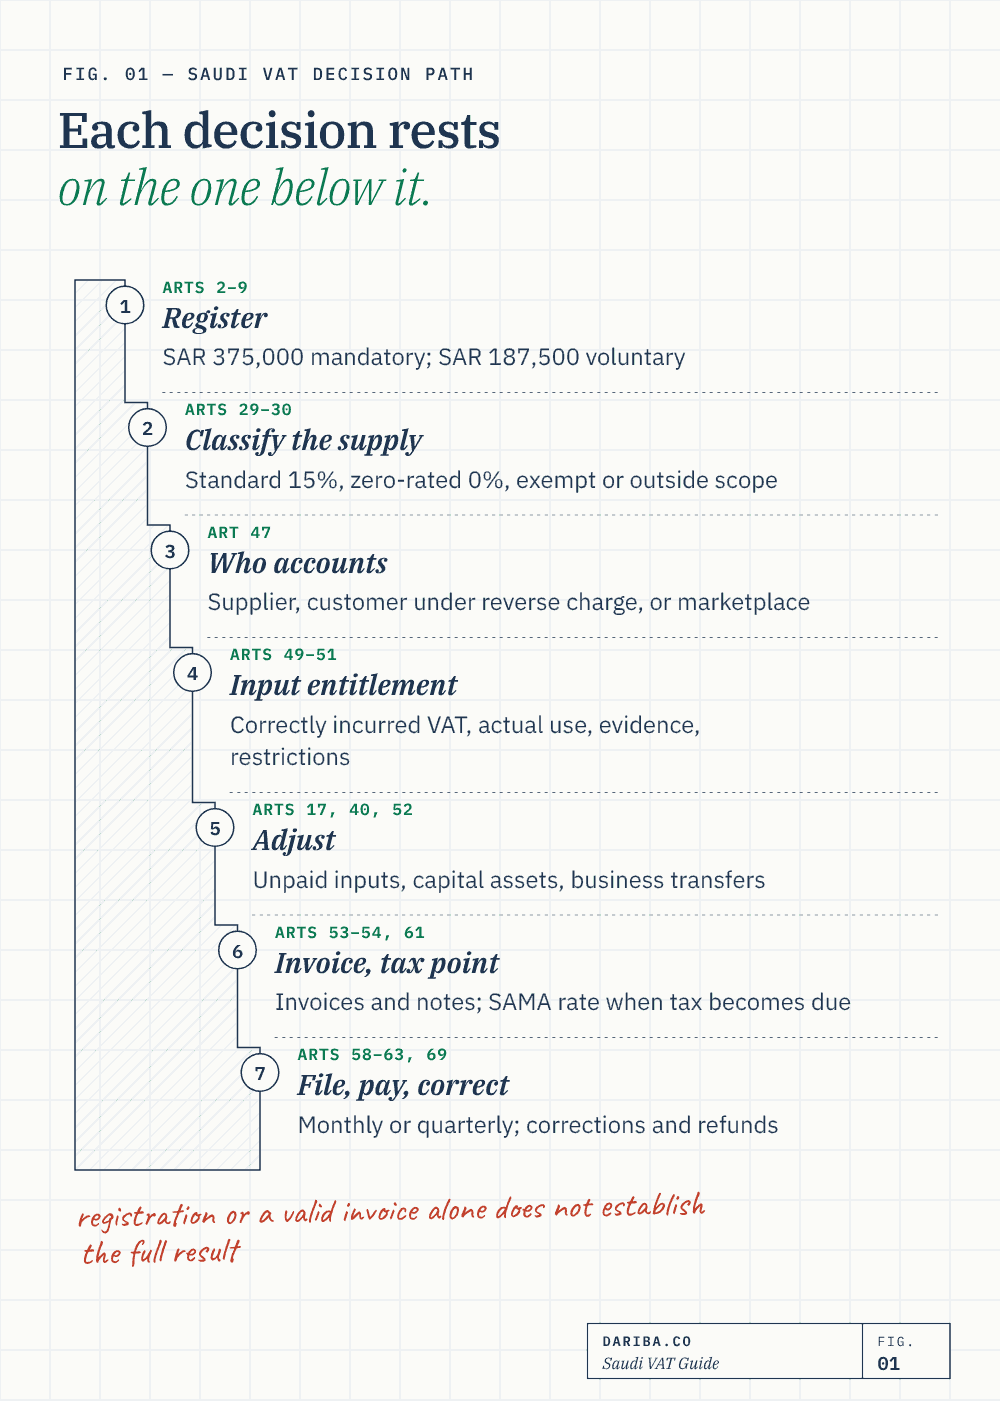
Saudi VAT compliance starts with identifying the actual supply, place, liable person and applicable rate, then connecting output tax to properly supported input deductions, adjustments and returns. The standard rate is 15%. Zero-rated, exempt and outside-scope transactions have different conditions; registration or a valid invoice alone does not establish the full result.
This overview connects the principal decisions to Dariba’s detailed provision guides. It should be used as a navigation framework alongside the actual transaction facts and controlling Arabic legislation, rather than as a claim that every special regime or arrangement has been resolved in one page.
Use the current legal framework and the correct source hierarchy
The GCC VAT Agreement, Saudi VAT Law and Implementing Regulations form the primary framework. The VAT Law was issued under Royal Decree M/113 dated 2 Dhu al-Qadah 1438H, corresponding to 25 July 2017. The current official Arabic regulation file reviewed for this release is its tenth edition, April 2025; official guidelines retrieved again provide the explanatory examples.
ZATCA guidance explains indicative treatment but does not amend the statute by itself. An English example, old project document, technical file timestamp or secondary article should not silently displace current Arabic text. Where the sources contain a real discrepancy, identify it and apply the controlling provision rather than inventing a reconciliation or assurance.
Official examples below retain their dates and context. Historical figures are not automatically recalculated at today’s rate; original Dariba assumptions are labelled separately.
Establish economic activity and registration
Articles 2–9 address activity and registration. For resident mandatory registration, actual and expected taxable supplies use distinct tests around the SAR 375,000 threshold and different application/effective-date provisions. The past-supply application is tied to the month-end review and thirty-day rule; the future-supply rule should not be replaced by the same retrospective effective-date formula.
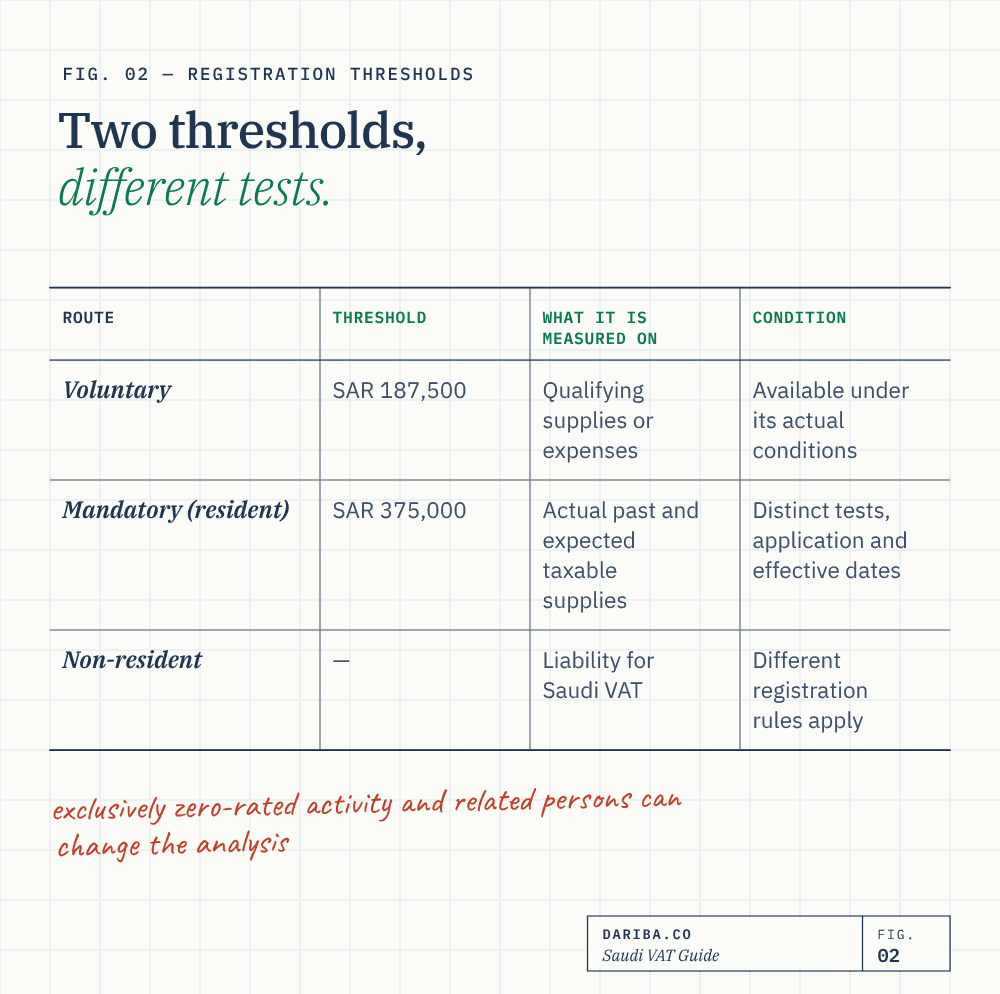
Voluntary registration can be available at SAR 187,500
The registration guide and freelancer guide explain the tests, official examples and timing. ZATCA’s Tax Groups guideline section 3, Example 1, p. 10, illustrates Golden Falcon’s substantial pre-revenue expenses supporting voluntary registration on its facts. It does not establish automatic cash refunds on every start-up cost.
Classify the supply, rate and place
Ordinary standard-rated supplies bear 15%; qualifying zero-rated taxable supplies use 0%; exempt supplies follow Articles 29–30. The conditions for exports, transport, medical goods, metals and other specific zero-rate routes must actually be met. Foreign customers and no-VAT invoice labels do not prove qualification.
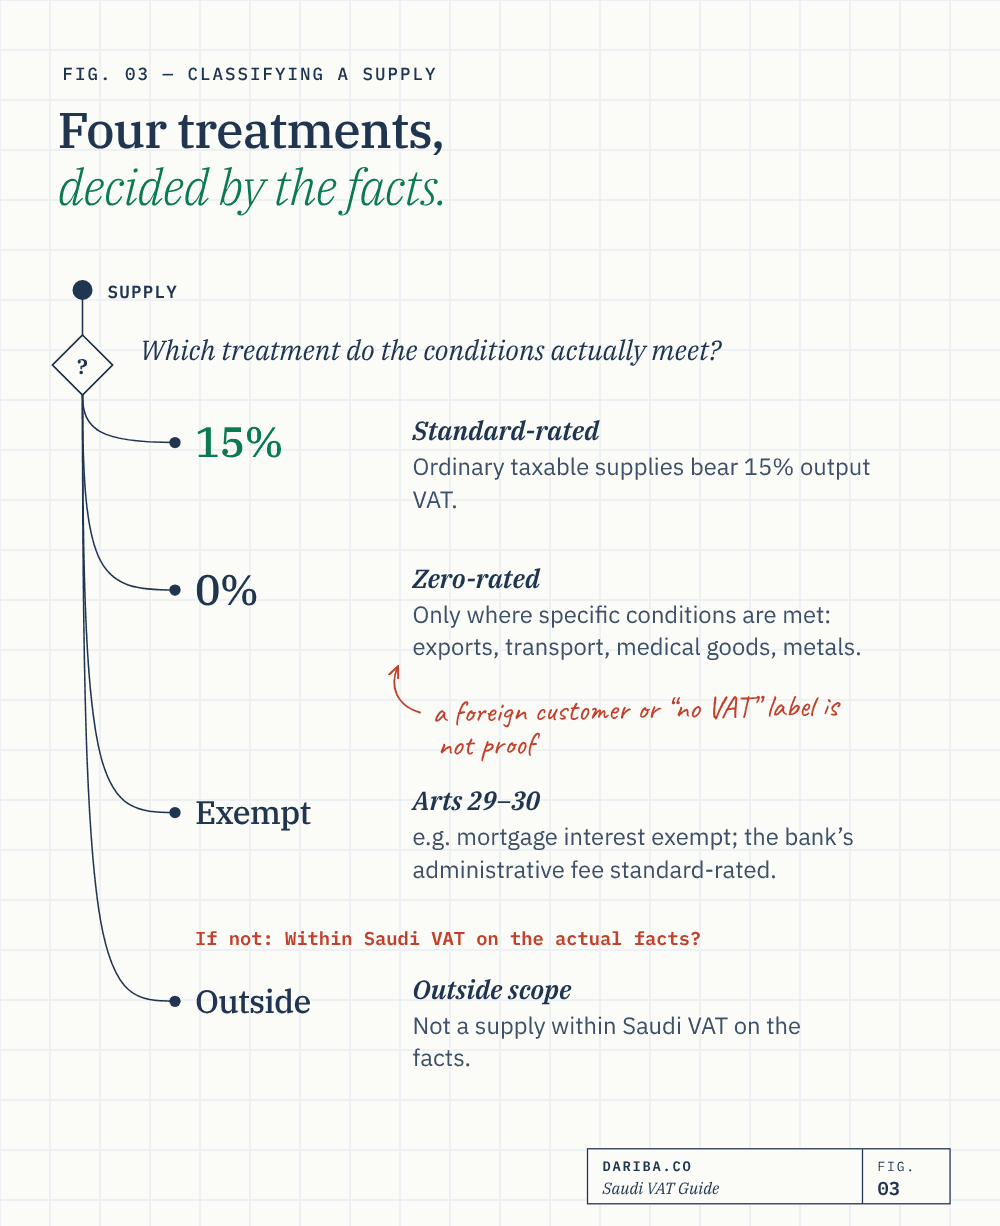
The Financial Services guideline section 4.1, Example 5, p. 16, separates exempt mortgage interest from Al Madinah Bank’s standard-rated administrative fee. The Real Estate Sector guideline section 6.1, Examples 6–8, pp. 15–16, distinguishes genuine student residences, a four-month serviced traveller stay and optional parking. Institution, property and duration labels alone do not decide every supply.
Use the exempt-supplies guide, zero-rate comparison, residential analysis and digital-services guide. Property ownership transfers and leasing differ, while RETT remains a separate regime.
Determine whether the supplier, customer or marketplace accounts
Cross-border goods importation, a domestic supply by a non-resident and a qualifying imported service are different transactions. Article 47(1) and the Agreement’s received-supply rules govern the relevant reverse charge; they do not impose 15% on every foreign expense regardless of place or exemption.
Articles 47(2)–(4) can treat a marketplace as purchasing and reselling, with distinct supplier-status and exception conditions. A non-resident platform can still leave a Saudi registered taxable customer responsible for reverse charge. A tax-looking foreign invoice does not automatically supply a Saudi input credit.
The reverse-charge overview, imported-services analysis and marketplace guide explain the actual legs. An ordinary marketplace margin is not a universal VAT-on-margin scheme, and a free nominal supply under Article 15 is a different concept from a deemed marketplace supplier.
The consideration guide, related-party valuation analysis, vouchers guide and business-promotions analysis address the pricing and payment rules that apply before calculating the final VAT amount.
Establish the input entitlement before claiming it
Articles 49–51 require correctly incurred VAT, the actual recipient/use, adequate evidence and applicable restrictions. Direct taxable-use inputs differ from direct ordinary exempt-use and genuinely shared inputs. Permitted simplified/alternative/import/reverse-charge evidence requires its own conditions; a missing field should not be replaced by a universal no-remedy conclusion or an automatic deduction.
Dariba illustration — original assumptions: an otherwise wholly taxable business has SAR 15,000 VAT on qualifying taxable-use expenditure and SAR 3,000 actually blocked VAT. Deduction is SAR 15,000, not SAR 18,000, assuming all other requirements. A qualifying zero-rated output would not cure the blocked SAR 3,000.
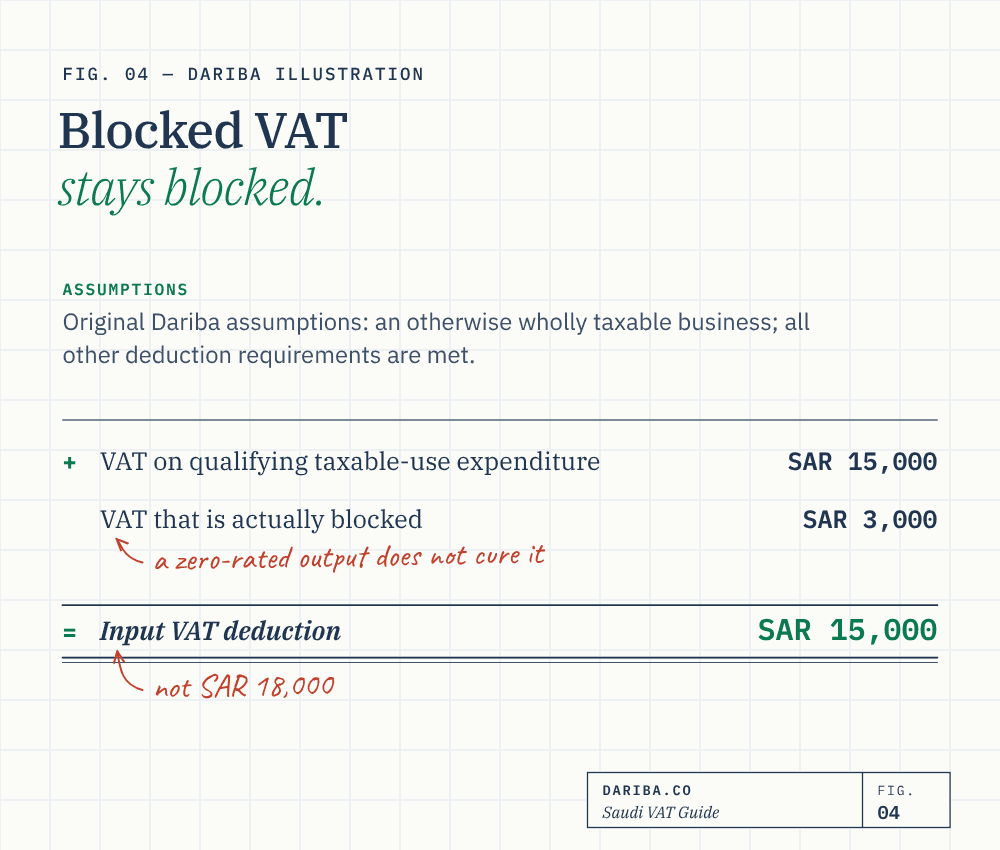
See input entitlement, apportionment and alternative methods. An Article 51(9) approval is for an actual period of no more than five years, renewable through a new application; it is not automatically a full five-year term. Deduction, a carried credit and an approved refund are separate outcomes.
Review unpaid inputs, capital use and business changes
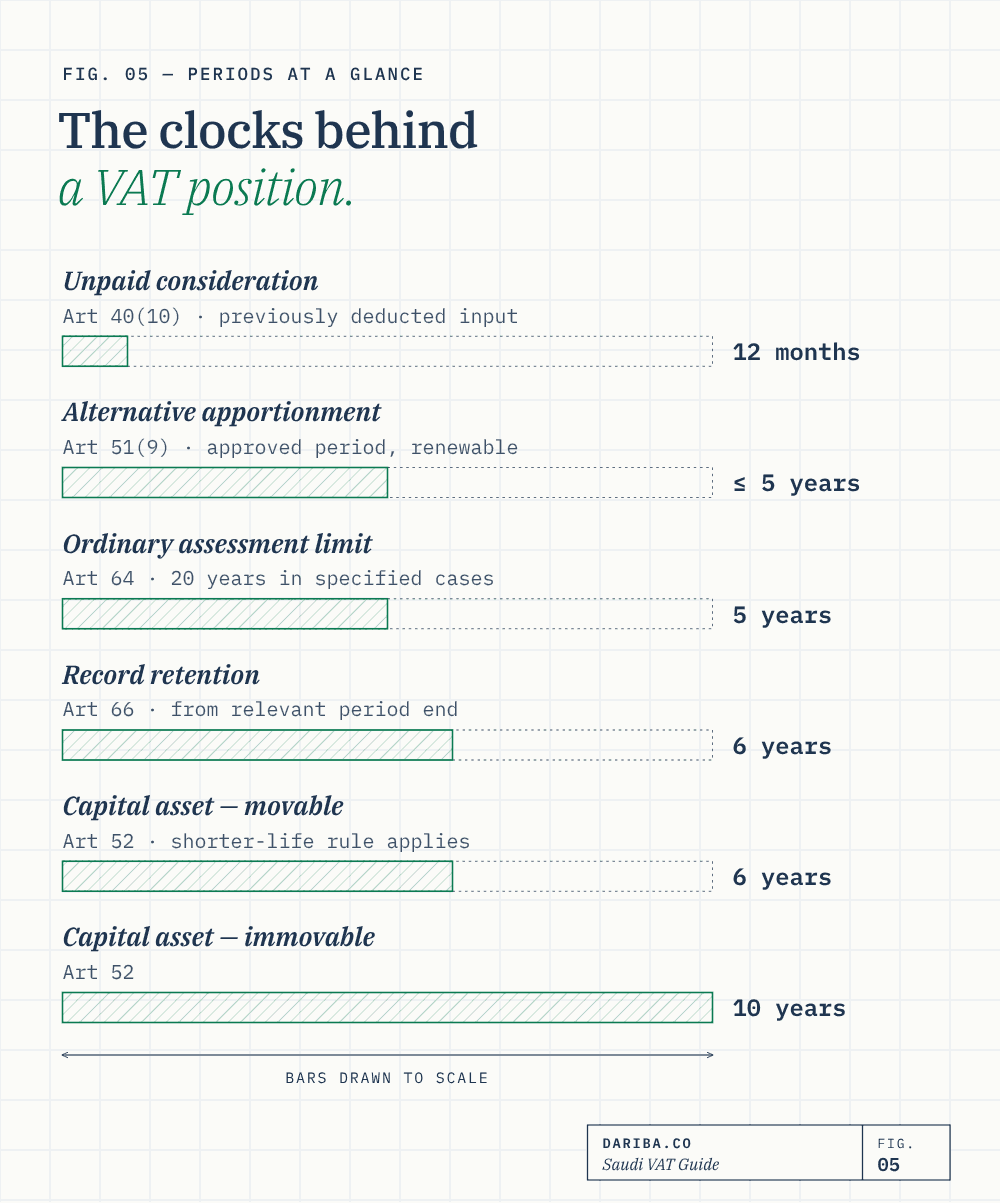
Article 40(10) addresses previously deducted input on unpaid consideration after its prescribed twelve-month clock. The relevant financed-goods exception has conditions, including a qualifying licensed provider, periodic payments, continuing contract, no relevant judicial dispute and the supplier’s written declaration confirmation. It is not an unconditional exception for every loan or finance company.
Article 52 ordinarily uses six years for movable capital assets and ten years for immovable assets, subject to its shorter-accounting-life rule. Actual review cycles, later improvements, use changes, disposals, cessation and qualifying transfers require their specific calculation. Do not use a universal five-year movable-asset period or automatically stack duplicate adjustments.
Article 17 qualifying business transfers require operational continuity, written agreement and actual notification conditions. Failure requires classification of the transferred supplies, not automatic 15% on every property component. Capital adjustments, deemed supplies and business transfers cover these events.
Apply group treatment only to the approved eligible perimeter
Articles 10–12 require continuing group eligibility, the actual ownership/control test, exclusions and Authority process. Article 18(2) disregards supplies between actual members, but grouping does not guarantee improved input recovery or remove external taxable supplies.
The group-registration guide and financial-group analysis explain member liability, change notices and combined cost attribution. An application is not the same as effective group approval, and a historical transition window is not a new grace period for every structure.
Keep VAT grouping separate from Zakat, income tax, withholding and transfer pricing. Another regime can use a different taxpayer perimeter and treatment.
Invoice and record the actual tax point
Tax points govern the reportable period. Ordinary, advance and continuous supplies have different relevant rules; payment and invoice dates can matter. Article 61 conversion uses the applicable SAMA rate when tax becomes due, not an arbitrary accounting average in every case.
Articles 53–54 govern invoices and credit/debit notes. E-invoicing requirements depend on the actual resident population, phase/integration scope and invoice category. Clearance and simplified-invoice reporting are different workflows; do not describe every electronic invoice as real-time pre-issue clearance.
Use the invoice requirements, continuous-supplies guide and clearance/reporting analysis. Article 66 ordinarily requires six years of records from the relevant period end, with distinct capital/property requirements and electronic-storage conditions.
File, pay, correct and request refunds under their own rules
Article 58 uses preceding-twelve-month taxable supplies to determine monthly versus quarterly periods, with applications and notifications for changes. Articles 59 and 62 generally require payment/filing by the following month’s last day. Article 74 does not automatically move VAT filing/payment deadlines falling on a weekend to the next working day.
Article 63 distinguishes correction routes, including its strict less-than-SAR 15,000 discovery-period exception. Article 49’s later first deduction, an Article 40 event and a refund request do not share one universal correction clock. Article 69 refund conditions, discretionary rejection, approval-based payment and offsets also need separate analysis.
See tax periods, filing, corrections and refunds. A valid credit or completed filing does not guarantee immediate payment or cancellation of every penalty.
Preserve the basis for assessments and uncertain positions
Article 64’s ordinary five-year calendar-year limit, specified twenty-year cases and paragraph (10) agreement route require their actual conditions. Record retention and refund examination are separate questions. Not every error proves intentional breach, and not every period since 2018 remains within the ordinary window.
Dariba recommends retaining the legal provision, actual facts, official source/version, calculation, assumptions and evidence for each material position. Where the source or arrangement leaves an issue unresolved, define that boundary and obtain appropriate clarification before promising a result. The assessment and audit guides explain the related procedures.
Key takeaways
- Registration past/future tests, voluntary expenses and non-resident liability have different conditions and dates.
- Zero-rated, exempt and outside-scope supplies require actual classification and conditional recovery analysis.
- Imported supplies, marketplace resale and ordinary free nominal supplies are different legal mechanisms.
- Correctly incurred VAT, actual use, evidence and restrictions determine deduction; refunds remain separate.
- Capital periods are ordinarily six years movable and ten immovable, subject to the shorter-life rule.
- Tax points, invoices, electronic workflows, filing/payment dates, corrections, refunds and assessments each retain their own rules.
Sources
- Controlling Arabic VAT Implementing RegulationsTenth edition April2025. Articles 10-12,18(2),29,40(7),(10)-(12),47,49-52; Article 51(9)maximumfiveyears renewable;52(2)ordinarysixmovable/tenimmovable with shorter-life rule.
- Saudi VAT Law, official Arabic textCurrent official source retrieved again for release. Controlling Arabic primary text and exact sections/examples cited in the article and evidence report.
- GCC Unified VAT Agreement, official Arabic textCurrent official source retrieved again for release. Controlling Arabic primary text and exact sections/examples cited in the article and evidence report.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.