In brief
Resolve Saudi WHT payer, source, rates, software, gross-up, monthly and annual reporting, certificates and corrections using current official guidance.
Saudi withholding decisions start with the payment’s actual facts. A rate table is useful after identifying the relevant payer, non-resident recipient, Saudi source and income category. These questions connect the current Arabic implementing regulations with ZATCA’s official examples, while identifying the matters that require contract-specific or treaty-specific confirmation.
Does a Zakat payer or a GCC recipient change the scope?
Income Tax Law Article 68 and Regulations Article 63 concern the relevant Saudi resident payer or Saudi permanent establishment paying in-scope Saudi-source income to a non-resident. ZATCA’s General Withholding Tax Guideline, second version May 2026, sections 1–2, pp. 8–17, explains that Zakat status does not by itself remove withholding duties. Government entities and business-connected natural-person payments also require the stated scope considered.
Nationality, GCC incorporation, Saudi residence and a payment’s actual connection with the recipient’s Saudi establishment are different facts. A GCC address is not a Saudi residence determination. A Saudi shareholder does not automatically make the foreign recipient resident.
Official Example 2, pp. 15–16, concerns an actual payment connected with the recipient’s Saudi permanent-establishment activity and the income-tax route. The existence of an unrelated Saudi office is not enough to apply that treatment to every payment. See the main WHT guide.
Which domestic rate should finance apply?
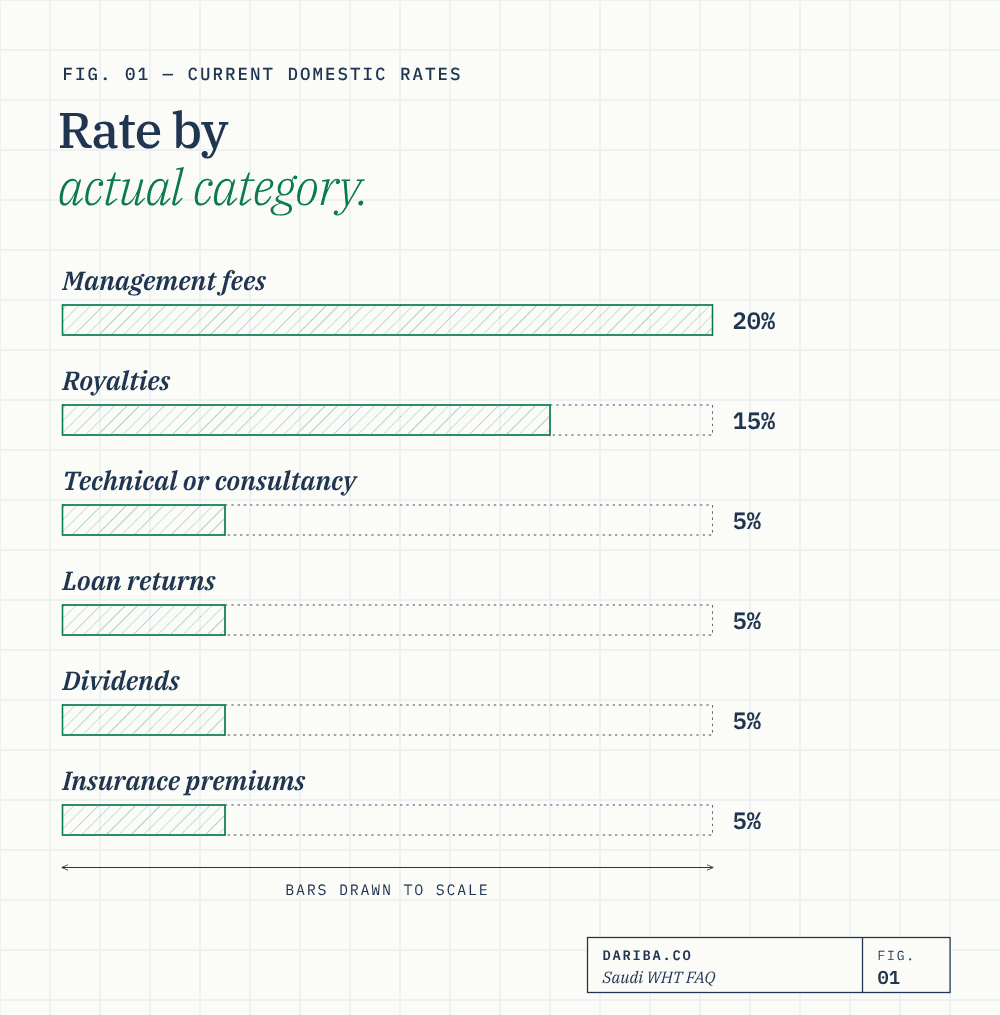
Current Arabic Article 63(1), p. 34, and guideline section 3, p. 28, provide the categories. These common categories are not interchangeable:
| Actual in-scope category | Current domestic rate |
|---|---|
| Management fees | 20% |
| Royalties | 15% |
| Technical or consultancy services | 5% |
| Loan returns | 5% |
| Dividends | 5% |
| Insurance or reinsurance premiums | 5% |
The table does not establish source, a classification or treaty eligibility. Rent, freight, telecom and residual payments have their own definitions and exclusions; other payments is not a universal 15% rule for anything sent abroad.
Related-party status does not automatically move actual technical fees from the current 5% category to 15%. Conversely, using technical expertise while managing a business does not automatically turn actual management consideration into a 5% service.
Does performance overseas remove Saudi source?
Not necessarily. Regulations Article 5(3), p. 5, specifically addresses technical/consultancy services provided to a Saudi resident or associated with Saudi activity. Relevant related/head-office service rules also require their actual facts considered. Performance abroad is not by itself an exemption for those cases.
It is equally unsafe to say every remotely delivered foreign service is Saudi-source on identical grounds. Identify the applicable source provision and actual consideration. Guideline Example 6, p. 24, describes pure overseas advertising placement on its stated facts, distinguished from design, studies or other work.
Dariba recommends recording the source rule used. A supplier-location field in accounting cannot replace that explanation. See the technical-services guide for the actual definition and foreign-performance rule.
Are all software licences or SaaS subscriptions royalties?
No universal result is established by the word software. Guideline sections 5.1–5.2, pp. 33–36, distinguish actual rights/know-how from services, and give specific software/database and non-royalty examples. p. 23 separately addresses technology used in delivering a service and independent software-related support.
Read the actual exploitation, modification, reproduction or distribution rights and independent service obligations. Do not broaden a personal/recreational-use example into a corporate exemption, or use 15% as a legally established SaaS default simply because it is called conservative.
A non-royalty payment can still be another in-scope category. The software guide explains why licence rights, automated access and independent implementation/support require their own evidence rather than one universal software rate.
How do mixed contracts and net fees affect the calculation?
Regulations Article 63(8), p. 35, applies withholding to the full relevant amount without deducting the recipient’s expenses. Regulations Article 5(7) and guideline Example 7, pp. 24–25, require actual goods and associated work distinguished. Genuine separation depends on substance and supported value, not merely two invoice lines.
Dariba original assumptions: SAR 100,000 is gross technical consideration within scope at 5%, without relief. Tax is SAR 5,000 and supplier receipt SAR 95,000. If the contract instead guarantees that SAR 95,000 net receipt and the payer bears the same tax, gross consideration is SAR 100,000.
This does not establish a classification or deductibility. A tax-bearing clause affects the commercial calculation; it cannot choose the statutory category or justify an artificial low-value allocation.
When are monthly and annual reports due?
Article 63(9), pp. 35–36, ordinarily requires the monthly statement within the first ten days of the month following payment. Confirm the actual official deadline. Cash, in-kind consideration and liability-discharging offsets/settlements require payment analysis under guideline p. 17; not every unpaid accrual is a completed payment.
Annual information generally uses 120 days after the financial year ends, with 60 days for partnerships. Guideline section 5, p. 30, distinguishes a month without in-scope payments from annual cases with zero tax where withholding cases existed during the year. Do not turn that into unconditional annual filing for every inactive entity.
The compliance guide addresses actual dates, statements and retention. Records ordinarily remain for at least ten years after payment, with unresolved matters preserved longer under the applicable provision.
Does a residence or withholding certificate guarantee treaty relief?
No. Guideline section 4, p. 29, recognises possible agreement relief, but the current agreement, income article, actual recipient, residence, entitlement conditions, relevant establishment connection and ZATCA procedure must support the claimed outcome.
A certificate is evidence of the fact it certifies, not proof that every treaty condition is satisfied. Do not infer one universal direct-relief, refund or certificate-timing procedure without checking the actual current requirements.
A withholding certificate and a residence certificate also serve different purposes. Evidence of Saudi withholding does not guarantee the recipient’s foreign tax credit. Keep the actual beneficiary, return, remittance and certificate reconciled.
What happens if the wrong amount was withheld?
Reassess the actual payments, scope, category, recipient and relief evidence; reconcile any tax shortfall by period and use the appropriate correction process. The penalty guide distinguishes underlying tax, delay, fraud and conditional relief.
Regulations Article 68, p. 39, and guideline p. 32 use the unpaid-tax base and completed 30-day periods for the 1% delay charge. The cited calculation does not compound earlier penalties into the tax base. An ordinary classification correction does not automatically establish fraud, and voluntary correction does not guarantee immunity.
Dariba recommends maintaining the decision trail before payment and reviewing it when contracts or recipients change. A defensible file explains the actual rule and evidence; it does not rely on the previous payment’s rate or an unsupported statement that all foreign services receive identical treatment.
Key takeaways
- Residence, nationality, payer scope and actual establishment connection are different tests.
- Select the current rate after identifying the actual source and category.
- Official software examples do not establish one universal SaaS rate.
- Net-fee calculations depend on the actual tax-bearing clause.
- Annual reporting distinguishes 120 days from the partnership 60-day rule.
- Certificates and correction do not guarantee treaty relief, foreign credit or immunity.
Sources
- Official Arabic Income Tax Implementing RegulationsArticles 5 and 63, pp. 5–6 and 34-36: source, actual categories, current rates, gross base and reporting; Articles 68-69, p. 39: delay/fraud distinctions.
- ZATCA General Withholding Tax GuidelineSecond version May 2026: Examples 2, 6 and 7, pp. 15–16 and 24-25; rates, treaty/reporting/penalty distinctions pp. 28–32; actual software/rights analysis p. 23 and 33-36.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.