In brief
Technical/consultancy services in scope use the current 5% domestic category. Foreign performance and relationship do not replace source/classification; goods, management and royalty rights can differ.
Technical and consultancy services within Saudi withholding scope use the current 5% domestic category. The real work, recipient/source and payment determine the result. A service is not technical merely because delivered online, and genuine technical advice does not escape withholding simply because the adviser works abroad.
Apply the actual technical-service definition
Current Arabic Implementing Regulations Article 63(3), p. 34, includes technical, technological and scientific services, studies/research, scientific/geological/industrial surveys, advisory or supervisory work, and engineering services including related plans.
ZATCA’s General Withholding Tax Guideline, second version May 2026, section 2.2.2.2, pp. 22–23, explains that definition. Identify the deliverables and work rather than treating every professional invoice, digital purchase or vendor with technology in its name as the same category.
The definition’s breadth does not remove the need for a Saudi-source payment to the relevant non-resident recipient. An employee salary, pure goods supply, royalty and management contract can require different legal analysis.
Foreign performance does not remove the source rule
Regulations Article 5(3), p. 5, treats technical/consultancy income as Saudi-source where the service is provided to a Saudi resident or connected to activity in the Kingdom. The guideline pp. 22–23 and 41 applies withholding regardless of the service’s performance location in the stated circumstances.
A foreign consultant’s absence of travel to Saudi Arabia therefore does not establish a non-taxable fee. Nor does payment from an offshore group bank account necessarily change the source of the underlying Saudi obligation.
Dariba original comparison: engineering advice supplied remotely to a Saudi business can remain within the technical-service source rule. That is a different transaction from a pure goods purchase or a genuinely separate non-technical service performed entirely abroad. Assess the actual category before relying on location.
Use the current rate for related and unrelated suppliers
Article 63(1)‘s current Arabic table, p. 34, and guideline section 3, p. 28, place technical/consultancy services at 5%. Do not reintroduce an old blanket 15% rate merely because the actual technical supplier is a head office or related company.
Relationship can affect source, transfer-pricing and evidence questions, but it does not turn genuine technical work into a different current rate category automatically. Conversely, labelling management or intellectual-property exploitation as technical support cannot obtain the technical rate.
See the group-payments guide for the separate classification and main WHT guide for gross-base, treaty and recipient conditions.
Distinguish use of technology from the service being sold
The guideline p. 23 explains that advanced technology used to produce a service does not necessarily make the customer payment technical. Its online-game discussion distinguishes development skills from what a consumer purchases when accessing the finished game service.
The same analytical discipline applies to automated access, routine distribution or advertising. Determine what the payer actually receives, not every technical process in the supplier’s business. This does not itself certify a particular platform or subscription as outside withholding.
Dariba recommendation: retain the statement of work and actual outputs. A generic invoice saying IT services can obscure development, ordinary access, management, a licence and independent support within one amount.
Separate services from royalty and know-how rights
Guideline sections 5.1–5.2, pp. 33–36, distinguish applying expertise to perform work from transferring qualifying intellectual-property/know-how rights. A report using the consultant’s experience is not automatically a licence to exploit its proprietary technology.
The classification table on p. 36 distinguishes independent maintenance, design implementation and technical consultancy from specified exploitation rights. Actual software rights and bundled terms still require review; a non-royalty entry does not itself establish no withholding.
Where a contract includes an actual royalty and independent technical services, identify and support the genuine consideration for each. An artificial split or a contract label cannot replace the rights actually granted.
Official examples distinguish pure promotion and goods bundles
Example 6, p. 24, considers a foreign advertising company’s work limited to securing overseas satellite advertising for Saudi products, without film design/studies or Saudi work. On those stated facts the guideline does not treat it as Saudi-source income. It should not be expanded into a blanket exemption for all marketing, creative or related-party services abroad.
Example 7, pp. 24–25, distinguishes equipment supply from associated support/maintenance services, with technical-service withholding on the service consideration on its stated no-permanent-establishment facts. The example’s period wording is not a universal permanent-establishment safe harbour for every short contract.
The contract, deliverables and supported values must explain the distinction. Allocating a nominal fee to installation while moving most service value into equipment does not establish the correct withholding base.
Calculate withholding from the supported gross service amount
Article 63(8) applies withholding to the gross relevant amount, without deducting the recipient’s costs. Dariba original illustration: a supported mixed purchase includes SAR 200,000 of pure equipment and SAR 40,000 gross of independent technical services. Assuming the goods are outside the withholding route, the services are in scope at 5%, and no treaty/other relief applies, WHT is SAR 2,000 on the service amount.
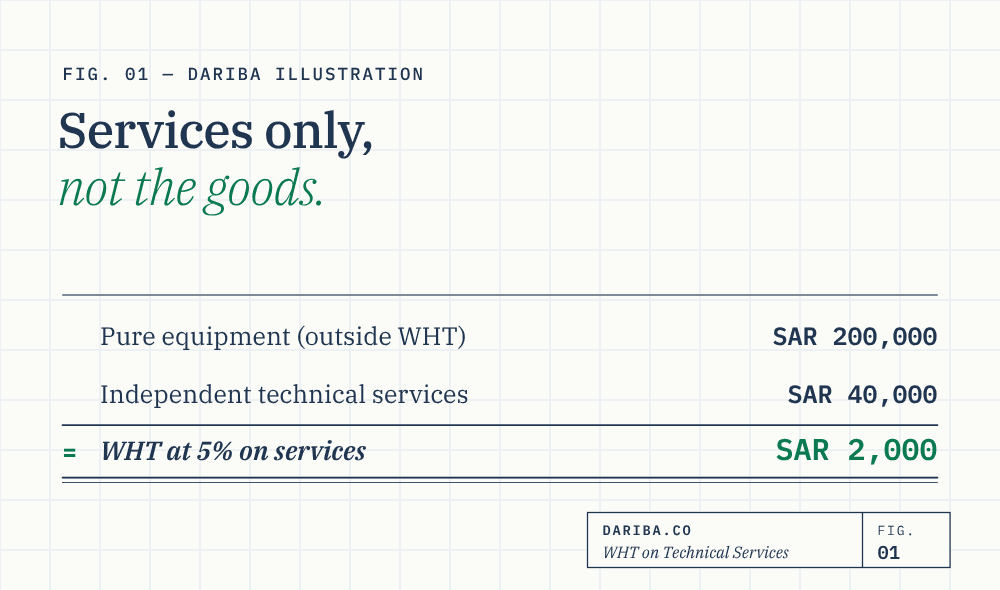
If the agreement promises the supplier a net service receipt or includes other rights, recalculate from the actual tax-bearing terms and classification. The illustration does not decide the values, permanent-establishment status or treaty entitlement for another contract.
VAT on imported goods or received services is separate. A technical-service withholding calculation neither replaces reverse-charge analysis nor permits deduction of WHT as input VAT.
Keep the classification and compliance evidence together
Retain the legal payer/recipient, residence/permanent-establishment connection, actual work and rights, source analysis, supported allocation, payment/settlement date, domestic/treaty basis, return, remittance and certificate.
Payments connected with the recipient’s actual Saudi permanent-establishment activity need their income-tax route considered; the existence of an unrelated Saudi branch is insufficient to decide every foreign invoice. A treaty requires its own current article and procedural conditions checked.
The compliance guide explains monthly/annual reporting and records. Dariba recommends reaching the classification before approving payment so the contract, supplier receipt and withholding evidence all reflect the same actual transaction.
Key takeaways
- Technical work requires the actual Article 63 definition.
- Qualifying Saudi-source technical services can be taxable even when performed abroad.
- The current technical/consultancy category is 5%, not an automatic related-party 15%.
- Technology used in providing a service does not decide the customer payment category.
- Actual royalty/know-how rights and management services have separate analysis.
- Support goods/service allocation, gross base, settlement and compliance evidence.
Sources
- Official Arabic Income Tax Implementing RegulationsArticle 5(3), p. 5; Article 63(1),(3),(8), pp. 34–35: current technical rate, definition and gross base.
- ZATCA General Withholding Tax guidelineSecond version May 2026, pp. 22–25, 28 and 33-41: actual technical service, Examples 6-7 and royalty/service distinctions.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.