In brief
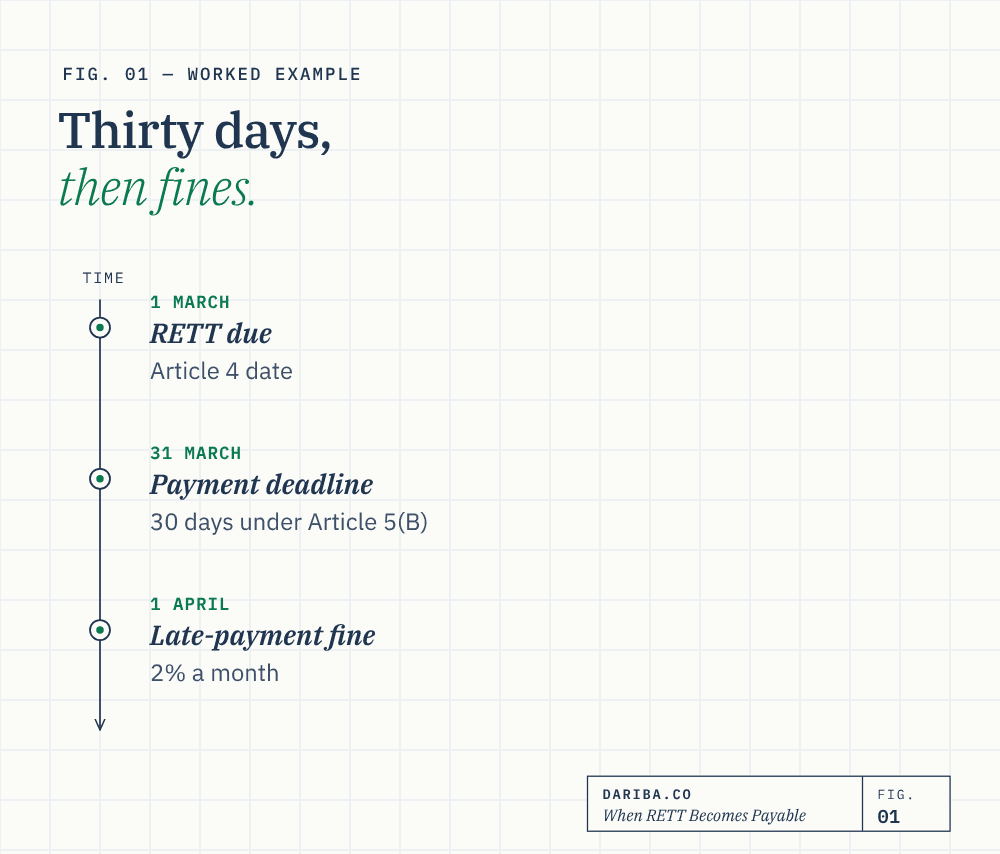
For a sale completed at the notary, RETT is due on the notarization date and must be paid on or before it. For transactions that are not notarized, Article 4 of the Regulations sets the date. The fallback is the earlier of an unconditional agreement or the actual transfer of ownership, with 30 days to pay.
The RETT Tax Due Date: When Does RETT Become Payable? | Dariba.co
The General Rule: Notarization, With Article 4 for Everything Else
Timing matters in RETT. Get it wrong and you are not just late on a payment — you are triggering fines, penalties, and potentially a ZATCA investigation. Understanding exactly when RETT becomes due is not a theoretical exercise; it is a compliance imperative for anyone involved in Saudi real estate transactions.
For most property sales, the answer is simple. ZATCA’s Detailed RETT Guideline (section 4.3) states that the tax-triggering event is the transaction itself, and that the due date is generally the date of notarization with the Notary Public or an Accredited Notary. The tax must be paid on or before that date. The notary will not complete the transfer until the tax is paid or an exemption is confirmed.
Article 4 of the Implementing Regulations covers the cases where notarization has not been carried out. Its opening words limit it to those cases. For such transactions, it sets a specific date by type, and its general rule in Article 4(g) is the earlier of (a) the date an unconditional agreement is concluded, or (b) the date ownership actually transfers.
The phrase “unconditional agreement” matters for those non-notarized deals. An agreement is unconditional when it binds both parties with no remaining conditions that could stop the transfer. A binding SPA with no outstanding conditions precedent qualifies.
Non-Notarized Transactions: Special Rules by Transaction Type
Article 4 of the Implementing Regulations specifies the RETT due date for categories of transaction where notarization does not occur. Each category has its own rule:
| Transaction Type | RETT Due Date | Regulation Reference |
|---|---|---|
| Transfer of possession for ownership purpose (no notarization) | Date property is placed in the possession of the transferee | Article 4(a) |
| Usufruct right exceeding 50 years | Date the right to use is granted (unless cancelled within 30 days) | Article 4(b) |
| BOOT project transfer | Date of actual transfer — when all conditions for ownership transfer are met | Article 4(c) |
| Share transfer in a Real Estate Company | Earlier of: date shares transfer OR date of unconditional agreement | Article 4(d) |
| Off-plan property sale | Date of notarization with Notary Public or Accredited Notary | Article 4(e) |
| Conditional exemption that later becomes taxable | Date of the original disposal that failed to maintain exemption conditions | Article 4(f) |
| All other transactions (general rule) | Earlier of: unconditional agreement date OR actual ownership transfer date | Article 4(g) |
Payment Deadlines: How Much Time Does the Transferor Have?
The due date of RETT and the payment deadline for RETT are related but distinct concepts. Under Article 5 of the Implementing Regulations, different payment deadlines apply depending on transaction type:
Standard Notarized Transactions
For the majority of property sales that proceed through the Notary Public, RETT must be paid on or before the date of notarization. The notary serves as the enforcement mechanism — no payment, no title transfer. This is a hard deadline with no grace period built into the system.
Share Transfers in Real Estate Companies
Where RETT is triggered by the transfer of 30% or more of shares in a real estate company, payment must be made no later than 30 days from the earlier of: the date shares transfer or the date of the unconditional agreement (Article 5(A)(1)). There is no notary backstop here — the parties must proactively manage this deadline.
Non-Notarized Transactions (General)
For non-notarized transactions (usufruct rights, BOOT completions, possession transfers for ownership purposes), RETT must be paid within 30 days from the RETT due date as determined under Article 4 (Article 5(B)).
Off-Plan Sales
As a specific exception, for off-plan property sales, RETT must be paid on or before the date of notarization (Article 5(C)). This aligns with the general notarized transaction rule — the notary will not complete the transfer without RETT confirmation.
Conditional Exemptions That Become Taxable
If a previously exempt transaction loses its exemption status due to a breach of conditions, RETT must be paid within 30 days from the date of the breach (Article 5(A)(2)). The transferor must also notify ZATCA via a correction request within 30 days of becoming aware the data is incorrect or the exemption condition is breached.
The Off-Plan Exception: A Different Timeline
Off-plan transactions have a materially different RETT timing rule that is frequently misunderstood. When a buyer purchases a unit off-plan — before construction is complete and before a title deed exists — the RETT due date is the date of notarization with the Notary Public or Accredited Notary, not the date the off-plan purchase agreement is signed (Article 4(e)).
This means RETT is not due when the off-plan sale contract is executed. It is due when the completed unit is notarized — which could be one, two, or more years later. For developers managing large off-plan projects, this deferred RETT obligation must be built into financial planning. The RETT liability crystallises at completion, not at booking.
The same timing rule applies for resales of off-plan units before completion. If an off-plan buyer resells their unit before construction is complete, the RETT on that intermediate transfer is also due at notarization (once the property is completed and title is registered), not at the point of the intermediate assignment agreement.
Conditional Exemptions: When the Clock Runs Back
Several RETT exemptions are granted on conditions that must continue to be met after the transaction date. These include:
- The gift exemption: the donee must not re-dispose of the gifted property to a non-qualifying person within three years
- The in-kind contribution exemption: the shares received in exchange must be held for at least five years
- The wholly-owned group transfer exemption: ownership must remain within the same group for five years
- The merger and acquisition exemptions: continuing share/unit ownership conditions apply for five years
If any of these conditions are breached after the original transaction was granted an exemption, the original transaction becomes taxable. The full RETT that would have been due on it, calculated on its value, becomes payable. The timing runs from the breach, not from the original transaction. Article 4(f) ties the due date to the disposal that broke the conditions, and Article 5(A)(2) allows 30 days from the breach to pay. Late-payment fines start only after that window.
The transferor must submit a correction request to ZATCA within 30 days of becoming aware of the breach, and pay the RETT within 30 days of the breach date. Failing to do so adds penalty exposure on top of the principal RETT amount.
Key takeaways
- For notarized sales, RETT is due on the notarization date, and the notary will not complete the transfer until it is paid. The earlier-of-agreement-or-transfer rule in Article 4(g) applies only to transactions that are not notarized.
- Off-plan sales are a specific exception: RETT is due at the date of notarization with the Notary Public or Accredited Notary, not at the off-plan agreement date.
- For notarized transactions, payment must be made before notarization. The Notary Public will not proceed without the RETT payment confirmation.
- For share transfers in real estate companies, the 30-day payment window runs from the earlier of the share transfer date or the unconditional agreement date.
- BOOT project RETT is due on the date of actual transfer — when all contractual conditions for ownership transfer are met.
- Conditional exemptions that are later breached make the original transaction taxable. The 30-day payment window, and any late-payment fines after it, run from the breach date.
- ZATCA can accelerate payment demands where delayed payment appears to be deliberately planned to defer RETT obligations.
Frequently asked questions
When is RETT due — at the SPA or at notarization?
For a sale that is notarized, RETT is due on the notarization date and must be paid on or before it. ZATCA's Detailed RETT Guideline (section 4.3) confirms this. Signing an SPA does not start the clock for a notarized sale. The earlier of an unconditional agreement or the actual transfer applies only to transactions that are not notarized (Article 4(g)), and those have 30 days to pay. Off-plan sales are due at notarization.
How long after a share transfer in a real estate company must RETT be paid?
Within 30 days from the earlier of: the date the shares are actually transferred, or the date an unconditional agreement is signed to transfer them. This is a proactive deadline — there is no notary backstop for share transfers, so the parties must manage it independently.
What is the RETT deadline for a BOOT project?
RETT is due on the date of the actual transfer of ownership — meaning the date on which all conditions required by the BOOT contract for the transfer are met. For payment, the 30-day window from that date applies (as a non-notarized transaction).
If an exemption condition is violated years after the transaction, when is RETT due?
RETT is due from the date of the original transaction — not from the date the condition was violated. The full RETT amount that would have been due on the original transaction is triggered retroactively. Payment must be made within 30 days of the breach, and a correction request must be submitted to ZATCA.
Is there a grace period for RETT payment?
For notarized transactions, the deadline is absolute — RETT must be paid before notarization proceeds. For non-notarized transactions (share transfers, usufruct rights, BOOT completions), a 30-day window applies. ZATCA also has the power to accelerate the payment deadline in cases where it determines that delaying payment was the main purpose of the transferor.
Sources
This article reflects the RETT Law (Royal Decree M/84, effective 10 April 2025) and the RETT Implementing Regulations (ZATCA Board Resolution 01-03-25, 24 March 2025). It is for informational purposes only and does not constitute legal or tax advice. Readers should confirm the current position with ZATCA guidance or a qualified Saudi tax advisor. dariba.co is an independent platform with no consulting relationships.