In brief
The current Article 50 categories have qualifications and exceptions. ZATCA contrasts voluntary team meals with legally required catering; removing a restriction still does not establish full recovery.
The April 2025 VAT amendment guidance calls for a review of the expenditure and the statutory exceptions together. For employee benefits and vehicles, the useful question is whether the specific legal conditions are met, rather than whether the business has historically coded the cost as recoverable or blocked.
This article explains the input-tax restriction review associated with ZATCA’s April 2025 Amendment Guideline, particularly section 2.11. For a historic return, establish the operative legislative version and commencement provisions. A guideline’s issue date alone is not a substitute for that period analysis, nor does a current summary prove that an expense was deductible under an earlier version.
Read the current seven categories with their qualifications
Article 50(1) addresses seven categories, not seven unconditional permanent denials:
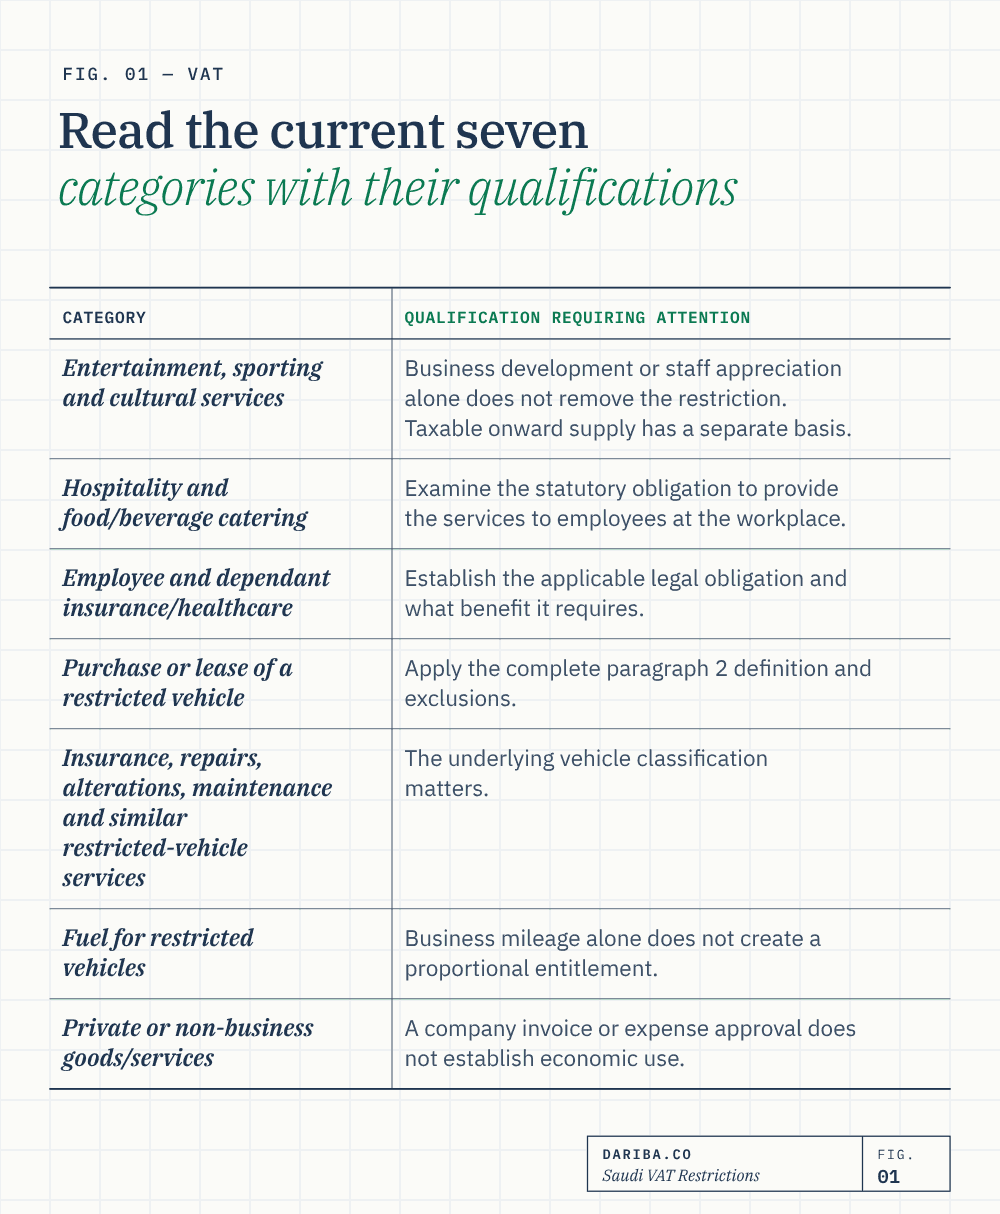
| Category | Qualification requiring attention |
|---|---|
| Entertainment, sporting and cultural services | Business development or staff appreciation alone does not remove the restriction. Taxable onward supply has a separate basis. |
| Hospitality and food/beverage catering | Examine the statutory obligation to provide the services to employees at the workplace. |
| Employee and dependant insurance/healthcare | Establish the applicable legal obligation and what benefit it requires. |
| Purchase or lease of a restricted vehicle | Apply the complete paragraph 2 definition and exclusions. |
| Insurance, repairs, alterations, maintenance and similar restricted-vehicle services | The underlying vehicle classification matters. |
| Fuel for restricted vehicles | Business mileage alone does not create a proportional entitlement. |
| Private or non-business goods/services | A company invoice or expense approval does not establish economic use. |
See section 2.11, pages 40-42 of the Amendment Guideline and the controlling Arabic Article 50, pp. 50-51.
The current list is not evidence that every voluntary benefit was recoverable before the amendment. When reviewing an earlier claim, compare the actual historical rule, supply and use, instead of treating a before-and-after headline as an entitlement test.
Official examples: a team dinner and legally required catering
Example 23, section 2.11, page 41, concerns Ahmad, the owner of a beauty-products retail company, taking his marketing team to dinner to thank them for improving sales. They discuss work and future opportunities. ZATCA disallows the dinner VAT on those facts: the benefit is a voluntary initiative rather than a legal obligation.
Example 24, pages 41-42, concerns Al-Dhahabi Construction Company and catering for employees at remote project locations. ZATCA permits deduction on the stated facts because provision is a legal obligation. Read both examples, including the continuation of Example 24.
Dariba’s analysis. The decisive difference is not that one business is retail and the other construction. It is the nature of the service and the legal obligation in the relevant circumstances. A voluntary remote-site meal should not be assumed recoverable merely because the project resembles the example. Conversely, a statutory exception should not be denied because an accounting policy blocks all catering indiscriminately.
Keep the applicable obligation, covered employees, workplace facts and supplier scope in the review file. These are recommended evidence categories, not a new ZATCA-prescribed application form.
Employee healthcare: establish the required benefit and enhancements
Article 50(1)(c) requires a review of the statutory obligation. A voluntary contractual promise or a market expectation does not, by itself, establish that exception. Identify the persons covered and the benefit the applicable Saudi rule requires before considering any enhancement.
The Input Tax Deduction Guideline, third version, May 2026, section 7.2, Example 21, page 31 permits deduction for the legally required employee/dependant cover in its manufacturing-employer scenario. Section 7.1, Example 16, page 29, also distinguishes required cover and additional benefits. Neither example establishes identical eligibility for every employer, person or policy upgrade.
For a combined policy, ask whether components can be identified reliably from the contractual and pricing evidence. Do not invent an allocation percentage merely to produce a claim, or assume a broad HR confirmation resolves the VAT analysis.
Removing the Article 50 restriction is only one stage. Exempt activities, non-economic use and evidence requirements can still limit the deduction.
Dariba illustration: statutory cover in a mixed business
Assume a business receives correctly charged VAT of SAR 20,000 on separately evidenced cover: SAR 15,000 relates to benefits meeting the statutory exception, and SAR 5,000 to a voluntary enhancement that remains restricted on the assumed facts. The eligible cover is a shared cost for taxable and exempt activities, with a valid applicable 70% recovery proportion and no non-economic use.
The assumed deduction is SAR 15,000 x 70% = SAR 10,500. It is neither the whole SAR 20,000 nor automatically SAR 15,000. These are original Dariba facts, not a ZATCA example or an approved allocation for a particular policy.
If the enhancement also satisfies a statutory obligation on different facts, its restriction analysis changes. If the eligible cost is exclusively and directly attributable to taxable activity, its attribution may differ. The result therefore depends on the obligation, the actual components and their use.
Vehicle capacity does not replace private-availability analysis
Article 50(2) starts with a vehicle designed to carry no more than ten persons, then excludes specified heavy equipment used exclusively for economic activity without private availability; vehicles for taxable resupply; registered emergency vehicles; and vehicles used exclusively for economic activity without private availability.
A nine-seat business vehicle is not automatically restricted just because of its capacity. It must still be tested against those exclusions. Equally, a vehicle available privately does not qualify merely because most journeys are business-related.
The current Input Tax Deduction Guideline, section 7.2, Example 19, page 32 denies deduction where employees have private use on Thursdays and Fridays. It does not provide a business-days or mileage apportionment concession for a vehicle that remains restricted.
Review actual custody, permitted journeys and operating practice alongside policy documents. A written ban on private use is evidence, not conclusive proof if the vehicle is in fact available privately. Do not omit the no-private-availability condition when assessing heavy equipment either.
Taxable resale and subsequent disposal need their own facts
Article 50(1) recognises taxable onward supply, while paragraph 4 concerns listed services acquired for resale without the purchaser’s own use. A caterer buying services for taxable customers has a different position from an employer consuming them at a staff event. A recharge label alone does not prove that the conditions are met.
Paragraph 3 separately addresses a later supply of a restricted vehicle treated as acquired outside the economic activity. It is not a universal rule that every asset bought without input recovery can subsequently be sold without output VAT. Apply the provision to the particular vehicle and its acquisition treatment.
Convert the amendment review into supported corrections
For each affected category, record the applicable period, restriction, exception, facts, evidence and remaining attribution. Where an earlier return appears wrong, quantify the actual error and assess the correction route for that period. Do not stop all medical or catering recovery, or reverse historic deductions wholesale, solely because a headline describes a new block.
This is an Article 50-focused review. Activity transfers, joint liability and other amended provisions require their own transaction analysis rather than being treated as an additional input-tax restriction. Use the full Article 50 guide and input VAT framework for the connected entitlement and apportionment decisions.
Key takeaways
- The seven current categories must be read with their exceptions; the guideline issue date does not establish the rule for every earlier return.
- Amendment Examples 23-24 contrast a voluntary team dinner with catering provided under the stated legal obligation.
- Identify legally required healthcare or cover and any enhancements from reliable evidence, then apply the remaining attribution rules.
- Capacity is only part of the restricted-vehicle test; exclusive economic use and absence of private availability matter.
- A taxable onward supply, services bought for resale and a later vehicle disposal each have different conditions.
- Correct an earlier return from its actual rule, facts and quantified error rather than reverse whole categories indiscriminately.
Sources
- ZATCA - VAT Implementing Regulations, Arabic tenth edition, April 2025Article 50, document pp 50-51; controlling Arabic text.
- ZATCA - VAT Amendment Guideline, issue 1, April 2025Section 2.11, pp 40-42; Example 23 p 41 and Example 24 pp 41-42.
- ZATCA - Input Tax Deduction Guideline, third version, May 2026Sections 7.1-7.2, Examples 16, 19 and 21, pp 29-32.
General information only. Treatment depends on the facts, applicable period and controlling Arabic legislation. Dariba analysis and original illustrations are distinguished from official examples. Seek advice or clarification for an unresolved specific arrangement.