In brief
The ordinary ten-year rule does not itself make a property purchase taxable. Determine correctly incurred VAT, initial use, the applicable period and later events; historical ZATCA examples retain their original tax assumptions.
Real estate creates two separate VAT questions: what tax was correctly incurred on the acquisition or works, and how the resulting capital asset is used over time. A ten-year adjustment rule does not itself make a property purchase subject to VAT or make the original tax deductible.
Article 52 applies the ordinary ten-year period to qualifying immovable capital assets permanently attached to land or real estate, with a shorter-accounting-life rule where applicable. The initial deduction, review cycle, later improvements and disposal events must each be identified before calculating an adjustment.
Separate a property transfer from construction and leasing
Article 30(1)(a) exempts the specified transfer of real estate ownership or disposal as owner, including commercial and residential property, subject to the applicable provisions. It is not merely an exemption for bare land. Residential rental has its separate exemption, while qualifying commercial leasing has a different VAT treatment.
Consequently, a current example of buying a commercial building should not simply assume 15% VAT on its purchase price. Construction, professional services, equipment and later works may have their own VAT treatment; establish the supply actually received and the tax correctly charged.
The Financial Services Guideline, second edition, May 2026, section 8.5.2, page 58 expressly cautions about the real-estate VAT exemption in its capital-asset discussion. The controlling Arabic Article 30, pp. 28-29 distinguishes the relevant categories.
RETT paid on a property transaction is not input VAT to deduct in a VAT return. Any eligible-developer refund route also needs its own conditions; it should not be assumed to be ordinary Article 49 recovery.
Identify the capital asset and initial qualifying use
Establish whether expenditure produces an asset held for long-term use, rather than inventory held for sale or an ordinary expense. Then identify whether the asset is immovable and permanently attached for Article 52 purposes. The treatment of removable equipment should not be assumed from its location inside a building.
At acquisition, use Article 49 entitlement, Article 50 restrictions and Article 51 attribution to determine the initial deduction. A shared building or improvement is not automatically assigned the same recovery percentage as the whole business if its actual intended use differs. Retain the allocation and evidence supporting it.
Ten years and the twelve-month reporting cycle
Distinguish Article 52(2)‘s adjustment period from paragraph 5’s reporting cycle. Where the accounting useful life is shorter than the ordinary period, the shorter life applies, with part-years counted as whole years under the provision.
The first twelve-month review cycle begins at the start of the tax period in which the asset was acquired, and the adjustment is included in the last tax period falling within that cycle. It is not necessarily a December return.
Official illustration. In Capital Assets Guideline, version 2, May 2026, section 6.2, Example 5, page 31, a facility acquired on 20 July 2020 has a five-year accounting life and a first review period beginning on 1 July 2020. The example supports the shorter-life and tax-period-start rules; it does not make every building a ten-year December schedule.
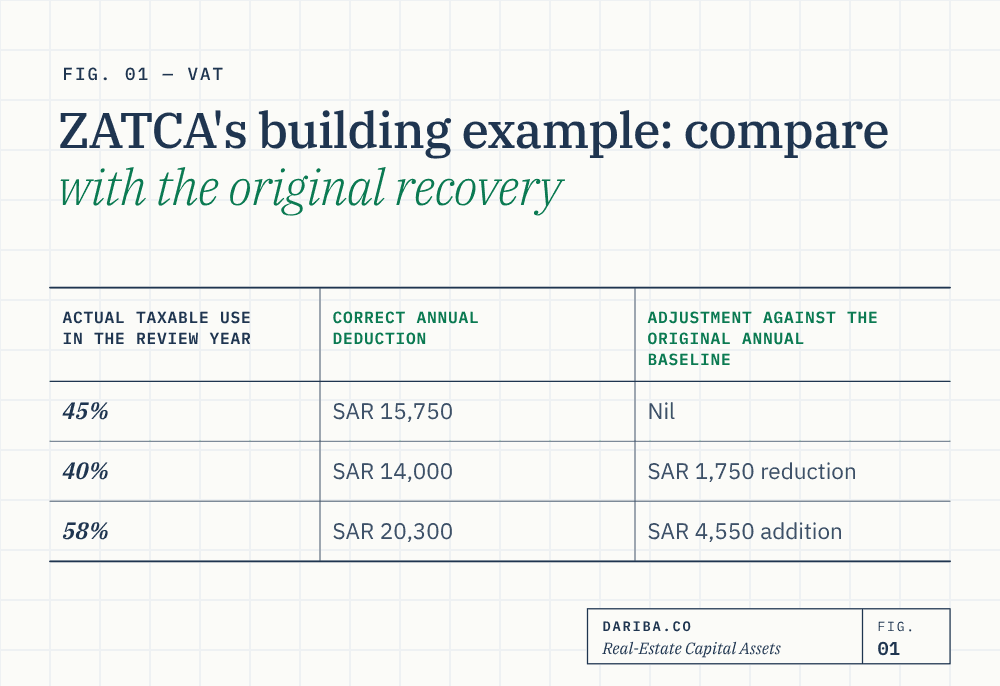
ZATCA’s building example: compare with the original recovery
Example 7, section 6.3.2, pages 36-37, concerns Red Sea Development Company’s April 2019 office-building acquisition with SAR 350,000 VAT and 45% initial recovery. The original deduction is SAR 157,500, and the annual baseline over ten years is SAR 15,750. Read the complete official example.
| Actual taxable use in the review year | Correct annual deduction | Adjustment against the original annual baseline |
|---|---|---|
| 45% | SAR 15,750 | Nil |
| 40% | SAR 14,000 | SAR 1,750 reduction |
| 58% | SAR 20,300 | SAR 4,550 addition |
These historical figures illustrate the mechanism, not current VAT treatment on purchasing a building. They have been independently recalculated from the stated VAT, recovery percentage and period.
Dariba’s analysis. Each year is compared with the original 45%, rather than the immediately preceding year’s use. At 58%, the difference is thirteen percentage points from 45%, not eighteen from 40%. The annual adjustment uses total original VAT divided by the adjustment period, multiplied by that percentage-point change; multiplying the already reduced baseline by the change again would understate the result.
Dariba illustration: taxable construction services and mixed use
Assume a registered business incurs SAR 450,000 of correctly charged VAT on qualifying construction services producing an immovable capital asset. The ten-year period applies, initial qualifying taxable use is 80%, all other entitlement conditions are met and no special refund route is being assumed. These are original Dariba facts; they do not assume VAT on a current property purchase price.
Initial recovery is SAR 360,000 and the annual baseline is SAR 36,000. If actual taxable use in a review year is 60%, the correct annual deduction is SAR 27,000, producing a SAR 9,000 reduction. If use is instead 90%, the correct annual deduction is SAR 40,500, producing a SAR 4,500 addition.
The formula is SAR 450,000 / 10 x (actual use - 80%), using percentages as decimals. Verify how use is measured. A floor-area change does not automatically prove the correct taxable-use percentage for every asset or cost; support the allocation and any required method approval.
Improvements have separate expenditure and dates
Article 52(3) treats qualifying construction, enhancement and improvement expenditure as acquisition or additional acquisition expenditure, with the additional period starting on completion of the works. It does not restart the original asset’s entire period.
Identify whether later works are a qualifying capital improvement and which category and period apply, rather than assign every repair invoice a fresh ten-year schedule. Retain the original asset and each later capital project separately, with its own VAT, initial recovery, completion date, useful-life basis and subsequent use.
Sale and permanent changes need transaction-specific treatment
A partial change in actual taxable/exempt use within a continuing mixed asset requires review under the annual adjustment rules. Do not extrapolate that automatically to a permanent switch to wholly exempt use. The interaction between Article 52(1) and (8) and the guidance’s economic-activity explanation must be assessed on the actual facts; seek clarification where the correct route remains unresolved.
Similarly, the Capital Assets Guideline’s section 6.5 disposal illustration assumes a taxable sale. An exempt property transfer should not automatically be treated as 100% taxable remaining use by copying that formula. Determine the transaction’s output treatment, applicable adjustment provision and remaining period separately. A zero initial deduction, an idle asset retained for economic activity, theft and destruction each require their own analysis.
Article 49(9) is separate historical relief associated with the 2020 real-estate exemption transition. It has conditions for pre-exemption costs, specified deduction periods ending no later than 31 December 2020, and proportionate treatment where relevant. It is not a general protection for all prior property deductions or a new claim route for current exempt sales.
Keep records for the correct period
Article 66(1) distinguishes the ordinary six-year retention rule from capital-asset records kept for the applicable adjustment period plus five years from ownership. For an ordinary ten-year immovable-asset period, that gives a fifteen-year horizon; the shorter-life rule and the actual record history still need attention.
The Capital Assets Guideline, section 8.3, page 48 summarises the extended retention periods. Preserve the original tax evidence, intended use, recovery calculation, acquisition/review dates, later works, annual use evidence and disposal decisions. This allows a reviewer to reconstruct the adjustment instead of infer it from a property ledger balance.
Primary provisions: Arabic Article 52, pp. 53-54, and Article 66(1), p. 67. See also the general capital-adjustment guide.
Key takeaways
- Current commercial and residential property transfers have an exemption distinct from construction services and commercial leasing.
- Identify the immovable capital asset and actual intended use before assigning an adjustment period or initial recovery.
- A shorter accounting life can control, and the first twelve-month review starts with the acquisition tax period.
- ZATCA Example 7 compares each year with original 45% recovery; its 2019 property purchase is a historical fact pattern.
- Use total original VAT divided by the period and the percentage-point change, rather than reapplying it to a partly deductible baseline.
- Qualifying improvements have separate dates and periods; repairs do not automatically restart the original schedule.
- Exempt disposal and permanent wholly exempt use require specific analysis; preserve the applicable adjustment-period-plus-five-year records.
Sources
- ZATCA - VAT Implementing Regulations, Arabic tenth edition, April 2025Article 30, document pp 28-29; Article 49(9), pp 49-50; Article 52, pp 53-54; Article 66(1), p 67.
- ZATCA - Capital Assets Guideline, version 2, May 2026Section 6.2 Example 5 p 31; section 6.3.2 Example 7 pp 36-37; sections 6.5-6.6 pp 39-42; section 8.3 p 48.
- ZATCA - Financial Services Guideline, second edition, May 2026Section 8.5.2, p 58: real-estate exemption caution in the capital-asset discussion.
General information only. Treatment depends on the facts, applicable period and controlling Arabic legislation. Dariba analysis and original illustrations are distinguished from official examples. Seek advice or clarification for an unresolved specific arrangement.