In brief
Prevent WHT errors in scope, contract allocation, software rights, gross-up, treaty evidence and settlement with current official rules and worked examples.
Procurement can prevent withholding disputes by establishing the contract facts before the first settlement. This is an operating recommendation, not a claim that one prescribed tax approval workflow is compulsory for every business. The objective is to give finance a supported source, category, recipient and gross/net analysis that matches what the business actually buys.
Mistake: selecting a rate before identifying the payment
Current Arabic Income Tax Implementing Regulations Articles 5 and 63 distinguish source and actual income categories. ZATCA’s General Withholding Tax Guideline, second version May 2026, section 3, p. 28, reproduces the domestic rate table. A vendor’s name, invoice heading or country alone does not establish all these tests.
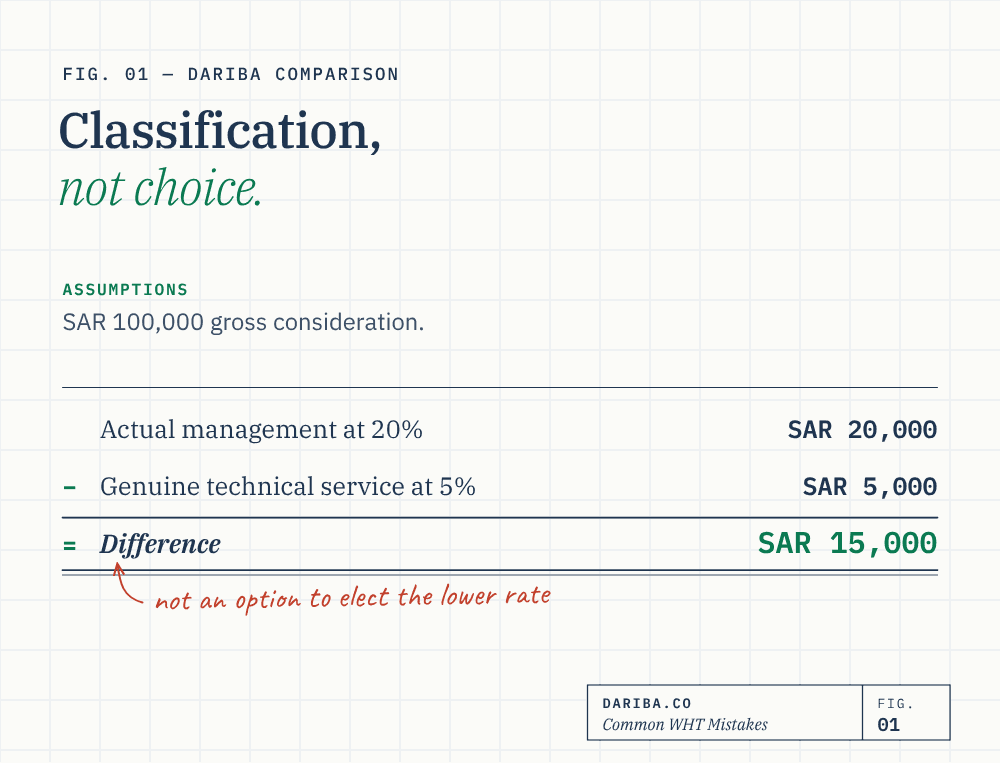
Actual management, royalty and technical consideration use different domestic categories: 20%, 15% and 5% respectively within scope. Do not turn a technical label into proof that a supplier has no responsibility for managing operations, or assume every head-office recharge is management.
Dariba original comparison: on SAR 100,000 gross consideration, an assumed actual 20% management classification gives SAR 20,000 tax, while a genuinely different 5% technical service gives SAR 5,000. The SAR 15,000 difference is not an option to elect the lower rate; the actual deliverables and responsibilities decide classification.
Mistake: relying on offshore performance or the group’s nationality
Article 5(3), p. 5, specifically addresses Saudi-source technical/consultancy services, including relevant work performed abroad. The payer’s Zakat position and the recipient’s GCC incorporation do not themselves remove a withholding duty.
Conversely, a blanket statement that every foreign service is Saudi-source is too broad. Record the source provision and actual facts. Official guideline Example 6, p. 24, distinguishes pure foreign advertising placement on its stated facts from other work.
Dariba recommends capturing the contracting party, actual recipient, residence, service scope, performance and Saudi activity connection in the vendor file. Review a changed payee or scope rather than treating an offshore bank instruction as a tax conclusion.
Mistake: treating an invoice split as conclusive
Regulations Article 5(7) addresses pure goods imports and associated work; guideline Example 7, pp. 24–25, illustrates goods and support on its stated facts. Actual independent services and supported consideration matter. The example’s inconsistent short-visit wording should not be treated as a universal permanent-establishment safe harbour.
Ask which deliverables are separately supplied, which rights or work are inseparable, and how the values were supported. Artificially shifting consideration into goods cannot establish a no-withholding result merely because the invoice totals still agree.
Retain the executed scope, pricing, deliverables and amendments. Separate pricing can improve the evidence where separation is real; it does not replace substantive classification.
Mistake: treating every software or subscription fee alike
Guideline pp. 23 and 33–36 distinguish actual intellectual-property/know-how rights, independent software-related services and technology used by a supplier. A finished service delivered through software does not become technical merely because developers built it.
Neither every on-premise licence at 15% nor every cloud subscription at 5% is supported as a universal rule. Read actual exploitation, modification, reproduction/distribution, support and access terms. A non-royalty outcome is not automatically no withholding.
The software guide explains these boundaries. Dariba recommends reviewing material renewals where the actual rights or service package changes, rather than automatically reusing an old tax code.
Mistake: agreeing a net fee without calculating the tax-bearing terms
Article 63(8), p. 35, uses the full relevant consideration without deducting the recipient’s expenses. Dariba original assumptions: a supplier must receive SAR 80,000 net for an actual management service within scope at 20%, the payer bears tax and no relief applies. Gross consideration is SAR 100,000, including SAR 20,000 withholding.
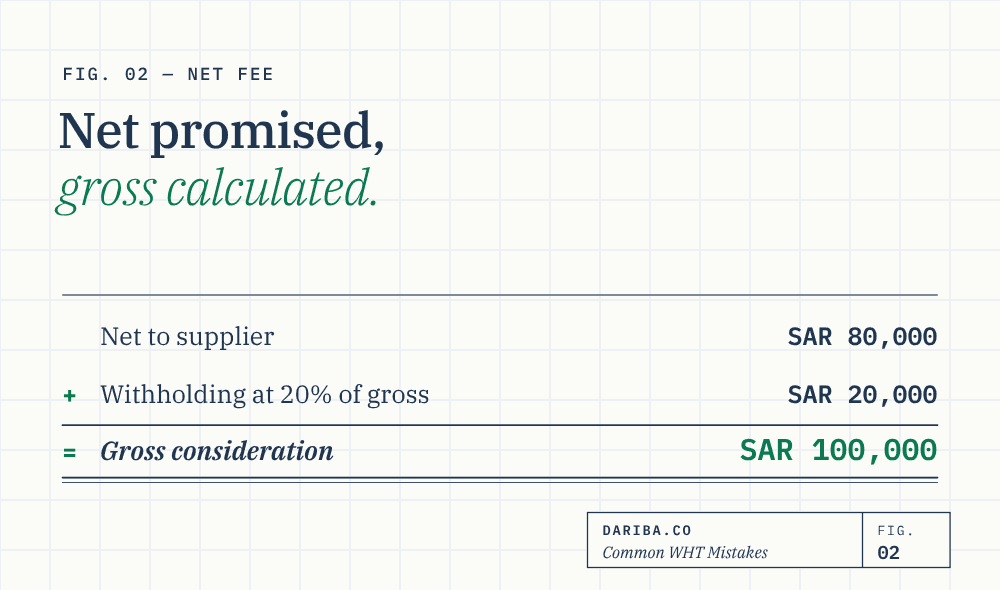
Adding 20% to the net SAR 80,000 gives SAR 96,000; withholding 20% of that amount leaves SAR 76,800, not the promised SAR 80,000. The correct calculation depends on the actual net/gross agreement and category.
Identify who bears the economic cost before agreeing the payment clause. This recommendation does not certify every contract’s enforceability or the expense’s income-tax/Zakat deductibility. Keep VAT analysis separate.
Mistake: promising treaty treatment without a supported route
Guideline section 4, p. 29, recognises possible treaty reduction/exemption. Check the current agreement and period, actual recipient, relevant article, residence/entitlement conditions, establishment connection and required procedure before promising an outcome.
Do not infer entitlement from a group headquarters address, generic certificate or intermediary’s bank details. Nor should procurement invent a universal certificate-expiry period or assume that one direct-relief/refund mechanism applies to every case.
Record who must supply the relevant evidence and when the actual procedure requires it. Where the information is missing, establish the lawful payment/reporting route; an assurance in commercial correspondence is not a substitute for the necessary facts.
Mistake: overlooking non-cash settlement and the reporting calendar
Guideline p. 17 includes cash, in-kind payments and liability-discharging offsets/settlements. Group netting can require payment analysis even without a fresh bank transfer; a mere unpaid accrual is not automatically the same event.
Article 63(9), pp. 35–36, ordinarily requires the monthly statement within the first ten days of the following month; verify the actual official deadline. Annual information generally uses 120 days, with 60 days for partnerships. Do not defer monthly obligations to the annual reconciliation.
Dariba recommends a settlement-to-return handoff identifying the actual month, relevant gross amount, rate/relief basis, remittance and recipient certificate. The compliance guide sets out the underlying rules and record retention.
Mistake: assuming correction automatically removes the consequences
If a review finds an error, substantiate the correct treatment and reconcile affected tax and periods. The penalty guide explains the completed 30-day unpaid-tax calculation, actual fraud conditions and conditional relief.
Early correction can reduce continued unpaid balances and improve the evidence, but it does not promise immunity, a refund, automatic waiver or a predetermined audit result. An ordinary error is also not automatically fraud. Use the actual notice and current procedural requirements for a disputed assessment.
Dariba recommends a decision file linking the contract, source/category, recipient, allocation, tax-bearing clause, settlement and reporting evidence. That lets finance explain the position consistently rather than reconstructing it from a short invoice after a dispute begins.
Key takeaways
- Define the actual source, work, rights and recipient before selecting a tax code.
- A genuine supported allocation differs from an artificial invoice split.
- Gross-up clauses require the actual net/gross calculation before settlement.
- Treaty entitlement and procedure require the actual current agreement and recipient.
- Identify non-cash settlement and preserve monthly/annual reporting distinctions.
- Correction does not automatically remove tax, penalties or evidence requirements.
Sources
- Official Arabic Income Tax Implementing RegulationsArticles 5 and 63, pp. 5–6 and 34-36: source, actual categories, current rates, gross base and reporting; Articles 68-69, p. 39: delay/fraud distinctions.
- ZATCA General Withholding Tax GuidelineSecond version May 2026: Examples 2, 6 and 7, pp. 15–16 and 24-25; rates, treaty/reporting/penalty distinctions pp. 28–32; actual software/rights analysis p. 23 and 33-36.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.