In brief
Analyse actual royalty rights, know-how, Saudi source, gross consideration and treaty conditions with the May 2026 ZATCA classification guidance.
Royalty withholding depends on the rights granted and the Saudi-source rules. A licence, know-how transfer, ordinary service and disposal of an asset can have different treatment. Neither a one-off payment nor a contract headed services determines the answer. Establish what the recipient permits the payer to use or exploit.
Identify the actual intellectual-property or exploitation right
ZATCA’s General Withholding Tax Guideline, second version May 2026, section 5.1, pp. 33–34, explains the Income Tax Law’s royalty definition, including consideration for use/right to use specified intellectual property, know-how/experience information and natural/mineral exploitation rights.
Current Arabic Implementing Regulations Article 63(1), p. 34, applies the domestic 15% royalty category to an in-scope payment. The scope and source conditions remain necessary; the table is not a tax on every payment involving a creative business.
Read the actual rights: copyright, patent, trademark, confidential process, franchise, proprietary knowledge or another relevant interest. An invoice’s word licence or purchase is useful context but cannot replace the agreement.
Establish Saudi source before calculating the rate
Income Tax Law Article 5 addresses intellectual/industrial property used or licensed for use in Saudi Arabia and other relevant source categories. The actual payer, non-resident recipient, use/right and any permanent-establishment connection must be assessed.
Paying to an offshore bank account does not independently make the income foreign-source. Equally, merely having a Saudi shareholder or a Saudi customer somewhere in the chain does not answer every licence’s source and recipient facts.
The main WHT guide explains the framework. Confirm the contracting rights-holder or actual recipient rather than assume a collection agent or group treasury entity automatically has the same treaty position.
Distinguish know-how transfer from expertise used in a service
Guideline section 5.2, p. 35, contrasts transfer of proprietary knowledge enabling the recipient to use it with a supplier applying expertise to perform a service. Its particular computer-technology discussion should not erase the broader statutory definition of industrial, commercial or scientific experience.
A consultant can use considerable experience to produce advice without transferring its protected process for the customer to exploit. Conversely, calling a proprietary production-process transfer technical assistance does not remove the rights actually granted.
Dariba recommendation: document confidentiality, ownership, permitted use, exploitation/reproduction/modification rights, delivery obligations and what remains with the supplier. These terms often explain the classification more clearly than whether the fee is hourly or fixed.
Use the official classification table within its stated facts
The guideline p. 36 identifies specified patent/trademark/confidential-process, franchise, know-how, natural-resource and copyright rights as royalty cases. It distinguishes design implementation, independent maintenance and technical consultancy from royalty consideration on their stated descriptions.
It also gives specific database and customizable-software rights examples. Do not broaden one entry into a universal rule for every subscription, cloud service, database purchase or software licence. Actual rights and terms still matter.
A non-royalty result does not itself mean no withholding. The transaction may instead be technical, management, rent or another in-scope service. See the software guide and technical-services guide for those boundaries.
Payment frequency and goods labels do not decide the right
Section 5.1, pp. 33–34, discusses royalties negotiated as fixed amounts, per-unit amounts or revenue/profit percentages. A lump sum therefore does not automatically cease to be royalty consideration; periodic billing does not automatically make a payment one.
Likewise, transferring a device containing software and granting exploitation rights are not necessarily the same transaction. An asserted outright asset disposal requires the actual rights and applicable capital-gain/ordinary-income route considered, rather than an automatic no-WHT conclusion from the word sale.
Where a contract genuinely includes separate goods, services and rights, support their nature and value. An artificial allocation cannot change the substantive rights supplied.
Apply the supported gross base and tax-bearing terms
Article 63(8) uses the full relevant consideration without deducting the recipient’s costs. Dariba original illustration: a SAR 100,000 gross royalty within scope at 15%, without treaty/specific relief, produces SAR 15,000 WHT and SAR 85,000 supplier receipt.
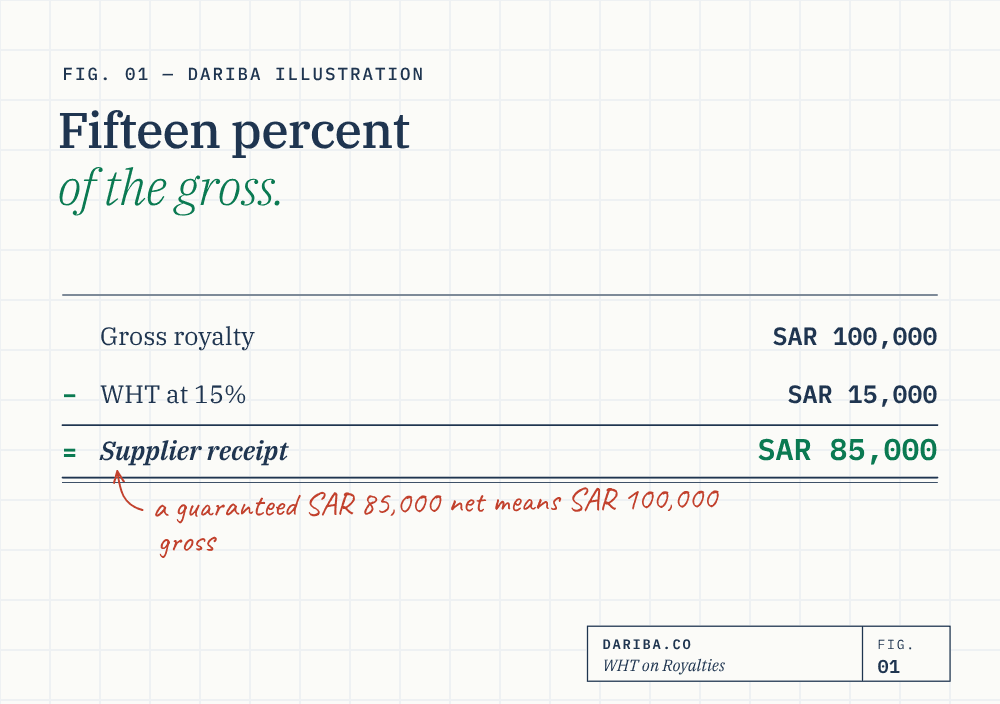
If the contract instead guarantees that SAR 85,000 net receipt and the payer bears the same 15% tax, the assumed gross amount is SAR 100,000. Confirm the agreement rather than add 15% to the net amount and assume the calculation is complete.
These figures are original illustrations. They do not certify a specific right, treaty article, beneficial-recipient entitlement or expense deduction. VAT on foreign rights/services requires its own analysis and does not disappear because WHT was paid.
Treaty relief and permanent-establishment cases need the actual route
Guideline section 4, p. 29, recognizes possible treaty exemptions/reductions. Check the current treaty applicable to the actual recipient/payment period, its definition and entitlement conditions, any permanent-establishment connection and the required ZATCA mechanism.
Do not select a treaty rate from the group’s headquarters country where another entity actually receives the royalty. A residence certificate supports a fact but does not prove all conditions or make domestic withholding classification irrelevant.
Payments connected with the recipient’s Saudi permanent-establishment activity can require the income-tax route considered. The mere existence of some Saudi establishment is not an automatic exemption for every foreign royalty.
Retain a rights file alongside the withholding records
Keep the executed licence, actual scope/use, rights-holder/recipient, source facts, service/goods allocation, pricing basis, gross/net clause, treaty evidence, settlement, return/payment and certificate. Preserve amendments that change what the payer may exploit.
The compliance guide explains the actual monthly/annual and retention rules. A generic supplier invoice often cannot establish why a payment was royalty, a service or outside withholding.
Dariba recommends making the tax classification part of licence review before payment. Where the available provisions/guidance do not resolve a particular instrument’s rights clearly, obtain the missing facts or an appropriate clarification rather than present an unqualified rate conclusion.
Key takeaways
- Actual rights, use and source determine royalty classification.
- The current domestic royalty category is 15% for payments within scope.
- Know-how transfer differs from expertise applied to an independent service.
- A non-royalty result does not automatically mean no withholding.
- Payment frequency and invoice labels do not replace the rights analysis.
Sources
- Official Arabic Income Tax Implementing RegulationsArticles 5 and 63, pp. 5-6 and 34-36: source, current categories, gross base and reporting. Read with actual contract and recipient facts.
- ZATCA General Withholding Tax GuidelineSecond version May 2026, sections 5.1-5.2, pp. 33–36: rights, know-how and classification examples; treaty conditions p. 29.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.