In brief
Group ownership does not establish one WHT rate or exemption. Classify the actual service/right/premium/distribution, source and settlement; recharges, agents and treaty recipients require their facts supported.
Group payments require the actual income category and Saudi source assessed. Common ownership neither creates a universal exemption nor makes every recharge a 15% service. Current Arabic regulations distinguish technical services, management, royalties, insurance, dividends and other payments; genuine agency/foreign-source facts can also matter.
Establish the payer, recipient and actual settlement
Income Tax Law Articles 5 and 68 and Regulations Articles 5 and 63 frame the analysis. A Saudi resident or Saudi permanent establishment paying a relevant non-resident can have a withholding obligation even if the group files consolidated accounts or the Saudi entity pays Zakat.
ZATCA’s General Withholding Tax Guideline, second version May 2026, pp. 15–17, includes settlements, offsets and book arrangements with the effect of discharging a liability. Group treasury netting is not automatically outside scope because no separate supplier wire is made.
Distinguish a settlement from a mere unpaid accrual and identify the actual recipient. A treasury company receiving cash as settlement agent is not automatically the beneficial supplier of every service or the person entitled to a treaty claim.
Related-company service source is not limited to Saudi performance
Guideline section 7, p. 39, explains the source rule for relevant amounts paid by a resident company to its head office or a related company. Such services can fall within source regardless of where performed.
Technical/consultancy services also have the specific Regulations Article 5(3) source rule. Therefore, an overseas shared-service centre’s location alone does not remove withholding for a Saudi recipient.
Dariba analysis: a remote related-party service should not be treated as non-taxable merely by copying the outcome of an unrelated foreign-source promotion example. Establish relationship and the particular source category before comparing rate outcomes.
Apply the actual current payment category
Article 63(1), p. 34, and guideline section 3, p. 28, specify technical/consultancy services at 5%, management fees at 20%, royalties at 15%, and the relevant dividend, rent, loan-return and insurance categories at 5%, with residual in-scope payments at 15%.
The current table does not justify a blanket 15% rule for genuine technical/consultancy payments solely because the recipient is related. Nor does it permit every headquarters cost to be labelled technical and charged at 5%.
Examine the actual contract and deliverables. Transfer-pricing support for an arm’s-length charge can help explain value but does not itself establish the withholding category, source or treaty entitlement. VAT grouping is a different regime and does not eliminate these cross-border income-tax obligations.
Official head-office examples identify the real transaction
Example 1, p. 15, subjects foreign head-office technical services to a Saudi permanent establishment to withholding; any expense deduction is separately conditional. Corporate unity does not make that service payment irrelevant.
Example 5, p. 22, treats a Saudi branch’s properly allocated share of a global insurance premium at 5% on the stated facts, provided no separate head-office service amounts are included. A premium routed through head office is not automatically management consideration.
Example 8, p. 26, instead concerns funds sent to a foreign branch to pay rent for property used abroad. It distinguishes the actual foreign landlord/property source from a payment to the branch for services. This is not a universal exclusion for every amount called reimbursement.
Recharges require principal, agent and service facts
Identify who contracted for the underlying service, who receives it, whether the group entity acts as principal/agent and what it adds. A recharge at cost can still be service consideration. A markup does not by itself decide whether the income is technical, management or another category.
For a combined amount, preserve the underlying invoices, allocation basis, actual beneficiary and separate service fees. The insurance example’s pure-premium condition cannot support ignoring an additional administration/management service.
Dariba recommendation: agree the nature of each recurring recharge before year-end settlement. A late journal description often cannot reconstruct the rights, actual work or source facts needed to support the original tax conclusion.
Separate distributions, financing and intellectual-property rights
Regulations Article 63(6), p. 35, addresses dividends including relevant permanent-establishment profit transfers and distributions beyond paid-up capital on liquidation, subject to its specific provisions. A shareholder-related payment is not necessarily a service fee.
Actual management contracts, loan returns and royalty rights have their own definitions. Guideline sections 5.2 and 6, pp. 35–39, distinguish know-how/licence rights, expertise applied in services and management activities. A group policy label such as strategic support does not establish one category for everything.
Treaty relief requires the actual treaty, recipient/residence, relevant connection and procedure. Common ownership or a group residence certificate does not automatically give every company the same treaty result.
Quantify the consequence without assuming every rate applies
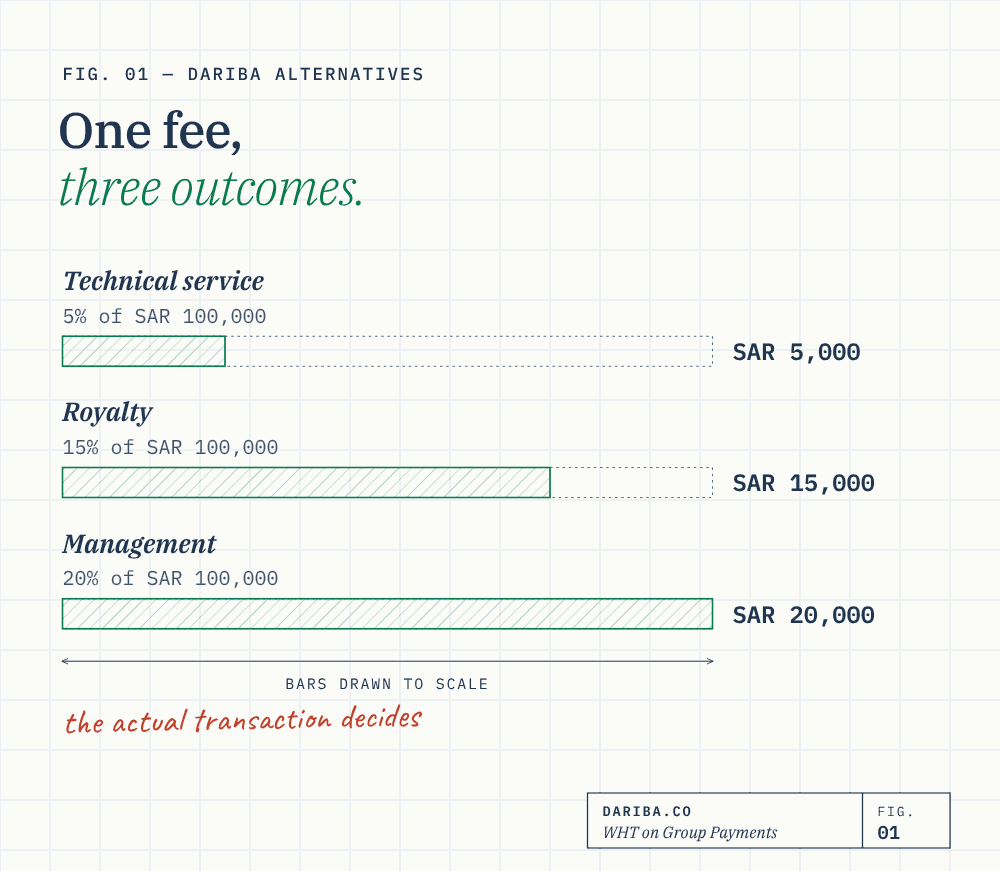
Dariba original alternatives: a SAR 100,000 gross fee gives SAR 5,000 WHT if it is an in-scope technical service, SAR 20,000 if it is actual management consideration, or SAR 15,000 if it is an actual royalty. These are separate assumed classifications, not options the group may choose freely.
If the supplier must receive an agreed net amount, the contract can require a supported gross-up. The payer cannot assume an intercompany invoice’s face amount already reflects who bears tax. Nor does paying withholding automatically make the full recharge deductible for income tax or Zakat.
Keep any pricing adjustment, withholding amount and supplier balance reconciled. A transfer-pricing adjustment needs its actual payment/settlement and category analysed; there is no universal withholding result for every year-end true-up from its name alone.
Reconcile group settlements with monthly and annual reporting
The compliance guide explains the monthly statement/payment, annual 120-day rule and partnership exception, certificates and ten-year minimum retention with extensions for unresolved matters.
Reconcile treasury netting and intercompany accounts to the actual payment population, preserving no-withholding reasons as well as taxable entries. An annual group reconciliation does not itself defer the monthly obligations created by an earlier settlement.
Dariba recommends a transaction-level file linking contracts, source/category, allocation, treaty evidence, settlement, tax and recipient certificate. That supports an advisory conclusion about the actual arrangement instead of applying one rate to all group-company payments.
Key takeaways
- Identify the actual payer, recipient and settlement instead of the treasury bank alone.
- Relevant related-company services can have Saudi source despite foreign performance.
- Technical 5%, management 20% and royalty 15% are different actual categories.
- Pure-premium and foreign-property examples do not exempt every recharge.
- Cost, markup and transfer-pricing support do not alone decide WHT treatment.
- Reconcile group netting to monthly reporting, treaty evidence and recipient certificates.
Sources
- Official Arabic Income Tax Implementing RegulationsArticles 5 and 63, pp. 5–6 and 34-36: actual related/source categories, rates, premiums, distributions and reporting.
- ZATCA General Withholding Tax guidelineSecond version May 2026, Examples 1, 5 and 8, p. 15, 22 and 26; sections 5-7, pp. 30–39: actual categories, settlement and rights.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.