In brief
Classify actual management responsibilities, group recharges, gross and net fees, treaty conditions and reporting using current official Saudi sources.
The 20% management-fee category applies to actual management consideration within Saudi WHT scope. It does not apply to every headquarters invoice, nor can a management contract obtain the technical-service rate merely by changing its description. Identify the responsibilities, work and consideration before calculating the withholding.
Establish the actual management service
Current Arabic Income Tax Implementing Regulations Article 63(2), p. 34, defines management fees as amounts paid under management-service contracts, with hotel and ship management as examples. Article 63(1) sets the current domestic rate at 20% for the category.
ZATCA’s General Withholding Tax Guideline, second version May 2026, section 6(B), pp. 38–39, describes actual services adding commercial value under an agreement specifying work, fees and responsibilities. It lists facility management and relevant IT/HR, housing, property, ship and hotel management examples.
These are factual management arrangements. A supplier’s job title, the invoice word management or an allocation from a parent company’s budget is insufficient to classify every amount without examining what was actually supplied.
Determine Saudi source and the actual recipient
Law Article 5 and Regulations Article 5 govern source, while Law Article 68 and Regulations Article 63 govern the withholding mechanism. Relevant management consideration paid by a Saudi resident to a non-resident is analysed within those provisions, including the related-company source rule where applicable.
Foreign performance or offshore payment does not automatically remove Saudi-source management consideration. The actual recipient and any connection with its Saudi permanent establishment must also be established.
The main WHT guide explains payer/residence/source. Do not infer an exemption from the Saudi payer’s Zakat status, or assume that an unrelated Saudi branch settles the treatment of every foreign management invoice.
Distinguish management from technical advice
Article 63(3) separately defines technical/consultancy services, using the current 5% category. A supplier can apply expertise to deliver an engineering study without assuming responsibility for managing the customer’s business. Conversely, actual operational management can involve technical expertise without becoming a separate technical-service contract.
Dariba original comparison: an independent engineering report and an agreement to manage a hotel’s operations are materially different deliverables. Their categories follow the actual work/responsibilities, not the group’s preferred tax outcome.
For a mixed contract, establish whether independent services genuinely exist and support their consideration. Splitting one integrated management responsibility into a small management line and a large technical-support line does not by itself establish the lower rate.
A group recharge is not automatically a management fee
Guideline Example 5, p. 22, treats a Saudi branch’s allocated share of a global insurance premium at 5% on its stated pure-premium facts, excluding separate head-office services. Example 1, p. 15, instead addresses actual head-office technical services.
Those examples show why the underlying transaction matters. A recharge at cost can still be taxable consideration; equally, the group entity handling payment does not automatically transform an actual premium into a management service.
Retain the original contract/invoice, principal/agent capacity, allocation and any added services. Transfer-pricing evidence can support the charge but does not itself classify it for WHT or certify its income-tax/Zakat deductibility.
Calculate tax using the full relevant gross consideration
Article 63(8) applies the rate to the full relevant amount, without deducting the recipient’s expenses. Dariba original illustration: SAR 100,000 gross actual management consideration, within scope at 20% and without treaty/specific relief, produces SAR 20,000 WHT and SAR 80,000 payable to the supplier.
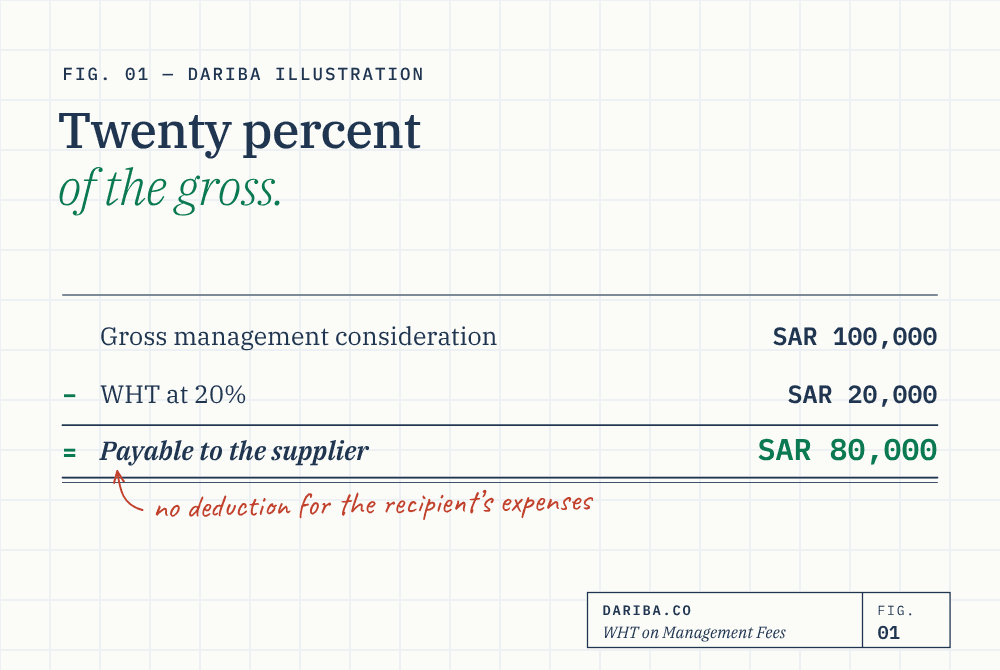
The supplier’s payroll, travel costs or low profit margin do not automatically reduce this gross withholding base. An amount properly paid as agent for a distinct underlying transaction requires its actual facts assessed; it is not excluded simply by putting reimbursement on the invoice.
This calculation does not determine whether the contract is management, whether a treaty changes the result, or whether the payer can deduct the expense under another tax regime.
Read net-fee and tax-bearing clauses before settlement
Dariba original assumptions: the supplier must receive SAR 80,000 net for a fully in-scope management service, and the payer bears WHT at 20%. The gross amount is SAR 100,000, with SAR 20,000 tax. Adding 20% to the promised net amount would not produce that same net receipt after withholding.
If a contract instead fixes a gross amount from which tax may be withheld, the supplier’s receipt differs. Establish the actual contractual terms before informing the supplier of the net payment or recording a gross-up.
Treat a tax-bearing clause as a commercial fact affecting the calculation, not a power to select a different statutory rate. Payment by offset or group netting also requires the actual settlement event identified.
Keep treaties, directors and employment separate
An applicable treaty may change the domestic outcome if the actual treaty article, recipient/residence facts, permanent-establishment connection and procedure support relief. No universal treaty rate for every management fee is established by the domestic table.
The guideline section 6(C), p. 39, separately describes directors’ fees. Employment remuneration and directors’ payments require their actual legal status considered; the 20% management category should not be applied indiscriminately to every person involved in corporate governance.
Likewise, VAT or reverse charge on received services is separate from withholding. A service’s VAT classification does not certify its WHT category, and WHT paid is not an input-VAT credit.
Preserve the contract-to-return analysis
Keep the service scope, responsibilities, actual deliverables, recipient/source, supported allocation, gross/net terms, treaty basis, settlement, statement/payment and beneficiary certificate. Explain why management rather than technical services, royalty, premium or another category applies.
The compliance guide addresses monthly and annual reporting and records. The group-payments guide connects these questions to recurring head-office charges.
Dariba recommends reviewing the contract before agreeing a net fee. The decision should be supported by what the supplier actually manages, rather than by its name, the group’s accounting label or the size of the tax difference.
Key takeaways
- Actual management services within scope use the current 20% domestic category.
- Head-office invoices and at-cost recharges require their underlying transactions assessed.
- Technical advice and operational management can have different responsibilities.
- Use the full relevant gross fee and the actual contractual tax-bearing clause.
- Treaties, directors and employment require their own factual and legal analysis.
Sources
- Official Arabic Income Tax Implementing RegulationsArticles 5 and 63, pp. 5-6 and 34-36: source, current categories, gross base and reporting. Read with actual contract and recipient facts.
- ZATCA General Withholding Tax GuidelineSecond version May 2026, section 6(B)-(C), pp. 38–39; Examples 1 and 5, p. 15 and 22; rates/reporting pp. 28–31.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.