In brief
Article 49(2) combines a six-month service window with cumulative purpose, consumption and expenditure conditions. An invoice or payment date alone does not establish eligibility.
The useful starting point is the service received and its position at the effective registration date. A payment made before registration is not automatically lost, but neither does a supplier invoice dated within six months automatically establish recovery.
Article 49(2) creates a specific route for services supplied before registration. It combines a six-month supply window with conditions about qualifying use, onward supply or consumption, and restricted expenditure. The review should establish each condition before calculating a claim.
Establish the effective registration date and supply window
Use the effective date shown in the registration position, rather than the application, certificate-printing or first-return submission date. If ZATCA determines a different effective date, revisit the analysis against that date. A business cannot choose a later date simply to bring expenditure into the six-month window.
For an effective registration date of 1 October 2026, the ordinary six-month lookback starts on 1 April 2026. This is Dariba’s timeline illustration, not a ZATCA example. It identifies the supply window; it does not determine which services remain eligible or the return in which a later claim can lawfully be made.
Invoice date, payment date and the date a service is supplied can differ. Review the contract, service period, invoices and deliverables together. Paying an old invoice after registration does not, by itself, turn an older service into one supplied within the permitted window. Equally, receiving the invoice late is not conclusive proof that the underlying service was supplied late.
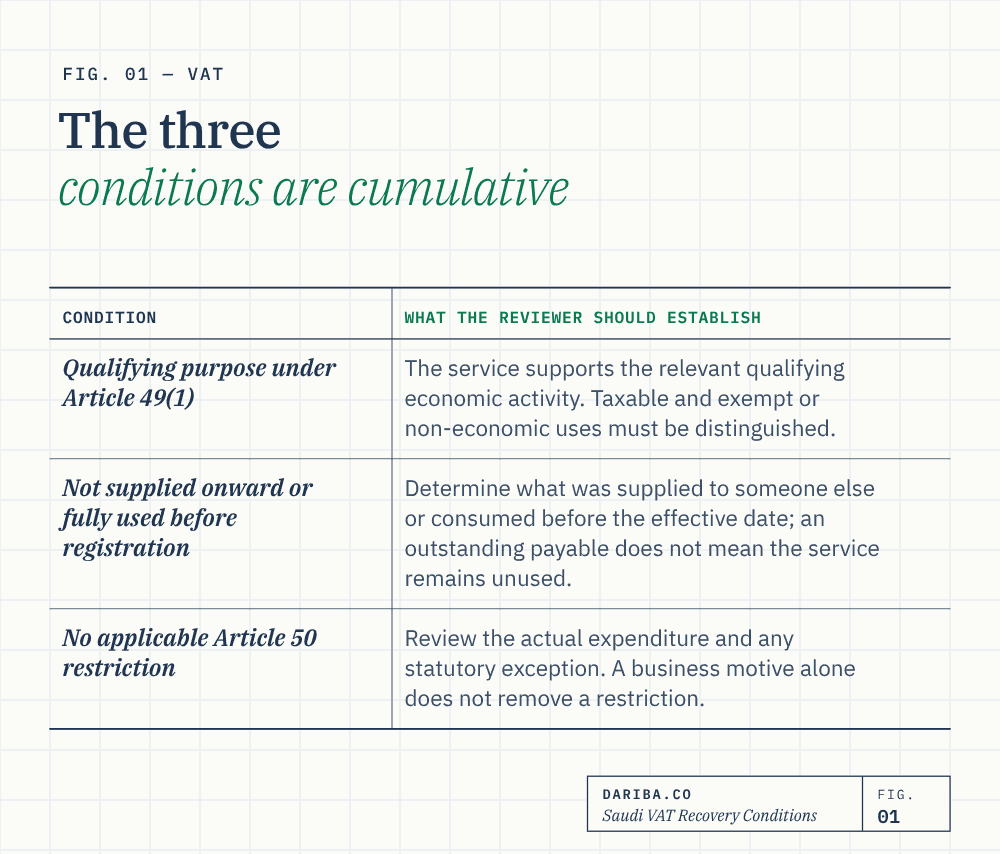
The three conditions are cumulative
The Input Tax Deduction Guideline, third version, May 2026, section 11.1, pages 45-46 explains Article 49’s pre-registration routes. For services within the window, test:
| Condition | What the reviewer should establish |
|---|---|
| Qualifying purpose under Article 49(1) | The service supports the relevant qualifying economic activity. Taxable and exempt or non-economic uses must be distinguished. |
| Not supplied onward or fully used before registration | Determine what was supplied to someone else or consumed before the effective date; an outstanding payable does not mean the service remains unused. |
| No applicable Article 50 restriction | Review the actual expenditure and any statutory exception. A business motive alone does not remove a restriction. |
A service used partly for exempt activities does not become fully deductible because registration has occurred. Apply the relevant allocation, alongside the other entitlement conditions. See the Article 49 entitlement guide and blocked expenditure and exceptions.
Completion, consumption and capitalisation are different questions
The difficult judgement is often whether a service has already been used in full. A supplier marking a project complete is relevant evidence, but the analysis concerns the service and how the recipient has used it. A continuing commercial benefit from an old expense is not, by itself, proof that the service was unconsumed at registration.
An expired annual support contract, a completed event and a continuing licence should therefore be examined on their own terms. Do not treat every completed report as automatically disqualified, or every report supporting future trading as automatically recoverable. Identify the deliverable, rights received, use before registration and remaining use, then document the conclusion. Where the facts do not resolve the consumption condition, obtain clarification before claiming.
Dariba’s analysis. Accounting capitalisation does not determine whether the supply is goods or services for this purpose. ZATCA’s Capital Assets Guideline, version 2, May 2026, section 7.2, pages 43-44 expressly applies the six-month condition to intangible capital assets treated as services. Putting software rights on the fixed-asset register does not, on its own, move them into the tangible-goods route with no equivalent six-month condition.
Classify the actual supply, including any bundled hardware, licences and support. Do not assume that every item described commercially as software has identical VAT treatment.
Dariba illustration: screening services at registration
Assume a business registers effectively on 1 October 2026, makes qualifying taxable supplies and holds evidence of correctly charged Saudi VAT. These are Dariba’s assumed facts, not an official worked example.
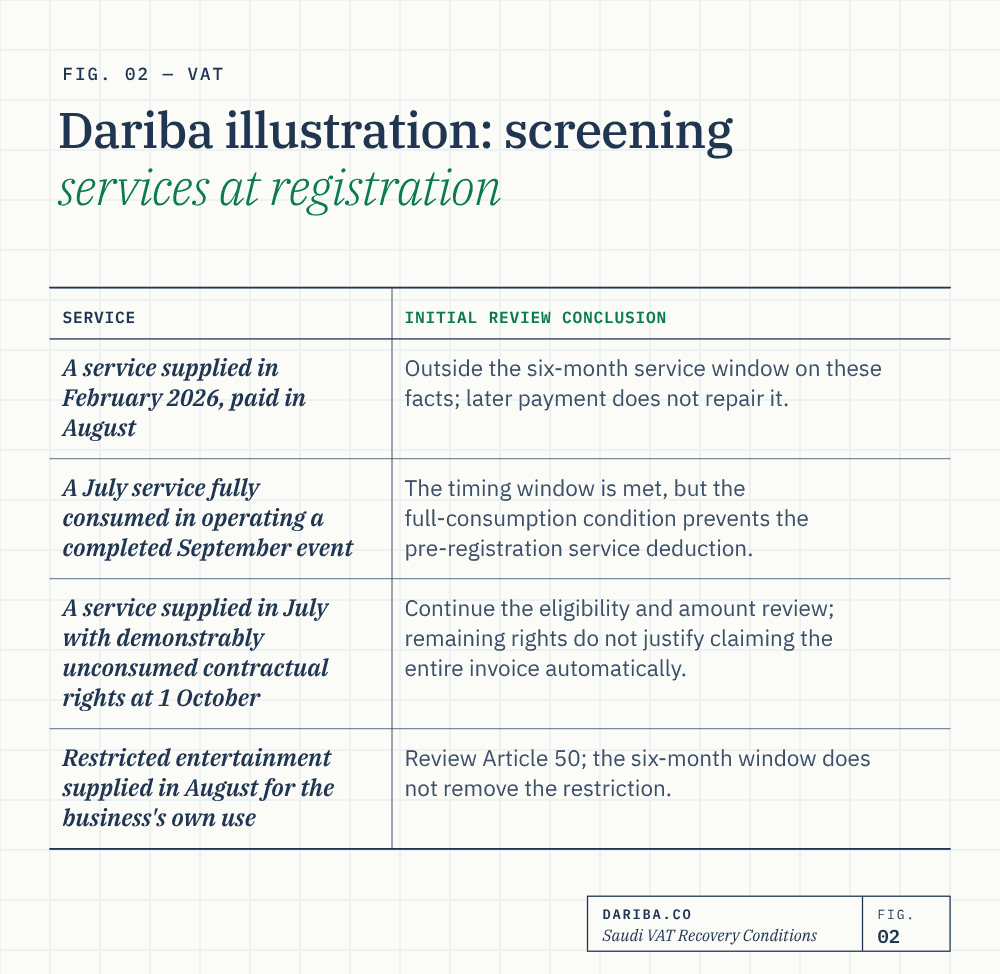
| Service | Initial review conclusion |
|---|---|
| A service supplied in February 2026, paid in August | Outside the six-month service window on these facts; later payment does not repair it. |
| A July service fully consumed in operating a completed September event | The timing window is met, but the full-consumption condition prevents the pre-registration service deduction. |
| A service supplied in July with demonstrably unconsumed contractual rights at 1 October | Continue the eligibility and amount review; remaining rights do not justify claiming the entire invoice automatically. |
| Restricted entertainment supplied in August for the business’s own use | Review Article 50; the six-month window does not remove the restriction. |
For a service spanning registration, a time-based split may help explain use where the benefit is genuinely uniform. Article 49(2) and section 11.1 do not prescribe a universal monthly formula. Support any allocation from the contract and actual use; do not present elapsed months as a ZATCA-approved method for every service.
The guideline section sets out conditions rather than a worked service-consumption example. That is why the scenarios above are labelled as Dariba’s own analysis.
Evidence: correct the invoice and establish the entitlement
Article 49(7) governs proof of the input tax paid or payable. Obtain the correct tax invoice and retain the agreement, service dates, recipient identity and evidence of intended and actual use. Where information is missing, seek correction rather than assume a payment reference is enough.
Official example and its limit. In Example 22, section 8.1 of the Input Tax Deduction Guideline, pages 35-36, ZATCA considers an incomplete invoice and other evidence under its discretion. This supports an evidence review; it does not waive the six-month or consumption conditions, and it does not let a taxpayer approve its own substitute documentation.
Distinguish an invoice defect from a charge that was not valid Saudi VAT in the first place. Foreign VAT is not claimed through the Saudi VAT return merely because the expenditure supports the Saudi business.
Claim timing is separate from the six-month lookback
Prepare the pre-registration schedule when opening the first return. For capital assets, section 7.3 of the Capital Assets Guideline expressly describes deduction in the first tax period containing the effective registration date. That statement is relevant to intangible capital assets as well as the tangible assets discussed in that section.
For other services, read Article 49(2) with paragraph 8’s later-deduction conditions and the applicable return/correction rules. Do not invent an automatic forfeiture merely because an otherwise eligible item was omitted from the first return; equally, do not assume every late claim can be inserted in any later return. Establish the lawful period, evidence and continuing eligibility. See the input-tax time-limit guide.
The six-month rule asks when the service was supplied relative to registration. The later-claim rules ask when an eligible deduction can be taken. Keeping those questions separate prevents a missed invoice being confused with a service that never qualified.
The registration review file
We recommend one schedule recording the effective date, service description, supply dates, original VAT, qualifying use, pre-registration consumption, Article 50 review, evidence and proposed claim period. Where a decision depends on an unresolved fact, record that fact and the work needed to resolve it instead of assigning a recovery percentage prematurely.
Primary source: VAT Implementing Regulations, Article 49(1)-(2), (7)-(8), Arabic tenth edition, April 2025, pp. 48-49.
Key takeaways
- Use the effective registration date and actual service supply, rather than assume the application, invoice or payment date controls.
- Qualifying purpose, no prior onward supply or full consumption, and no applicable Article 50 restriction must all be established.
- Capitalised intangible services remain subject to the service conditions; an accounting asset label does not remove the six-month test.
- Completion of a deliverable and consumption of a service require a factual analysis; future benefit alone does not prove eligibility.
- The six-month lookback and later-claim rules answer different questions; omission from the first return does not itself settle forfeiture.
- Invoice correction and permitted alternative evidence do not waive the underlying entitlement conditions.
Sources
- ZATCA - VAT Implementing Regulations, Arabic tenth edition, April 2025Article 49(2), read with (1), (7)-(8); controlling Arabic text.
- ZATCA - Input Tax Deduction Guideline, third version, May 2026Section 11.1, pp45-46; section 8.1, Example 22, pp35-36.
- ZATCA - Capital Assets Guideline, version 2, May 2026Sections 7.2-7.3, pp43-45: intangible services and first-period capital-asset deduction.
General information only. The treatment depends on the facts, applicable period and controlling Arabic legislation. Dariba analysis and original illustrations are distinguished from official examples. Seek advice or clarification for an unresolved specific arrangement.