In brief
Phase 1 required compliant electronic generation and preservation from 4 December 2021. Its five-field simplified QR requirement and original controls must be distinguished from later integration features.
What Phase 1 Required from 4 December 2021
Phase 1 required persons subject to Saudi e-invoicing to generate and retain invoices and associated notes through a compliant electronic solution. It replaced handwritten invoices and invoices created using ordinary text-editing or spreadsheet software. Scanning a paper invoice does not make it an electronic invoice within this framework.
The obligation remains relevant to historic records and to taxpayers awaiting their integration date. A later upgrade does not repair an inaccessible archive or establish that the earlier system complied. Equally, a historical review should not apply a Phase 2 field or connection requirement before its applicable date.
Establish Person and Transaction Scope
E-Invoicing Regulation Article 3 covers resident taxable persons and parties issuing on their behalf, while excluding non-resident taxable persons. Implementation Resolution First separately identifies the transactions for which e-invoices and notes are required.
Standard-rated and zero-rated taxable supplies, relevant exports, nominal supplies and taxable advances fall within the stated invoicing scope. First 7 excludes fully exempt supplies and related advances, reverse-charge supplies and goods imports. A mixed business must apply those distinctions transaction by transaction. Zero-rating should not be described as exemption.
The existence of a VAT registration does not require an e-invoice for every movement of money. Establish whether the receipt is consideration for a supply, whether an invoice is required and whether the transaction falls within the Resolution. The overview provides the broader scope map.
Use a Compliant Generation Solution
Annex One’s Phase 1 table did not prescribe XML as the invoice format. That flexibility concerned format, not permission to use a document editor without the required generation and security controls.
The solution had to generate the relevant invoice and note types with the applicable fields, timestamp the documents, support archival export and satisfy the relevant access and tampering controls. Detailed Guideline 5.7 also requires the human-readable invoice to be in Arabic; another language may appear alongside it.
Dariba illustration: A consultancy has complete seller, customer and VAT details in an editable spreadsheet. It saves and emails each invoice but permits staff to overwrite the records. Accurate VAT arithmetic does not establish compliant electronic generation or preservation. The business should identify the system defects and available original evidence; it should not silently recreate the archive as though the replacement files were the originals. This is our illustration, not an official ZATCA worked example or an assumed audit finding.
Check Invoice Fields Against the Correct Column
VAT Implementing Regulations Article 53 sets the invoice requirements, supplemented by Annex Two’s field-by-field obligations and enforcement dates. A condensed table is a review aid; the applicable conditional fields still need to be tested against the transaction.
| Review area | Phase 1 treatment |
|---|---|
| Seller identity and VAT information | Include the required seller data for the relevant invoice type |
| Invoice number, issue date and taxable supply details | Include the applicable reference, dates, descriptions and amounts |
| Buyer details on a standard invoice | Include required name and address; buyer VAT registration is conditional under Annex Two |
| Simplified invoice content | Apply Article 53 and its transaction-specific conditions |
| Tax treatment where the standard rate is not charged | Include the applicable explanation; examine the legal basis for zero-rating or other treatment |
| Additional integration data and structured codes | Use the individual enforcement column; do not treat the full Phase 2 field set as retrospectively mandatory |
Annex Two’s standard-invoice special-tax-treatment entry requires a narration where its condition applies. That is not the same proposition as saying that every Phase 1 invoice showing no VAT had to contain every later XML reason code. Fully exempt supplies are separately excluded by Resolution First 7.
For simplified invoices, the low-value option concerns supplies below SAR 1,000, subject to Article 53’s conditions and exclusions. It does not exempt a supplier issuing fewer than 1,000 invoices per year. A correctly issued simplified invoice is also an expressly recognised alternative evidence category under Article 49(7); it should not be dismissed as incapable of supporting deduction in every case.
The Phase 1 QR Code Has Five Basic Fields
Annex One specifies five items for simplified invoices and their associated notes:
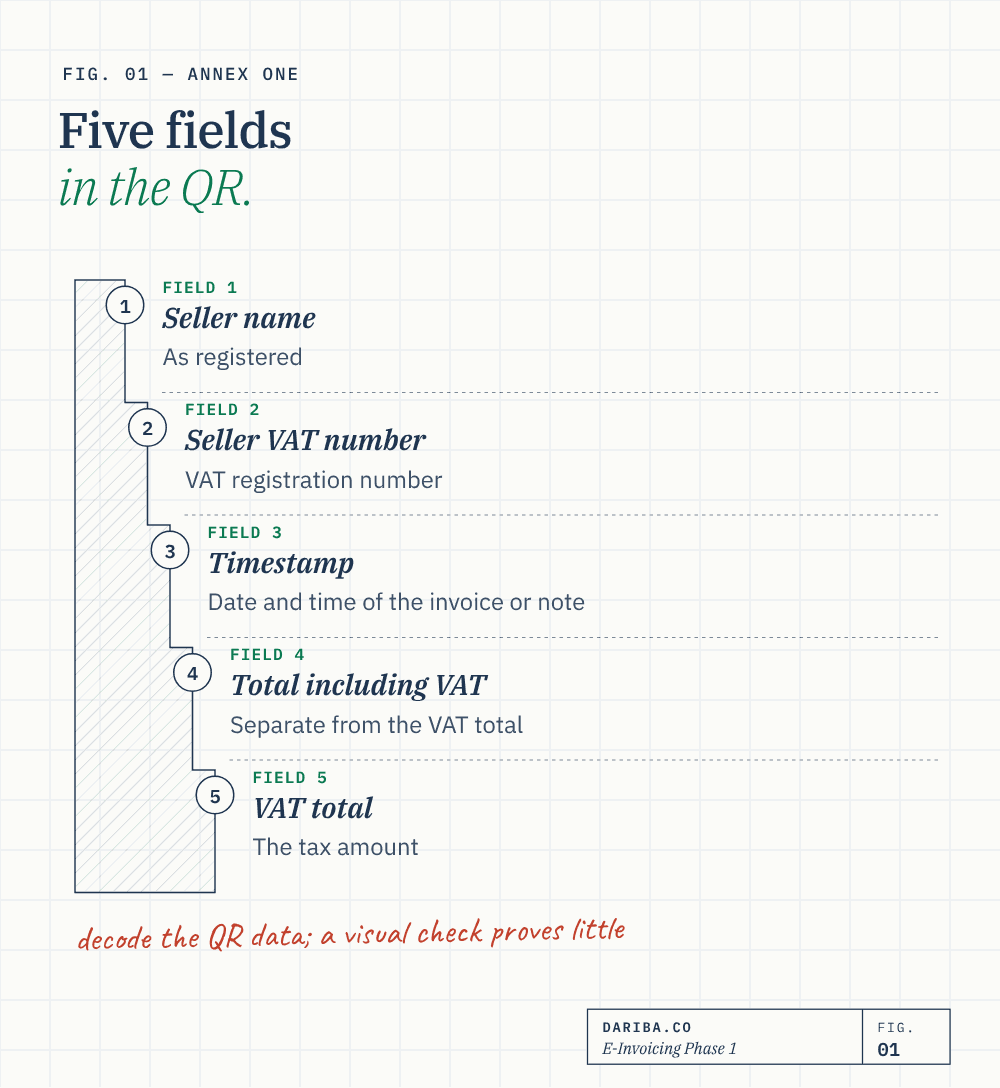
- Seller name.
- Seller VAT registration number.
- Invoice or note timestamp, including date and time.
- Total amount including VAT.
- VAT total.
The total including VAT and the VAT total are separate fields. A QR image that encodes only four items does not satisfy that list. The generation-stage QR requirement was for simplified documents; the additional cryptographic fields and broader Phase 2 QR requirements follow the integration timetable.
A QR code that opens a website or contains a free-text invoice number is not proof that the prescribed content is encoded correctly. Our practical recommendation is to decode representative original QR data and compare it with the corresponding retained invoice, rather than relying on a visual check of the square itself.
Prohibited Functions and Phase Distinctions
The controlling review is Annex One’s prohibition table, read with Detailed Guideline 5.6. Its Phase 1 entries address uncontrolled access, specified invoice/log tampering and multiple invoice sequences. The solution is assessed for enabling the prohibited capability; proof that a user actually deleted an invoice is not the only relevant question.
| Phase 1 control area | What to establish |
|---|---|
| Access | Unique user authentication, no anonymous access or operation with factory/default passwords, and user session management |
| Issued invoices and notes | Protection from alteration or deletion; use the applicable correction-note procedure |
| Activity logs | Protection from modification/deletion and the prohibited non-sequential generation capabilities |
| Accuracy and numbering | Accurate generated timestamps and no invoice-counter reset capability |
| Invoice sequences | No prohibited multiple sequences from the relevant solution unit |
The annex places export of stamping keys and software time-change capabilities in the Phase 2 column. It separately prohibits generated inaccurate timestamps in the Phase 1 column. Distinguishing those entries matters: a historical reviewer should not merge a later software capability restriction with the earlier requirement for accurate invoice information.
The Phase 1 counter-reset prohibition also should not be confused with a claim that every Phase 2 UUID, XML hash field and cryptographic-stamp mechanism was already mandatory in December 2021. Check each positive requirement and enforcement date independently.
Keep Records Accessible After Migration
Resolution Fifth and VAT Implementing Regulations Article 66 govern retention. The ordinary minimum is six years from the end of the relevant tax period. Capital-asset records follow the longer adjustment-period-plus-five-years rule. Additional applicable record requirements must also be considered.
Store the original electronic records and associated evidence in an accessible, protected archive. Article 66 addresses access in the Kingdom through the relevant terminal or connection, along with electronic-record conditions. The Detailed Guideline permits cloud arrangements subject to those VAT requirements and other applicable Saudi rules. An overseas cloud subscription alone does not establish compliance.
When replacing an ERP, demonstrate that historic invoices, notes and logs can still be retrieved and understood. Dariba recommends testing a sample retrieval after migration and retaining the mapping between the old and new references. That recommendation supports the legal retention duty; it is not a new statutory retention period.
Review Historic Gaps Without Assuming Waiver Relief
Identify the affected dates, document types, system capability and records before deciding what correction is required. Preserve originals and involve the vendor where technical changes are needed. Do not backdate replacements or silently alter issued invoices.
ZATCA’s current Arabic penalty-classification guide distinguishes categories, warning stages and repetition intervals. Current initiative announcements must be read separately. The 29 June 2026 extension runs to 31 December 2026 but expressly excludes VAT Law Article 45 fines. The earlier assertion that an open waiver automatically covers historical e-invoicing failures should not be relied upon. See the penalties guide and current initiative analysis.
Move to Phase 2 When Your Date Applies
Phase 1 compliance does not remove an integration obligation. Check the actual ZATCA notice and all reference years in the relevant wave announcement. Earlier targeted businesses remain subject to their earlier dates; a later, lower threshold does not restart their timetable.
The Phase 2 guide addresses XML submissions, onboarding, standard clearance, simplified reporting and incident handling. Before moving, reconcile the finance classification with the vendor’s configuration and confirm that the Phase 1 archive will remain available after the switch.
Key takeaways
- The generation obligation began on 4 December 2021, without a prescribed XML format for Phase 1.
- The basic simplified-invoice QR code has five fields, including separate gross-total and VAT-total fields.
- Apply the mandatory and conditional invoice fields using their actual enforcement dates.
- Do not import Phase 2 stamping-key or software-time-change restrictions into the wrong historical period.
- Keep original records accessible after migration and apply Article 66 retention and access conditions.
- An open initiative does not establish blanket relief for historical e-invoicing failures.
Sources
- ZATCA E-Invoicing Regulation, controlling Arabic textArticle 3: persons subject to the regulation and non-resident exclusion.
- ZATCA e-invoicing implementation controls, current Arabic publicationFirst to Seventh; Annexes One and Two: scope, evidence, document routes, controls and individual enforcement dates. Arabic text prevails.
- ZATCA English translation of the e-invoicing implementation controlsReading aid for First 3 and 5–7, Second 3, Third to Seventh and the annex enforcement tables; distinguish Phase 1 and Phase 2.
- ZATCA Detailed Guideline for E-Invoicing, second edition, May 2023Sections 2.3, 2.8, 4–7 and 10: invoice types, portal, generation/integration and qualified official failure scenarios.
- ZATCA Detailed Technical Guideline for E-InvoicingSections 3.5, 4.1–4.3 and 6 and rejection/failure FAQs: architecture, credentials, responses, sequence and QR distinctions. Differing simplified rejection answers remain qualified.
- Saudi VAT Implementing Regulations, current Arabic compilationArticles 49(7), 53–54 and 66: alternative deduction evidence, current invoice conditions, correction notes and records; historical comparison tables are not treated as operative text.
- ZATCA Arabic guide to classification of general VAT violations, second edition, May 2024E-invoicing items 8–18: category-specific warning, repeat and escalation rules. Detailed schedules remain in the linked penalty guide.
- ZATCA Wave 25 announcement, 24 July 2026Revenue exceeding SAR 187,500 in any of 2022–2025; actual notification and integration by 1 February 2027; earlier duties preserved.
- ZATCA penalty-waiver announcement, 29 June 2026Current extension to 31 December 2026 expressly excludes VAT Law Article 45 fines.
- Ministerial Decision 1117, official publicationOperative clauses First to Seventh: extension, specified covered relief, return cut-off and payment/instalment conditions; not blanket e-invoicing relief.
General information based on the cited official instruments and guidance reviewed on 29 October 2026. Arabic legislation controls. Actual transactions, applicable dates and system facts determine the result. Conflicting simplified-rejection FAQ instructions and tentative outage timings remain qualified. This guide does not certify a software implementation or guarantee tax relief.