In brief
Buyer VAT registration alone is not a complete routing rule. Non-taxable companies, low-value exceptions, valid simplified evidence and fully exempt transactions require distinct treatment.
Standard and simplified tax invoices differ in their permitted use, information and electronic workflow. Buyer VAT registration matters, but it is not the entire classification test. A non-taxable legal person can require a standard invoice, a qualifying low-value business supply can permit a simplified invoice, and a correctly issued simplified invoice can support an otherwise eligible input VAT claim.
Compare the legal types before configuring the workflow
| Decision | Standard tax invoice | Simplified tax invoice |
|---|---|---|
| Ordinary customer/supply category | Covered taxable supplies to businesses/entities under Article 53(1), with special export rules | Domestic natural-person supplies outside the standard categories and qualifying low-value exception |
| Low-value business supply | Standard form may still be used | Test the exception for value less than SAR 1,000; do not use “up to SAR 1,000” |
| High-value domestic consumer supply | Value alone does not make standard form mandatory | Natural-person framework applies regardless of value, subject to special rules |
| Legislative content | Article 53(5), including conditional information | Article 53(8), with applicable additional requirements |
| Input-tax evidence | Correct document plus separate entitlement tests | Correctly issued permitted document is recognised by Article 49(7)(a), plus separate entitlement tests |
| Integration-phase process | Applicable clearance before sharing with the customer | Reporting within 24 hours of generation under the published resolution |
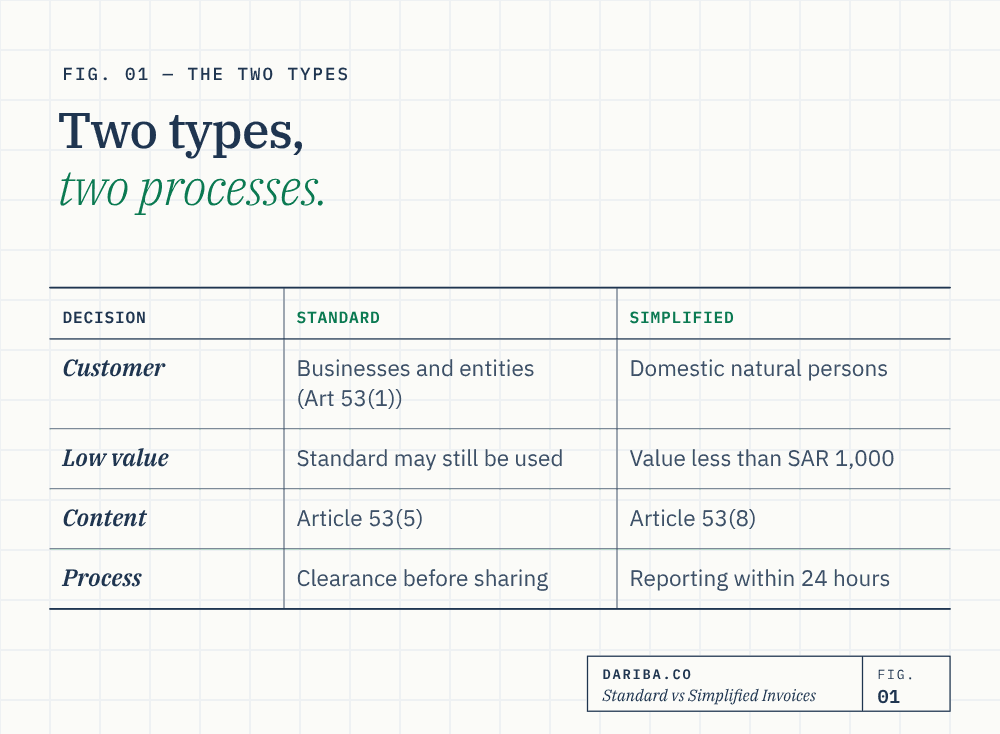
Sources: Arabic VAT Regulations, Articles 49(7) and 53, pp. 49 and 55–58; Tax Invoicing and Records Guideline, version 3, May 2026, detailed table and simplified rules, pages 13 and 23–24.
The comparison concerns the ordinary rules. Exports, deemed supplies, self-billing and qualified financial-service exceptions need their own tests; the table does not replace them.
Do not use “no VAT number” as the automatic consumer route
An unregistered company remains a legal person. It does not become a natural-person retail customer merely because it has no VAT registration number. Section 4.2.3, p. 19, includes alternative customer identification for standard invoices where the customer is not registered.
Conversely, a valid low-value exception should not be overridden by claiming that a simplified invoice necessarily destroys recovery. Article 49(7)(a) recognises a correctly issued simplified invoice. Actual recipient, use, restrictions, tax and evidence remain decisive. A company can adopt an internal preference for standard invoices, but its procurement preference is not the wording of the deduction law.
Dariba’s implementation recommendation. Capture customer legal status and the relevant transaction facts as well as registration data. Route special cases deliberately and retain the reason for classification. A single rule that asks only whether a number was entered can produce the wrong invoice for either a non-taxable company or a qualifying small business purchase.
Clearance and reporting apply when the taxpayer is in scope
The published e-invoicing implementation resolution distinguishes generation from the integration phase. For the applicable integration population, standard invoices and related notes must follow the clearance process before sharing with customers. Simplified invoices and related notes are reported within 24 hours of generation. The latter period should not be casually described as starting whenever the invoice is later emailed or handed over.
This is not a requirement to obtain clearance before physically dispatching every delivery: the legal tax point, invoice-issuance deadline and clearance-before-sharing requirement are different decisions. Taxpayer-specific integration obligations and current technical specifications must be checked for implementation.
Source: E-Invoicing Implementation Resolution, clauses First and Second, pp. 1–3. The linked English text is a translation; Arabic controls. This article is a workflow comparison, not a technical compliance certification.
ZATCA’s retail example illustrates presentation, not a recovery ban
Example 7, section 4.3.2 of the May 2026 invoicing guideline, p. 24, uses food products costing SAR 90 plus SAR 13.50 VAT, or SAR 103.50 inclusive with the permitted statement. It illustrates simplified-invoice presentation. It does not say that every business purchase documented in simplified form is non-deductible. Read Example 7.
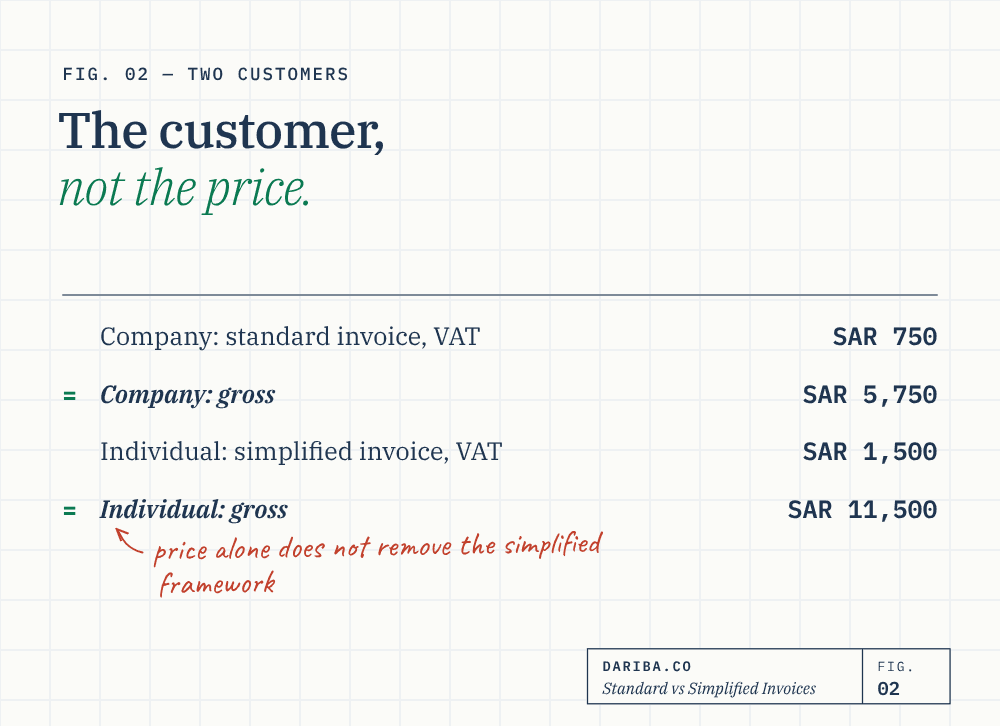
Dariba illustration. A supplier serves a non-taxable incorporated customer buying SAR 5,000 of ordinary taxable services and an unregistered private individual buying SAR 10,000 of domestic consumer services, both exclusive of 15% VAT. Assume no special transaction rules. The corporate supply ordinarily requires a standard invoice showing SAR 750 VAT and SAR 5,750 gross; the individual’s price alone does not remove the simplified framework, with SAR 1,500 VAT and SAR 11,500 gross. These original figures illustrate why value and VAT-number presence are not a complete decision tree. They are not additional facts in Example 7.
Fully exempt supplies are different from zero-rated supplies
Zero-rated supplies remain taxable supplies and fall within the relevant invoice/e-invoice requirements. Fully exempt supplies and their advances are excluded from the implementation resolution’s transaction scope. It is incorrect to describe exemption as just another taxable 0% category requiring an electronic tax invoice in every case.
Keep appropriate commercial and tax records for exempt transactions. Where a document covers mixed elements, identify the actual supplies and applicable electronic treatment rather than assuming the fully exempt exclusion resolves the whole document. The resolution also excludes imports of goods and reverse-charge supplies from its specified transaction scope; the necessary supporting customs/commercial records remain distinct.
Source: implementation resolution, clause First(5)–(7), pp. 1–2; invoicing guideline section 4.1.2, pages 13–15.
Notes, self-billing and system testing
Configure the applicable clearance/reporting process for each invoice and associated note type. Link the note to the invoice or invoices being adjusted. Test both workflows, including the actual correction path and evidence retained. No claim is made that all software defaults behave incorrectly or that one prescribed testing script fits every system.
Self-billing requires the separate approval, agreement and registration framework. Annex 1 field 1.2, p. 17, excludes self-billing from simplified invoices. An invoice flag does not replace those conditions. See self-billing and credit/debit-note analysis.
For detailed content, use standard invoice requirements and the simplified-invoice guide. Their purpose is to support the legal and operational decision; supplier invoicing, technical acceptance and customer deduction should each be assessed on their own conditions.
Key takeaways
- An unregistered incorporated customer does not automatically belong in the consumer route.
- Low-value exceptions and domestic natural-person rules qualify a simple B2B/B2C description.
- Correctly issued permitted simplified invoices can support eligible input claims; standard form alone does not guarantee recovery.
- Applicable integration clearance precedes customer sharing; simplified reporting is within 24 hours of generation.
- Fully exempt supplies are excluded from the resolution’s specified transaction scope; zero-rated supplies remain taxable.
- Notes and self-billing need their own legal and electronic conditions; no universal software or deadline certification is given.
Sources
- ZATCA - VAT Implementing Regulations, Arabic tenth edition, April 2025Controlling Arabic text: Article 49(7) p49; Article 53 pp55-58; Article 54 pp58-59; Article 40 pp37-39.
- ZATCA - Tax Invoicing and Records Guideline, version 3, May 2026Detailed types pp13-15,23-24; standard data pp16-20; timing pp25-27; notes and Examples 17-21 pp36-39; alternative evidence Example 22 p47.
- ZATCA - Published E-Invoicing Implementation Resolution, English translationClauses First/Second pp1-4; Annex 1 field1.2 p17. Current legislation page links this resolution; Arabic version prevails. No software/integration-date certification.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.