In brief
Apply amended Saudi transfer-pricing rules to CIT, mixed and Zakat taxpayers, identify controlled dealings and distinguish pricing, files and disclosure.
Start with the amended Saudi rules
Saudi transfer pricing concerns the conditions of dealings between related persons and persons under common control. The arm’s-length question is what comparable independent parties would have agreed in the relevant circumstances. A group invoice, contract or consolidated accounting policy does not independently establish that result.
Use the current Arabic Transfer Pricing Bylaws, issued under Board Decision 6-1-19 and amended by Decision 8-2-23 of 20 March 2023. ZATCA’s Arabic Transfer Pricing Guideline, third edition 2024, explains the amended framework. The linked English guideline remains the third edition November 2021; its older scope must not override the amendment.
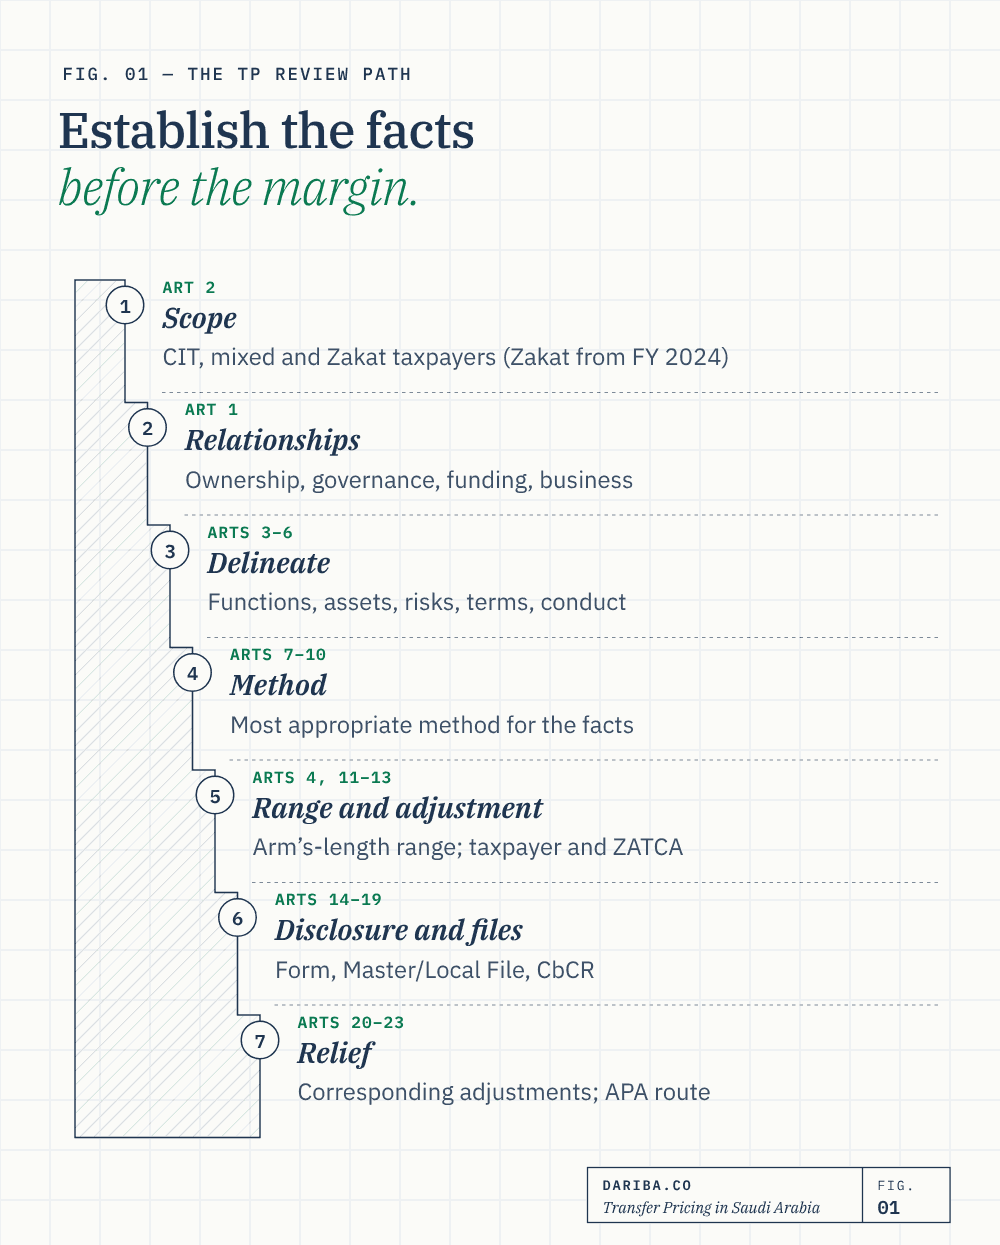
Scope includes CIT, mixed and Zakat taxpayers
Amended Article 2 addresses taxpayers under the Income Tax Law, Zakat regulations or both. Decision 8-2-23 applies the Zakat extension to financial years beginning on or after 1 January 2024. Mixed companies are treated as income-tax persons in full for TP purposes in the 2024 guideline, section 5.6.1; do not apply only a foreign-ownership percentage to the controlled-transaction review.
Domestic related-party dealings can be covered as well as international ones. Specific exceptions, including the defined consolidated Zakat-group treatment in Article 19(c), must be established on their actual conditions. “Both parties pay Zakat” is not a general exemption for all domestic transactions.
Identify relationships beyond the share register
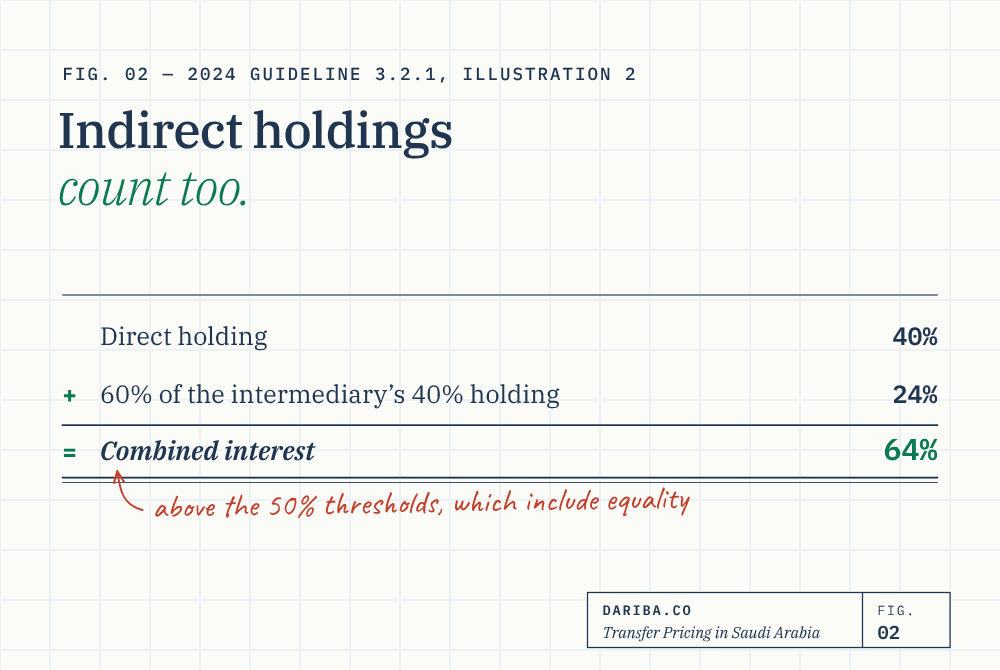
Article 1 addresses related persons and effective control through ownership, governance, funding and business arrangements. The test is broader than a parent owning more than half the shares. The relevant 50% thresholds include equality, while particular financing and guarantee tests have different denominators and specified financial-institution exclusions.
The 2024 guideline, section 3.2.1, Illustration 2, combines a direct 40% holding with 60% of an intermediary’s 40% holding, giving 64%. The related-person guide explains that official illustration and the financing examples. An accounting related-party list should be reviewed against the TP definitions rather than accepted as complete automatically.
Delineate the actual transaction before selecting a method
Articles 3–6 require the actual conditions and comparability analysis. Review functions performed, assets used, risks assumed, contractual terms, economic circumstances and business strategies. Actual conduct matters where a written description does not match the work and risk decisions in practice.
Dariba’s recommendation is to establish the transaction and parties before searching for a convenient margin. A distributor, manufacturer, service provider and financing entity may need different evidence even within one group. A profitable Saudi result does not independently prove arm’s-length pricing, and a loss does not automatically establish a violation.
Select and support the most appropriate method
Articles 7–10 address approved methods, the most appropriate method, other methods on the stated conditions and transactions that may be analysed together. CUP, resale price, cost plus, TNMM and profit split answer different economic questions. Their names do not supply a universal hierarchy divorced from comparability and available reliable data.
The methods guide addresses the underlying analysis. A benchmark should explain why the tested party, profit indicator, comparables, exclusions and adjustments fit the actual transaction. Selecting a range first and describing the business afterwards weakens the connection between evidence and conclusion.
Separate disclosure, files and country reporting
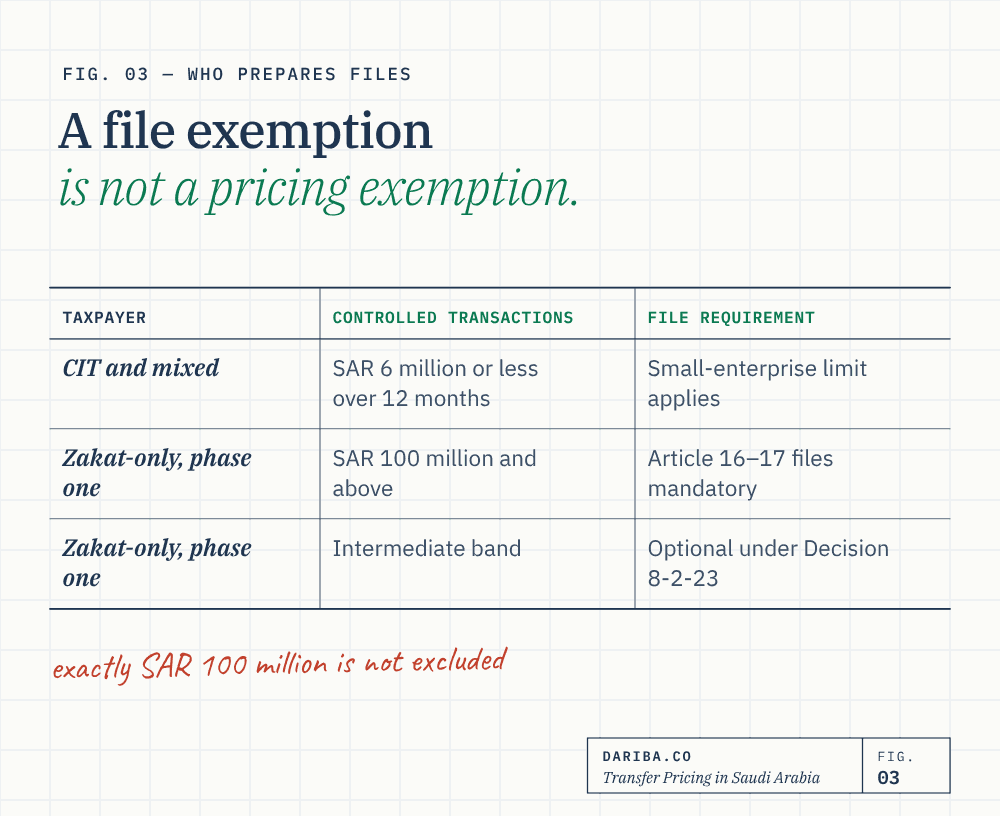
Articles 14–19 impose different obligations: the disclosure form and accountant certificate, supporting documentation, Master File, Local File and country-by-country reporting. The ordinary small-enterprise limit is SAR 6 million or less of arm’s-length controlled transactions over 12 months for CIT and mixed taxpayers. Zakat-only taxpayers have the separate phased application under Decision 8-2-23.
For the first phase, the decision makes SAR 100 million and above mandatory for the specified Article 16–17 file requirements, with the intermediate band optional; exactly SAR 100 million must not be excluded. The documentation guide explains the phases, financing-fund treatment and request periods. A file exemption is not a general exemption from pricing or disclosure.
An adjustment is not an automatic multi-tax calculation
Article 4 provides for the taxpayer’s appropriate adjustment and ZATCA’s relevant powers. Articles 11–13 address the arm’s-length range and adjustment framework; Articles 20–22 address corresponding adjustments. A foreign adjustment is not automatically accepted without the stated Saudi review and applicable treaty process.
CIT, Zakat, withholding, VAT and customs each require their own legal analysis of an adjustment. It is unsafe to assert that every increase in an arm’s-length expense automatically increases the withholding base by the same amount or creates an additional VAT charge. Establish the actual payment, supply, adjustment and applicable provision before measuring any secondary effect.
Put pricing evidence into the annual operating process
Maintain the relationship map, transaction inventory, agreements, actual conduct, functional analysis, pricing calculation, financial reconciliation and required filings. Revisit changes in functions, funding and risk rather than refreshing a benchmark mechanically. The disclosure guide explains the form and the limits of the accountant certificate.
Article 23 also provides an APA route subject to its conditions; applying is not the same as obtaining approval or immunity for every transaction. These guides support a provision-based review. They do not certify a group’s pricing, a particular comparable set or every international relief mechanism without the actual evidence and relevant instruments.
Key takeaways
- Use the amended Arabic Bylaws and 2024 Arabic guideline.
- Scope includes CIT, mixed and Zakat taxpayers under the stated dates.
- Domestic dealings and effective control can be relevant.
- Select a pricing method after establishing the actual transaction.
- Disclosure, files and country reporting have separate requirements.
- An adjustment does not automatically produce the same result under every tax.
Sources
- Saudi Transfer Pricing Bylaws, Arabic text amended by Decision 8-2-23Articles identified in the analysis. Amended Arabic scope, definitions, obligations and exceptions govern.
- ZATCA Board Decision 8-2-23, 20 March 2023Clauses 2–4: Zakat effective financial years, APA commencement and phased application of Articles 16–17, including financing funds.
- ZATCA Arabic Transfer Pricing Guideline, third edition 2024Relevant chapters 3 and 5, Annex 7 and exact control illustrations/examples. Tables checked against the original layout.
- ZATCA English Transfer Pricing Guideline, third edition November 2021Earlier explanatory reference only. It predates the 2023 Zakat amendments and does not override the amended Arabic text.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.