In brief
Apply the 5% premium category, Saudi-source rules and ZATCA group-policy Example 5 while distinguishing added services, actual recipients and treaty conditions.
The current 5% domestic insurance/reinsurance category applies to relevant Saudi-source premiums paid within withholding scope. A foreign policy, group recharge or broker payment requires the underlying risk, actual recipient and payment chain identified. The place where the policy is signed does not answer those questions.
Establish the premium and Saudi-source connection
Current Arabic Income Tax Implementing Regulations Article 5(2), p. 5, addresses insurance and reinsurance source. Its stated routes cover property insured in Saudi Arabia, the resident-insurer limb reproduced in the English official guidance, and insurance of activities or risks linked to an activity conducted in Saudi Arabia.
ZATCA’s General Withholding Tax Guideline, second version May 2026, section 2.2.2, p. 22, reproduces these three routes. Read the controlling Arabic provision and actual insurance roles together; do not replace the source analysis with the currency, invoice address or location of the insurer’s bank account.
Apply the current category after identifying the recipient
Article 63(1), p. 34, and guideline section 3, p. 28, give insurance/reinsurance premiums the 5% domestic category. Identify the actual non-resident recipient and relevant Saudi payer before applying it.
The same framework can concern a Saudi business’s direct premium or a resident insurer’s relevant reinsurance payment to a non-resident. A payment routed through a broker or group treasury company still requires the parties’ principal/agent capacities and the underlying income identified.
An intermediary’s separate fee is not automatically an insurance premium. Classification follows the actual consideration, not merely the bank account receiving a combined transfer.
Use ZATCA’s group-policy example with its condition intact
Official guideline Example 5, p. 22: a head office purchases a worldwide policy, fairly allocates each branch’s share and receives the Saudi branch’s premium share. ZATCA treats that share at 5% as an insurance premium, provided it contains no consideration for services performed by the head office for the branch.
This supports analysing the underlying premium even when payment is made to headquarters. It does not exempt all at-cost recharges or classify added management/technical work as premium.
Dariba recommends retaining the policy, original premium, allocation method, Saudi risk schedule and evidence separating any additional services. The example’s fair-allocation and no-extra-service facts are part of its usefulness, not optional details.
Support mixed-risk and mixed-service allocations
A global programme can combine several insured entities, territories and services. Determine which actual premium is Saudi-source and whether independent administrative, brokerage, management or technical services are also charged.
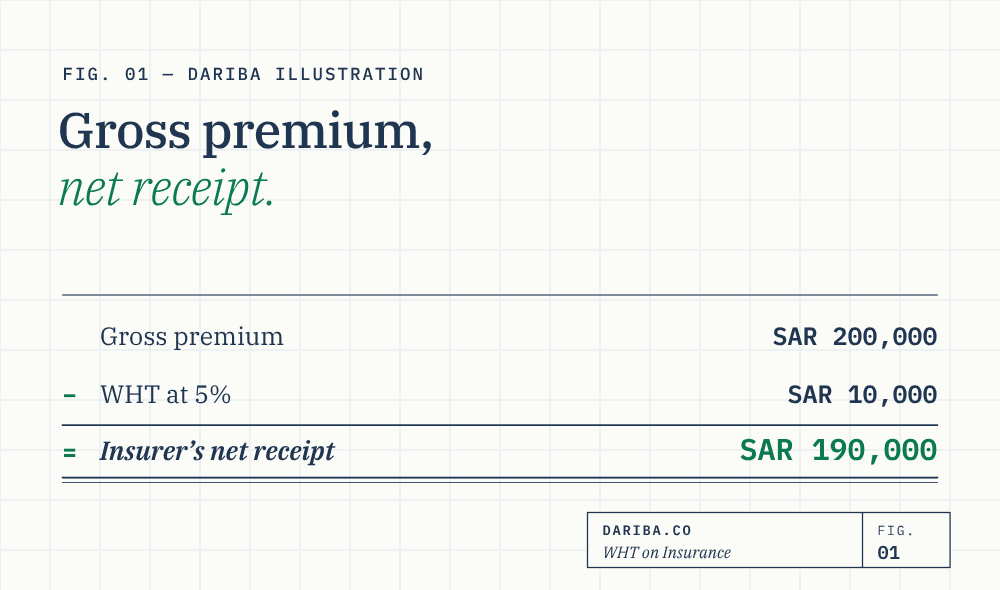
Dariba original assumptions: SAR 200,000 is a substantiated gross Saudi-source premium within the 5% category, without treaty/specific relief. WHT is SAR 10,000. The assumption does not establish that any particular global premium has the same Saudi allocation or that all other components are outside withholding.
Do not invent a universal allocation by turnover, headcount or days of cover. Use a basis supported by the actual insurance programme and review an uncertain source split before settlement.
Calculate gross withholding and the contractual net receipt
Article 63(8), p. 35, applies the rate to the full relevant consideration without deducting the recipient’s expenses. On the original SAR 200,000 gross-premium assumption, the insurer’s net receipt is SAR 190,000 after SAR 10,000 WHT.
If the payer instead promises SAR 190,000 net and bears 5% WHT without relief, the assumed gross amount is SAR 200,000. Simply adding 5% to a promised net premium would not produce the same net receipt after withholding.
Review the actual policy and tax-bearing clause. The insurer’s commissions, claims expense or underwriting loss do not automatically reduce a gross premium base, while a genuine independent service requires its own classification.
A Saudi establishment requires the actual income connection
Guideline Example 2, pp. 15–16, explains the income-tax route where the particular payment is connected with the non-resident’s Saudi permanent-establishment activity. Merely discovering that the group has some Saudi office does not settle every foreign premium.
Establish the contracting insurer, actual recipient and activity receiving the payment. Regulatory insurance licensing and income-tax establishment/source questions also have their respective legal tests.
No blanket WHT exemption is established by a Saudi licence, a local agent or the existence of an unrelated branch. Obtain the facts supporting the applicable route.
Keep treaty, VAT and deduction questions distinct
Guideline section 4, p. 29, recognises possible treaty changes subject to the actual agreement and conditions. Check the relevant recipient, residence, premium/income article, establishment connection and required relief mechanism; do not assume a standard premium exemption for every treaty country.
VAT on insurance or imported services requires its own classification. Paying WHT does not establish a VAT exemption, an input-VAT entitlement or full income-tax/Zakat deductibility.
Likewise, a captive or related insurer requires actual pricing and transaction evidence. Common ownership and an arm’s-length study do not alone establish source, treaty eligibility or the WHT category.
Reconcile policy evidence to the withholding records
Keep the policy/endorsements, insurer and intermediary roles, risk location/activity, premium allocation, added services, gross/net clause, treaty support, settlement, return/payment and recipient certificate. The compliance guide addresses timing and retention.
The group-payments guide connects Example 5 with other head-office charges. Non-cash settlements and group netting require the actual payment event considered.
Dariba recommends documenting the source and allocation before the premium is settled. A strong file explains why the amount is a qualifying premium and which facts support its Saudi portion, rather than relying on the policy’s global title.
Key takeaways
- Saudi source and actual premium/recipient facts precede the rate calculation.
- The current domestic insurance and reinsurance category is 5% within scope.
- Official Example 5 preserves fair allocation and no-added-head-office-service conditions.
- Independent services and intermediary roles require separate classification.
- Gross/net terms, actual establishment connection and treaties need their own evidence.
Sources
- Official Arabic Income Tax Implementing RegulationsArticle 5(2), p. 5; Article 63(1),(8)-(9), pp. 34–36: premium source, current rate, gross base and reporting.
- ZATCA General Withholding Tax GuidelineSecond version May 2026, Example 5 and source routes, p. 22; Example 2, pp. 15–16; rates, treaties and reporting pp. 28–31.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.