In brief
Distinguish software exploitation rights, independent support and access arrangements. Apply official examples without assuming one universal SaaS rate.
There is no single WHT answer for every software or SaaS payment. Actual exploitation rights, independent services, the user/payer, Saudi source and settlement determine the analysis. Buying access to a finished product differs from receiving rights to modify, reproduce, distribute or exploit protected technology; the word subscription alone does not settle the category.
Start with the contract’s actual rights and service
ZATCA’s General Withholding Tax Guideline, second version May 2026, sections 5.1–5.2, pp. 33–36, distinguishes royalty rights from services. Current Arabic Regulations Article 63, pp. 34–36, supplies the domestic rates, technical definition, gross base and compliance framework.
Read the licence/access terms, permitted users, hosting, data rights, modification/reproduction/distribution rights, support and implementation obligations. An invoice saying software service may contain materially different elements.
Dariba recommendation: classify the actual legal and commercial arrangement before approving a default vendor tax code. The same supplier can sell several products with different rights and service features.
Apply the specific royalty examples without inventing a universal SaaS rate
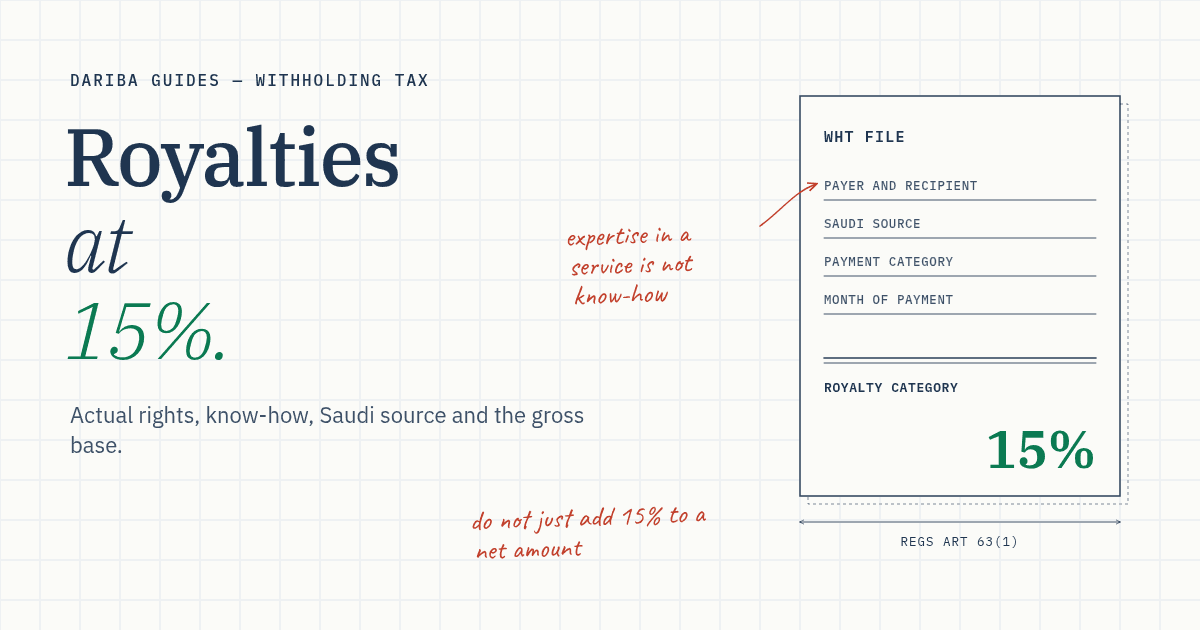
The guideline’s classification table, p. 36, treats certain customizable software with exploitation rights and specified database/technical-information rights as royalty cases. It distinguishes personal/recreational software use and certain other entries from royalties.
Those descriptions do not establish that every business end-user licence is exempt, every cloud fee is technical at 5%, or every access subscription is royalty at 15%. Establish the particular rights and source facts. A personal/recreational entry is not a blanket corporate software safe harbour.
Similarly, an open-source reference in an example cannot alone decide every paid service involving open-source code. Free code, a hosted service, independent support and a protected exploitation right require their actual transactions assessed.
Independent support and development require separate analysis
Guideline p. 23 discusses software-related support, maintenance, development, updates and training to the extent supplementary and separate from the software rather than part of it. p. 36 distinguishes unbundled support/development from royalties.
If the actual work meets Article 63(3)‘s technical-service definition and the Saudi-source conditions, the current domestic technical rate is 5%. The non-royalty description does not itself establish no withholding.
Support inseparable from the licensed rights and a genuinely independent technical service are different cases. Separately listing an amount on an invoice is evidence, not proof that a substantive independent supply exists.
Technology in delivery does not identify the payment category
The guideline p. 23 uses an online-game discussion to explain that special skills used in developing a product are not necessarily the service sold to the final customer. Providing a service through technical means does not make every payment technical.
This matters for automated access, content, platforms and hosting arrangements. Identify what the Saudi customer receives at the payment event; do not classify it solely by the supplier’s engineering staff or server technology.
Where the actual terms do not fit the guidance clearly, record the unresolved issue and seek the facts/clarification needed. This article does not certify a named SaaS product or provide an unsupported universal category for new business models.
Determine payer, source and permanent-establishment connection
Law Articles 5/68 and Regulations Article 5 require the relevant payer and Saudi source. Technical services to a Saudi resident can be Saudi-source even if performed abroad. Rights used in Saudi Arabia require their own source analysis; the server’s country alone does not decide the result.
A resident natural person’s purely private purchase differs from business payments under the natural-person scope rule. A business should not assume consumer treatment simply because a licence is bought by card or under a standard online agreement.
If the supplier has a Saudi permanent establishment, establish whether the actual payment is connected with that activity. A foreign supplier’s unrelated Saudi office does not automatically settle every overseas access or licence payment.
Allocate a genuine mixed contract on supportable values
Dariba original assumptions: a contract contains an actual SAR 60,000 gross royalty and genuinely independent SAR 40,000 gross technical services, both within scope, with no treaty/specific relief. Royalty withholding is SAR 9,000 and technical withholding SAR 2,000, totalling SAR 11,000.
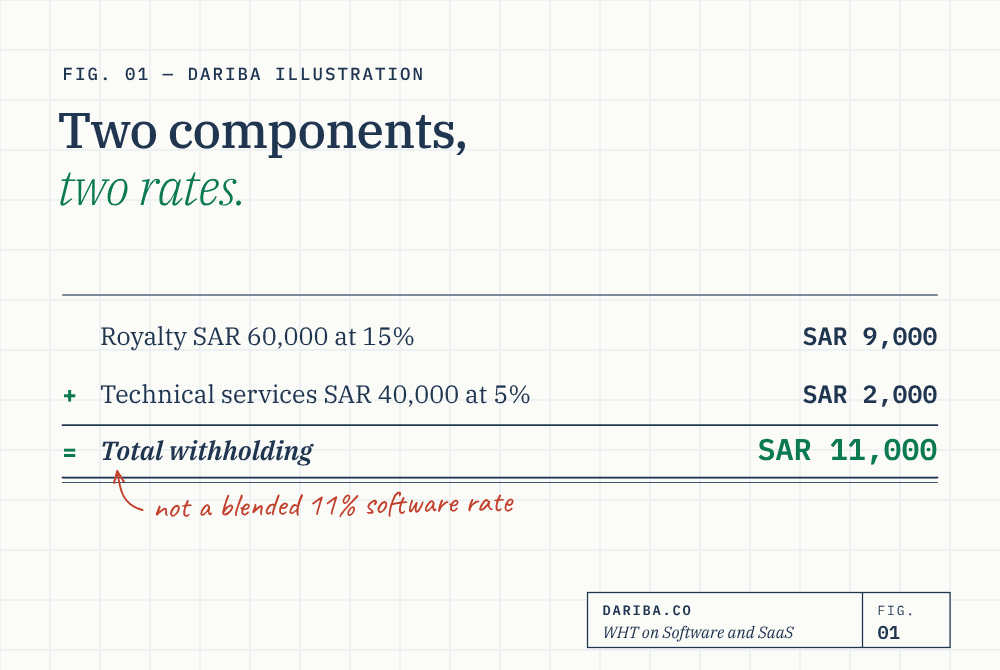
This is not a statutory blended 11% software rate. It depends on the assumed actual rights, independent work and supported values. Different facts, inseparable elements or a treaty can change the result.
Retain the pricing/deliverables basis rather than using the allocation that produces the lowest withholding. The royalty guide and technical-services guide explain those separate routes.
Establish who bears tax and keep VAT separate
Article 63(8) applies withholding to the full relevant amount without deducting the supplier’s costs. A contract guaranteeing a net supplier receipt can require a gross-up; a fixed gross fee with permitted deduction produces a different supplier receipt.
Treaty relief requires its actual article, recipient/residence and procedural conditions. It is not established merely by a foreign invoice address or the group’s preferred billing entity.
Saudi VAT/reverse charge is a separate analysis. A digital-service VAT result does not certify the WHT category, and withholding remittance cannot be claimed as input VAT. Preserve both analyses rather than assume one tax replaces the other.
Keep the rights, delivery and payment evidence together
Retain the executed terms and amendments, actual rights/user, service deliverables, source/recipient facts, supported split, tax-bearing clause, treaty evidence, settlement and withholding records. A short invoice may be insufficient to distinguish access from exploitation rights or independent services.
The compliance guide explains monthly/annual reporting, certificates and retention. Group netting or card settlement still requires the actual payment event considered.
Dariba recommends reviewing material software contracts before renewal or scope changes. A prior rate code should not be carried forward automatically when the product moves from ordinary access to different rights, a managed service or a materially changed support arrangement.
Key takeaways
- There is no supported universal rate for every software or SaaS subscription.
- Exploitation rights and independent services require separate factual analysis.
- Personal-use examples are not blanket corporate software exemptions.
- Technology used by the supplier does not itself classify the customer payment.
- Support a genuine allocation and retain source, recipient and tax-bearing evidence.
Sources
- Official Arabic Income Tax Implementing RegulationsArticles 5 and 63, pp. 5-6 and 34-36: source, current categories, gross base and reporting. Read with actual contract and recipient facts.
- ZATCA General Withholding Tax GuidelineSecond version May 2026, p. 23 and 33-36: actual software rights, independent support and technical delivery distinctions.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.