In brief
Distinguish Zakat demands, seizure and sale safeguards from Article 125(2) coordination for final dues. Royal Order 16145 supplies the original general cooperation direction; actual measures and later amendments require separate evidence.
Collection powers come with procedural and asset safeguards
Articles 120–125 of the Implementing Regulations for Zakat Collection, 1445H, govern late-payment demands, an individual proprietor’s death, seizure and sale. ZATCA’s General Guideline, sections 7.5.3–7.5.4, explains the collection process. The current Arabic regulation controls where the English explanation is broader or imprecise.
First establish the liability, its payment status and whether it is final and payable. Then distinguish a demand, seizure, transfer of funds and sale. The safeguards and effect of an ongoing dispute are not identical at each stage.
Article 120 requires successive demands and notification of measures
For delayed payment, Article 120(1) provides a first demand for payment within thirty days of notification, followed on non-payment by a second demand within the next thirty days and then a third within another thirty days. After failure to respond to the three demands, paragraph 2 permits lawful steps to compel payment and requires notification of the measures taken.
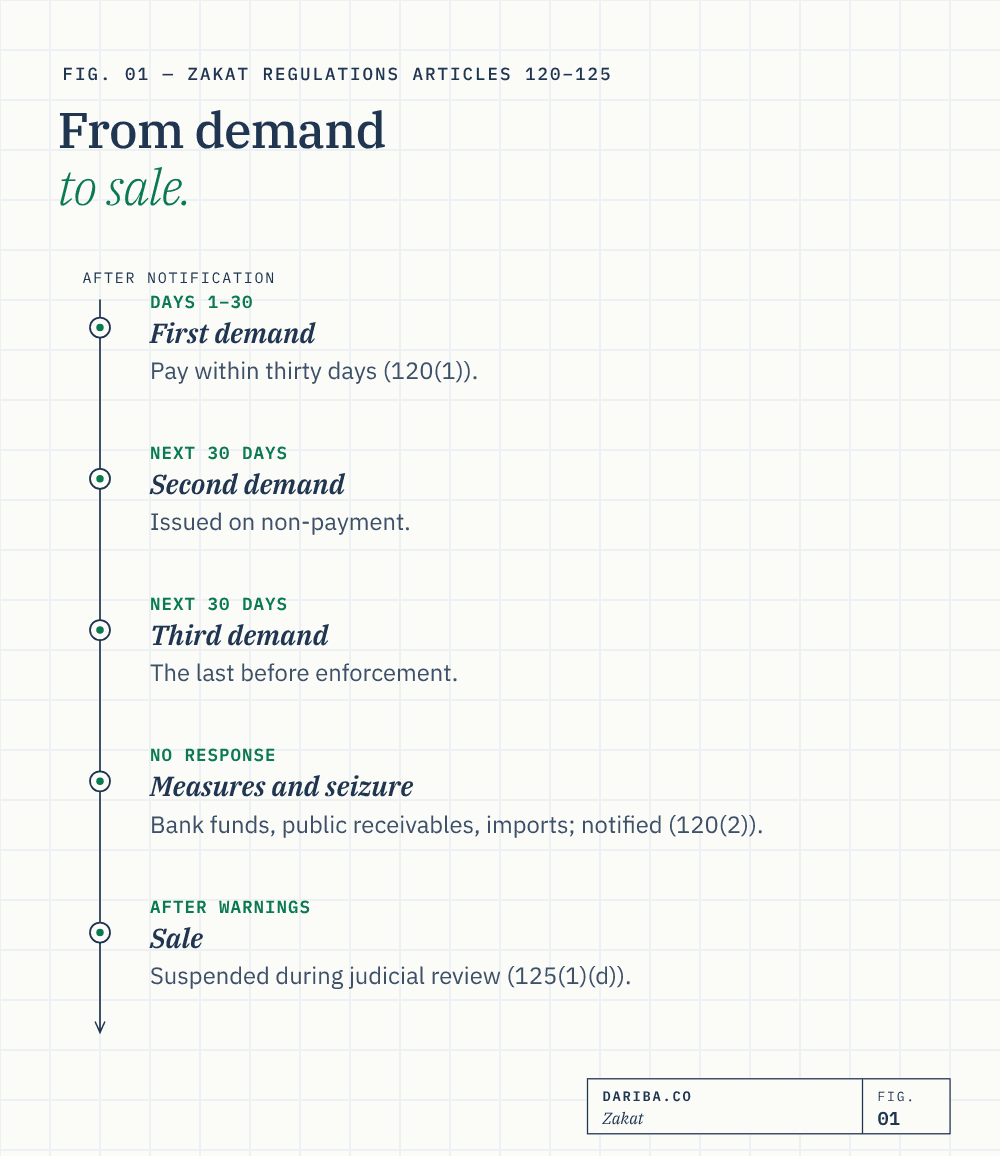
Dariba recommendation: record each demand, its notification date, the amount and the response. Reconcile a payment or credit against the actual debt promptly. Do not treat the demand sequence as permission to postpone an amount already due, or assume every enforcement situation can be answered by counting ninety days from an unrelated date.
Article 120(3) requires ZATCA, once it collects the dues, to take the necessary action to stop the measures it has taken against the taxpayer. Retain payment and collection evidence and follow up on the actual lifting of the affected measures.
Seizure may reach bank funds, public receivables and other assets
Article 122 allows ZATCA to request seizure of legally seizable movable and immovable assets where dues are not paid on time, subject to Articles 123 and 124. Article 123 identifies one or more of five routes:
- Correspondence with the Saudi Central Bank, Capital Market Authority and other relevant bodies concerning assets and bank funds, within the amount due, with transfer when requested.
- Correspondence with the Ministry of Finance concerning amounts it holds for the taxpayer, within the amount due.
- Correspondence with the Ministry of Justice to stop disposal of immovable assets.
- Seizure of imports within the amount due.
- A request to seize an amount a third party owes the taxpayer.
Dariba analysis: a debt owed to the taxpayer by a customer or another third party can become relevant even if the taxpayer’s own bank account is low. Identify the actual legal debtor, ownership and amount; a collection power does not automatically make every group company’s assets the taxpayer’s assets.
Employee dues, living expenses and the stated tools limit matter
Article 124(1) protects taxpayer funds due to employees or others, including living expenses, under the applicable laws, regulations and rules. The protected funds are identified using information available to ZATCA. Substantiation therefore matters; a general assertion that all cash is needed for operations does not identify the statutory category.
Article 124(3) limits seizure of amounts owed by third parties to the Zakat dues and addresses natural persons who are general partners in the specified partnership forms. It excludes tools used by the taxpayer in its activity and personal necessities within the stated SAR 300,000 limit.
The limit is not a universal SAR 300,000 exemption for every bank balance or an allowance multiplied by each collection channel. Likewise, the provision should not be read as making all shareholders in every company form personally liable. The actual legal form, partner capacity, ownership and statutory conditions require review.
A third party receiving a seizure request has its own task
Article 124(2) requires the entity carrying out seizure to deliver the seized funds to ZATCA when requested, including amounts it owes the taxpayer at receipt of the relevant seizure and delivery notice. The actual notice, amounts and legal relationships need to be reconciled.
Dariba recommendation: a bank, customer or other recipient should route the notice promptly to the responsible legal and finance staff. Identify the funds or debt covered and obtain clarification of a genuine ownership or amount discrepancy through the official channel. Do not assume that the taxpayer’s informal request authorises release of funds contrary to the notice.
For the taxpayer, keep the third-party deduction and remittance evidence so the same liability can be reconciled against ZATCA’s account. An amount withheld by a customer and an amount actually delivered to the Authority are separate events that should be traceable.
Sale follows seizure and warning periods, with proceeds accounted for
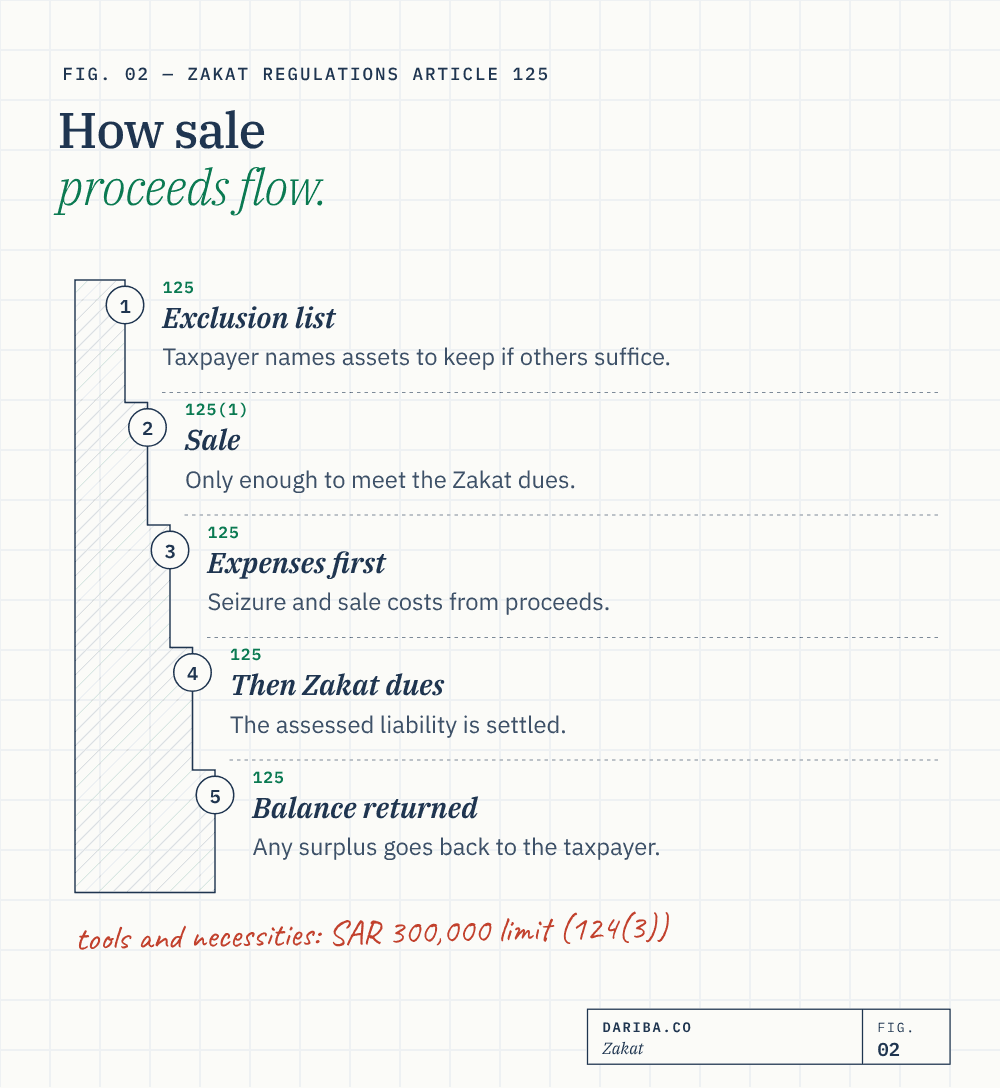
Article 125(1) permits execution through sale sufficient to meet the Zakat dues after seizure procedures and warning periods have ended, under applicable procedures. ZATCA or the competent authority conducts the sale.
The taxpayer must be allowed to submit a list of assets it wishes to exclude from sale if the sale value of other assets is sufficient to cover the dues. This condition does not provide an unconditional right to retain any preferred asset regardless of the remaining cover.
Seizure and sale expenses are paid from the proceeds first, then Zakat dues, with the remaining balance returned to the taxpayer. Dariba recommendation: retain asset valuations, the proposed exclusion list, the decision, sale information and the allocation of proceeds. Explain how the assets proposed for sale cover the debt and relevant expenses rather than presenting book values without context.
Judicial review suspends the specified sale, with exceptions
Article 125(1)(d), in the current Arabic text, suspends sale during judicial review of the Zakat assessment on which seizure was based. It excepts assets exposed to deterioration and assets the taxpayer requests to be sold.
The English General Guideline’s collection discussion uses broader wording referring to administrative or judicial review. The controlling Arabic provision expressly identifies judicial review. An administrative objection should therefore not be described as automatically creating this statutory sale suspension on the strength of the broader translation.
Dariba analysis: this is a sale safeguard tied to the assessment under judicial review, not a statement that every seizure, payment obligation or collection measure automatically stops. Identify the relevant case, assessment and assets, document the pending judicial review and address any perishable-asset or requested-sale exception specifically.
Other restrictions depend on the actual legal instrument
Article 125(2) of the current Arabic Regulations provides for coordination with relevant bodies where the taxpayer has final dues, based on Royal Order 16145 dated 1/4/1437H and any amendments. It identifies government competitions, recruitment of workers, and issuing or renewing the registrations and work licences that enable the activity. The final-dues condition is part of this specific provision.
The original Royal Order, available from the National Center for Archives and Records (NCAR), is a general cooperation direction. Addressed to the Crown Prince, Deputy Prime Minister and Minister of Interior, with copies to ministries and government departments for onward notification, it approves the stated recommendation that government bodies, companies in which the State participates and professional bodies cooperate with the then Department of Zakat and Income Tax. It names the Saudi accounting, engineering and lawyers’ bodies among the professional examples.
The stated purpose is more efficient and effective collection of Zakat for its recognised destinations and collection of taxes for the public treasury. The original order’s operative text does not enumerate the tender, recruitment and licensing restrictions or prescribe a separate waiting period. Attribute the specific power described here to current Article 125(2), read with the order and applicable amendments. The original’s general direction should not be presented as an independent instruction automatically imposing every restriction on every overdue taxpayer.
Sources: current Regulations, Article 125(2); Royal Order 16145, original cooperation direction held by NCAR. The original has now been read; a complete later amendment chain and each body’s actual implementation remain separate questions.
Dariba analysis: when a tender or recruitment restriction is reported, establish the final liability, actual notice, imposing body and legal basis. An unpaid balance, a particular coordination measure and the subsequent lifting of that measure are distinct facts. The order’s recovery does not establish that an actual case satisfies the current Regulations or that every related service must remain blocked.
Dariba recommendation: keep the assessment/finality record, collection account, correspondence and evidence of payment or any approved instalment arrangement together. Article 120(3) requires the necessary action to stop the Authority’s measures once the dues are collected; retain evidence of the actual resolution. Do not assume that an application alone approves instalments, settles the debt or lifts a measure.
Death of an individual proprietor does not erase the dues
Article 121 requires collection of an individual establishment owner’s unpaid Zakat before distribution of the estate. Otherwise, heirs or legatees may be required to pay according to their share of the estate, without exceeding the total estate.
The provision concerns the individual proprietor and the estate. It should not be generalised into unlimited personal liability for heirs or automatic liability for every relative, director or shareholder.
Dariba recommendation: before estate distribution, identify the proprietor’s Zakat account, returns, assessments, payments and pending proceedings. Coordinate the evidence and proposed allocation with the estate’s authorised representatives. The actual estate and each recipient’s share are material to the statutory limit.
Key takeaways
- Article 120 provides successive demands and notification of measures.
- Bank funds and third-party receivables may be reached.
- Protected amounts and the tools limit retain their actual conditions.
- Sale proceeds cover expenses, dues and any returned surplus.
- The Arabic sale-suspension rule refers to judicial review.
- An individual proprietor’s estate has a specific liability rule.
- The original Royal Order 16145 directs general cooperation; current Article 125(2) specifies the final-dues coordination power.
Sources
- Implementing Regulations for Zakat Collection, 1445H, current Arabic textArticles 120–125; Article 125(2) final-dues condition and specified coordination; Article 120(3) stopping measures on collection. Current Arabic controls.
- ZATCA General Guideline for Zakat Collection, 1445HSections 7.5.3–7.5.4. The Arabic judicial-review wording in Article 125 controls over the broader English explanation.
- Rules of Procedure of the Zakat, Tax and Customs Committees, Royal Order 25711Rules 5–7 and 46; actual notification-based periods and disputed/undisputed distinction.
- Royal Order 16145 dated 1/4/1437H, official NCAR originalOriginal one-page cooperation direction; recipients, professional examples, collection purposes and operative approval read. Does not itself enumerate Article 125(2) restrictions; later amendments and actual implementation remain separately qualified.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.