In brief
Zero-rated supplies are taxable at 0%, while exempt supplies have different ordinary input consequences. Actual evidence, restricted costs, shared use and special routes remain relevant; the ninety-day export rule is not blanket permanent loss.
Zero-rated supplies are taxable supplies at 0%; exempt supplies receive a different statutory treatment. Both may show no output VAT to the customer, but their ordinary input-recovery consequences differ. Neither classification means every cost is automatically recoverable or permanently blocked without examining the actual use, evidence and applicable special rules.
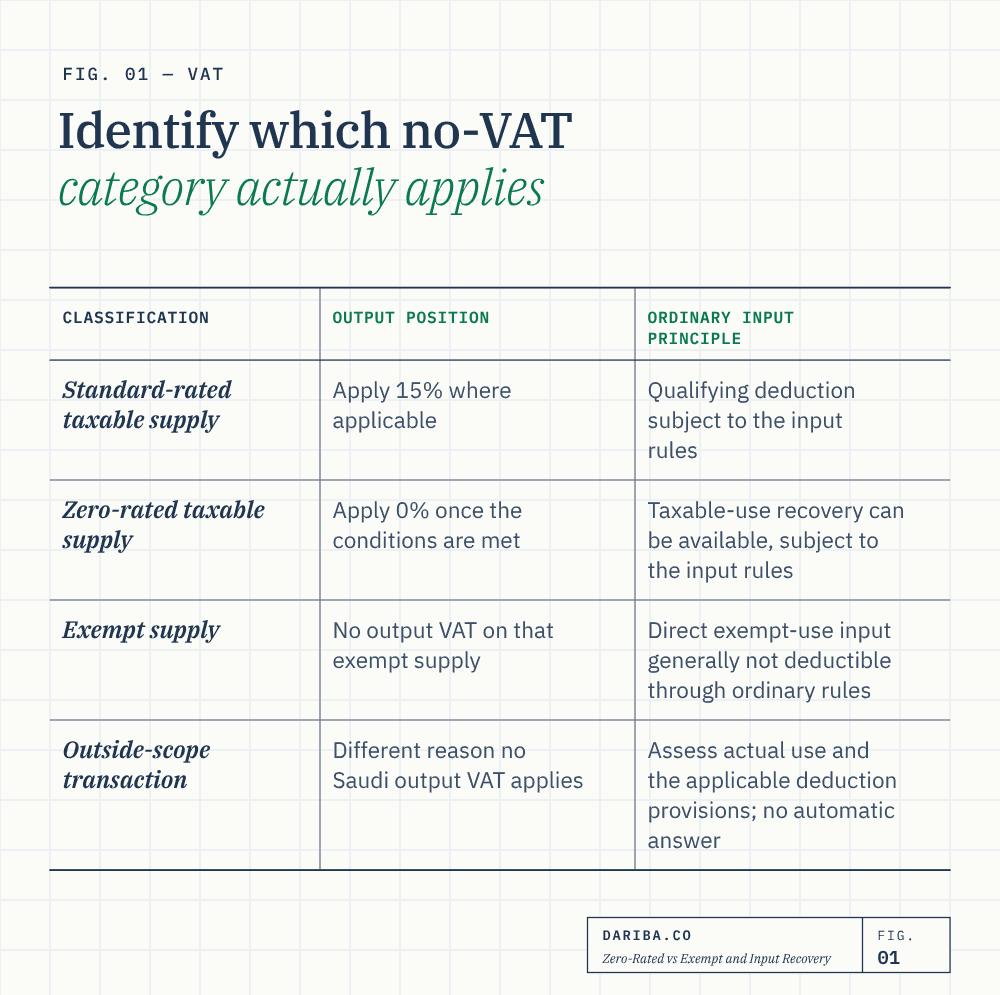
Identify which no-VAT category actually applies
| Classification | Output position | Ordinary input principle |
|---|---|---|
| Standard-rated taxable supply | Apply 15% where applicable | Qualifying deduction subject to the input rules |
| Zero-rated taxable supply | Apply 0% once the conditions are met | Taxable-use recovery can be available, subject to the input rules |
| Exempt supply | No output VAT on that exempt supply | Direct exempt-use input generally not deductible through ordinary rules |
| Outside-scope transaction | Different reason no Saudi output VAT applies | Assess actual use and the applicable deduction provisions; no automatic answer |
An unregistered supplier, government-bearing arrangement or foreign customer is not itself a legal zero-rate category. Start with whether there is a supply, its place, nature, liable person and actual statutory conditions. Registration and return obligations must then be assessed separately.
When zero-rating prevails over an exemption
Article 31(2) treats a supply qualifying both for the Chapter Five exemption and Chapter Six zero-rating as zero-rated. It is a priority rule for an actually qualifying supply, not permission to select the most favourable category without meeting its conditions.
ZATCA’s Services to Non-GCC Residents guideline, fourth version May 2026, section 4.3, Example 1, p. 12, describes a Saudi insurer supplying life insurance to a customer with no establishment/residence in a GCC state. The supply would be exempt domestically but qualifies for zero-rating on the stated non-GCC facts provided none of the exceptions applies.
Dariba analysis: domestic exemption does not necessarily end the enquiry. Article 33’s actual recipient, residence, special-place and direct-benefit exceptions must be tested. A foreign billing address alone does not establish the example’s result, and the zero-rate priority does not make every related input fully deductible.
Know the zero-rate routes without dropping their conditions
Chapter Six contains distinct routes: Article 32 goods exports; Article 32 bis specified customs-suspension transactions; Article 33 qualifying services to non-GCC residents; Article 34 international transport and specified related supplies; Article 35 qualifying medicines/medical goods; Article 36 qualifying metals; and the specified military/diplomatic provisions following Article 36.
Their requirements are different. A foreign shipment is not automatically a qualifying export; every overseas client does not satisfy Article 33; every transport asset is not a qualifying international means of transport; a medical description does not replace the competent authority’s classification. Investment-metal criteria, qualified military supplier/certificate requirements and qualified diplomatic-supplier rules also need the actual provision and current implementing requirements applied.
Article 32 bis additionally distinguishes zero-rated supplies from suspended import tax that becomes due on leaving suspension. A business’s presence in an area called a special zone does not, without the statutory conditions, prove every transaction is zero-rated. Identify the particular transaction and customs-suspension provision before assigning its VAT treatment.
This comparison is a route map, not certification of every product listing, military certificate, diplomatic approval or customs procedure. Establish the actual qualification before applying a 0% code.
Export evidence: ninety days is not a blanket permanent-loss rule
Article 32 requires the specified evidence within ninety days and prevents unsupported export treatment after that period. The ordinary evidence includes customs, commercial and transport documents. Actual export, dates and documentary sufficiency matter; an invoice saying “export” is not enough.
The current text also addresses rejected/insufficient documents and later evidence under paragraph (4). The Imports and Exports guideline, second edition May 2026, section 7.4, p. 38, explains non-export treatment until necessary evidence is later submitted and standard-rate treatment where the required documents are not obtained by the deadline. A missed evidence deadline should therefore not be described as permanent, incurable loss of zero-rating in every case.
Later evidence is not a general permission to ignore the ninety-day requirement, invent an export that did not occur, or bypass applicable correction/refund time limits. Distinguish delayed proof, rejected proof, actual movement and the proper adjustment procedure.
Official example: section 7.4, Example 9, p. 39, gives Al-Karamah’s wooden-panel sale to Turkey, transport starting 28 June 2018 and export/shipping documents received 3 July confirming export. ZATCA applies zero-rating on those facts. No sale amount is supplied in that example, and it is not an example of late evidence outside ninety days.
Exemption is wider than residential sales
Articles 29–30 govern the relevant financial-service and property exemptions. Specified financial margins/securities and qualifying life contracts require their own classification; explicit remuneration and genuinely separate services can differ. Not every service of a bank or insurer is exempt.
Article 30’s ownership-transfer exemption covers the specified commercial, residential, agricultural and land transfers. Residential leasing/licensing is a separate exemption; ordinary taxable commercial leasing is different. Hotel/serviced visitor accommodation is excluded from the residential definition. A hotel building’s sale and its guest accommodation are different supplies.
See the exempt-supplies analysis for the financial and property conditions. Do not use a no-output-tax comparison table as a substitute for classifying the actual supply.
Compare recovery using the actual costs
Dariba illustration — original assumptions: a registered supplier incurs SAR 15,000 correctly charged VAT on costs directly attributable to otherwise qualifying supplies. If those costs are wholly for a qualifying zero-rated taxable supply, deduction may be SAR 15,000, provided all entitlement/evidence conditions are met. If wholly for an ordinary exempt residential lease with no applicable special route, ordinary deduction is nil.
If SAR 3,000 of the apparent SAR 15,000 input is actually blocked under Article 50, a zero-rated output does not cure the restriction: the assumed deduction falls to SAR 12,000. Zero-rating preserves the taxable-use principle, not unconditional recovery of every invoice.
Special incidental-transaction treatment, approved developer refunds and capital adjustments require their own analysis. A refund request under Article 69 is also distinct from the deduction that creates a valid credit; zero-rated output does not guarantee a payment merely because a cost schedule was uploaded.
Mixed costs require attribution before a ratio
Wholly taxable-use, wholly exempt-use and genuinely shared inputs should be identified first. The applicable Article 51 method, exclusions, required rounding, annual reconciliation and any permitted alternative then govern shared recovery. The prior year’s supply values, actual-use evidence and later changes cannot be replaced by an unsupported estimated percentage in every return.
Dariba illustration: assume a valid 40% recovery entitlement for a particular pool of SAR 500,000 shared input VAT, after the necessary exclusions and attribution. Deductible shared input is SAR 200,000 and the non-deductible portion SAR 300,000. That is not proof that 40% applies to every separate purchase or that the same allocation is permitted for every property business.
The apportionment guide explains the default and alternative-method conditions. Article 51(9) limits an approved alternative-method period to no more than five years, renewable through a new application. The actual notification specifies the term and conditions; it does not automatically grant five years.
Keep classification, registration and evidence connected
Zero-rated taxable supplies generally enter the relevant registration calculation, with Article 9(1)‘s exception for exclusively zero-rated supplies and voluntary-registration options. Exempt outputs are different, but qualifying received supplies, expenses and actual status can also matter; see the registration guide.
Retain the legal classification, customer/supply evidence, export documents or certificates, input analysis and return/correction history. A transaction can need correction even if the customer paid no output VAT. The appropriate period, assessment powers and records obligations are separate questions, not a universal five-year rule or automatic penalty outcome.
Key takeaways
- Zero-rated taxable, exempt and outside-scope transactions are different categories.
- Article 31(2) gives priority only where the supply actually qualifies for both exemption and zero-rating.
- Zero-rated output does not cure blocked inputs or guarantee a cash refund.
- Export evidence ordinarily uses ninety days, but the current later-evidence framework makes blanket permanent-loss claims incorrect.
- Special zero-rate routes retain their actual conditions; customs import suspension is not identical to every zero-rated supply.
- Mixed inputs require attribution and the applicable method, rounding and adjustments before applying a shared recovery fraction.
Sources
- Controlling Arabic VAT Implementing RegulationsTenth edition April 2025. Articles 29-36, pp. 27-35; Articles 49-52, pages 48-54; relevant registration/correction/records distinctions. Arabic controls.
- ZATCA Imports and Exports guidelineSecond edition May 2026. Section 7.4, pages 38-39, export proof and Example 9; ninety-day ordinary requirement and later evidence distinguished without an unlimited waiver.
- ZATCA Services to Non-GCC Residents guidelineFourth version May 2026. Section 4.3 Example 1, page 12, otherwise exempt life insurance zero-rated only where actual conditions and exceptions permit.
- ZATCA Input Tax Deduction guidelineThird version May 2026. Entitlement, restricted costs, direct attribution and shared-cost methods remain conditional; a taxable output or invoice alone is not full deduction.
- ZATCA Real Estate Sector guidelineIssue 3.0 May 2026. Sections 2-3, pages 7-10; section 6 Examples 5-9, pages 14-17; sections 8-9, pages 19-24. Home, school, four-month traveller, optional parking and incidental disposal examples retain facts.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.