In brief
Article 2(g) uses the fair market value of the real estate at the actual BOOT ownership transfer. Article 4(c) identifies that date for the non-notarized case; the applicable 30-day payment rule is not a universal extension after notarization.
A project may cost SAR 150 million to build and have a different value when ownership passes years later. ZATCA’s RETT Implementing Regulations Article 2(g) addresses that difference: for a taxable BOOT real-estate transaction, use fair market value at the actual ownership transfer, with timing determined under Article 4.
Establish the date before fixing the value
Article 4’s opening words concern cases where notarization has not occurred. Its BOOT rule in paragraph (c) identifies actual ownership transfer to the transferee, meaning the date all contractual conditions relating to that transfer are satisfied.
This does not mean every BOOT transfers ownership only at final expiry. It also does not mean every acceptance certificate establishes ownership. Read the contract and actual rights, including amendments and early-termination provisions.
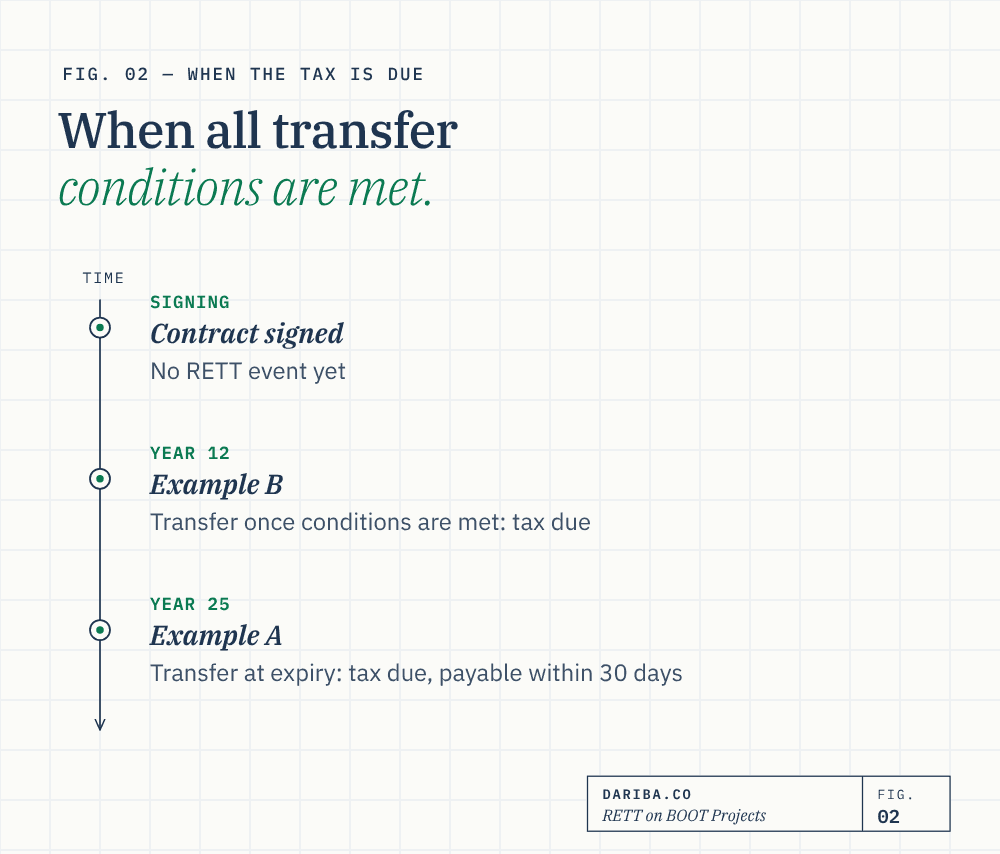
ZATCA’s Detailed RETT Guideline, Version 6, section 4.4, Example 12, printed page 21, makes the timing distinction concrete:
| Official case | Contract and actual ownership-transfer facts |
|---|---|
| Example 12(A) | A 25-year BOOT; transfer after expiry and fulfilment of ownership-transfer conditions |
| Example 12(B) | A 25-year BOOT; transfer after 12 years once the specified ownership-transfer conditions are fulfilled |
The second case cannot be treated as a year-25 tax event merely because the wider contract lasts 25 years. These examples also do not postpone a separate land purchase or a separate taxable usufruct grant until handback.
Dariba illustration: cost differs from transfer-date value
Assume a private landowner and an energy company sign a 20-year BOOT in 2026. Assume that the energy company actually transfers the relevant real estate in 2046, after all ownership-transfer conditions are met. Construction cost was SAR 150 million. A supportable transfer-date valuation puts the real estate actually transferred at SAR 90 million.
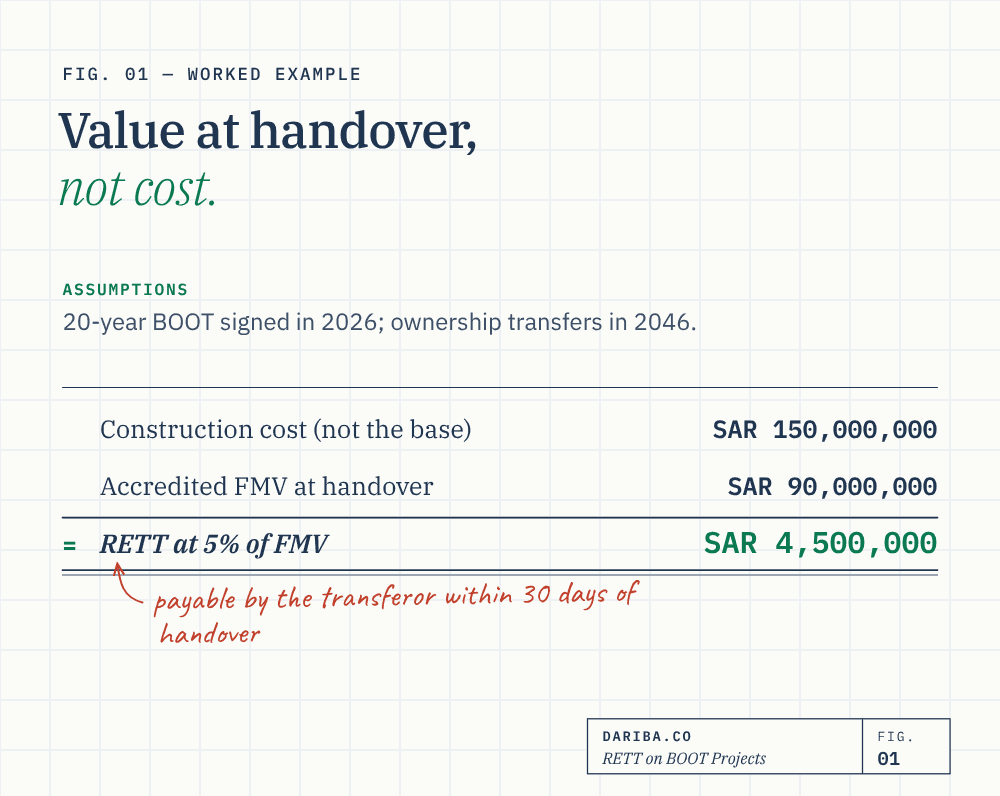
Under the current Article 2(g) rule and 5% rate, and assuming no exemption, the illustration is:
| Item | Amount |
|---|---|
| Original construction cost | SAR 150 million |
| Assumed relevant fair market value at actual transfer | SAR 90 million |
| Illustrative RETT base | SAR 90 million |
| Illustrative RETT at 5% | SAR 4.5 million |
This is Dariba’s assumed application, not ZATCA’s Example 12 and not a forecast of the law or value in 2046. The difference between cost and the assumed base is SAR 60 million. It does not itself establish any tax deduction or depreciation rule.
The retained illustration’s 30-day payment wording concerns the applicable non-notarized transfer. Article 5(b) provides that period from the relevant Article 4 date. Do not treat it as an unconditional right to delay payment after notarization. Resolve the actual formalities and payment requirements before closing.
Define what real estate passes
Value the rights and property that actually move. Where the recipient already owns the underlying land, that fact must be reflected in the valuation scope rather than assuming a second transfer of the same land ownership.
Buildings, closely connected rights and permanently allocated items also require analysis under the Law and Regulations, including Article 2(b). Detachability alone does not exclude an item. Conversely, the project’s total business value or every movable operating asset is not automatically the real estate transferred.
For staged handovers, identify whether each stage actually transfers separate ownership rights and whether the contractual conditions have been met. A single project label does not answer that question. Early termination likewise needs evidence of the resulting transfer, rather than an assumption that termination and ownership always occur together.
Test relief and identify the taxpayer
A qualifying public recipient may bring a transfer within Article 3(a)(4). Establish that status and the applicable conditions. Do not substitute the separate Article 3(a)(5) rule for a public grantor, or infer public legal personality solely from state share ownership.
Law Article 7 generally places responsibility on the transferor and identifies the person for whose benefit the transfer is made. The builder, operator, signatory and beneficial transferor need not be interchangeable descriptions in every arrangement. A contractual tax allocation should be reconciled with that statutory position.
A valuation report, exemption analysis and payment timetable should therefore describe the same transfer: the same parties, rights, date and property. Keep those records alongside the ownership-condition evidence and registration. See the BOOT overview and payment-deadline guide for the related distinctions.
Key takeaways
- Construction cost, contract signing and planned final expiry do not automatically determine the Article 2(g) base or date.
- An actual ownership transfer after 12 years can be relevant even within a 25-year concession, as in ZATCA Example 12(B).
- The 30-day rule applies to the relevant non-notarized transfer; notarization and other specific rules still matter.
- Separate land, improvement, equipment and rights analysis establishes what real estate actually passes.
- An assumed SAR 90 million taxable base produces SAR 4.5 million at the current 5% rate.
- A long-range illustration is not a guarantee of the law or value at a future handover.
Frequently asked questions
Does BOOT always mean RETT at the end of the operating term?
No. Identify actual ownership transfer and fulfilment of the contractual transfer conditions. Example 12(B) has a 25-year agreement but a transfer after 12 years. Separate acquisitions and usufruct grants are assessed independently.
Can construction cost be used instead of market value?
Article 2(g) specifies fair market value of the real estate at the relevant actual transfer date. Original cost may be evidence in a valuation, but it does not replace that rule.
Is an accredited valuation or public recipient an automatic guarantee?
No. A valuation supports the declared figure without binding ZATCA to accept it. A qualifying public recipient may establish Article 3(a)(4) relief, but the actual recipient and conditions must be verified rather than inferred from a project's government connection.
Sources
- ZATCA — Real Estate Transaction Tax Law (Arabic)Articles 1–3, 5 and 7
- ZATCA — RETT Implementing Regulations (Arabic)Articles 2(b), 2(g), 3(a)(4)–(5), 4(c), 5(b) and 11
- ZATCA — Detailed RETT Guideline, Version 6, May 2026Sections 4.2–4.4; Example 12, printed pages 17 and 19–21
Reviewed against the RETT Law, the controlling Arabic Implementing Regulations and ZATCA's Detailed RETT Guideline Version 6 (May 2026). The guideline does not amend the legislation. Historical transactions need their applicable-period analysis. General information, not transaction-specific advice. Dariba.co is independent of ZATCA.