In brief
New interests from a real estate company's capital increase fall outside the selected property-transaction rule in the two stated cases. Do not replace original-interest retention with an unchanged-percentage requirement or import exemption breach machinery without establishing its legal basis.
A company can issue new interests while existing owners keep their old interests. That differs from those owners selling their stakes. Article 2(j) of the Zakat, Tax and Customs Authority’s Implementing Regulations of the Real Estate Transaction Tax Law addresses ownership of new interests through a real estate company’s capital increase.
Two stated cases
| Route | Condition |
|---|---|
| Existing owners take new interests | Their ownership percentages remain unchanged from before the increase. |
| New owners take interests from the increase | Existing owners retain their pre-increase interests and do not dispose of them for five years from the increase. |
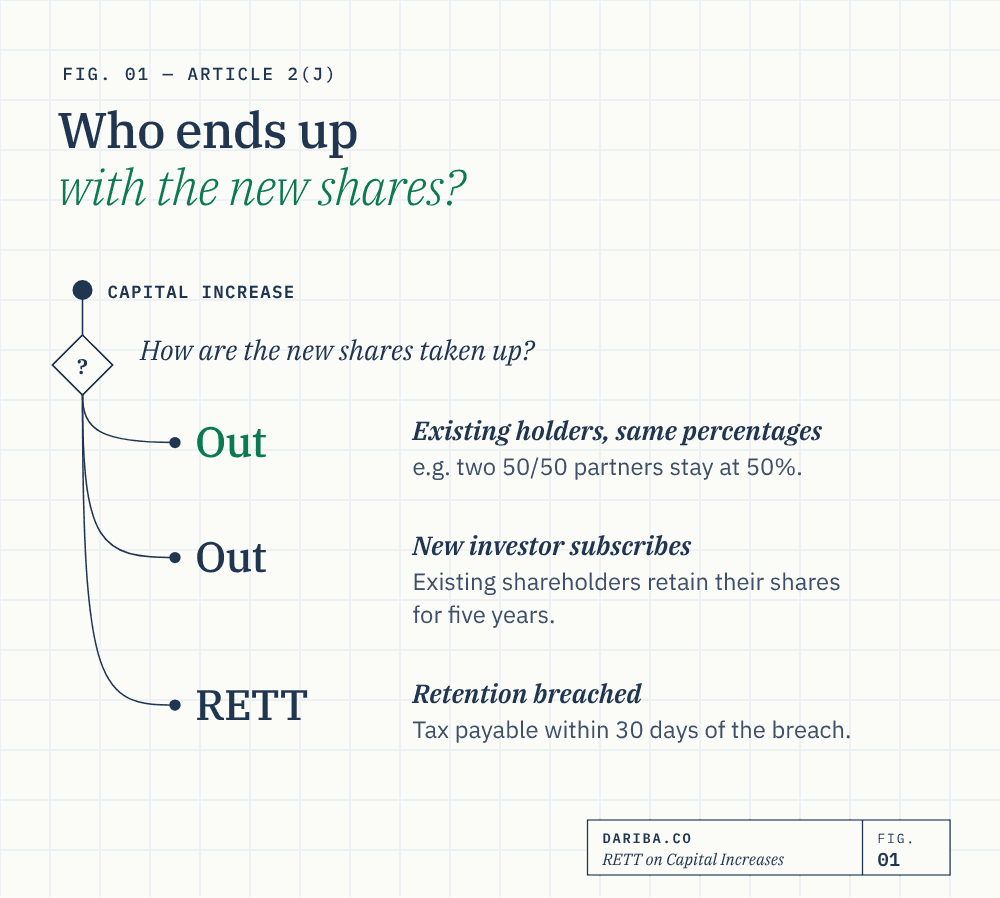
The diagram summarises the two routes. Its reference to an automatic 30-day breach payment should not be used as a statutory conclusion for Article 2(j): the separate exemption-breach rule requires its own applicable legal basis.
The selected provision concerns scope, rather than a grant of Article 3 exemption. Do not casually interchange those two legal categories.
Official illustration and translated wording
ZATCA’s Detailed Guideline version 6, section 3.2, Example 3, illustrates two 50/50 owners preserving percentages and a new investor joining while old interests are retained.
One English sentence in that section uses “not exceeding five years.” The controlling Arabic Article 2(j)(2) requires retention for five years from the increase; the following example also uses five years. Do not read the translated sentence as permission to dispose of the old interests earlier.
Dariba share-count examples
Pro-rata issue: A and B hold 50 interests each. They each subscribe for another 50. Each holds 100 of 200, remaining at 50%. The unchanged percentages support the first route, subject to the actual facts.
New investor: A and B instead keep their 50 each, and C subscribes for 100 new interests. A and B each hold 25%, and C holds 50%, of 200. Their percentages fall, but their original 100 interests remain. The second route is not accurately described as requiring their combined percentage to stay at 100%.
A subscription by an existing owner that changes percentages is not automatically within the pro-rata route. Establish whether the actual arrangement satisfies a stated route rather than assuming every capital increase qualifies.
Property contributed alongside the issue
If an owner contributes land in exchange for the new interests, analyse that property transfer separately. Article 3(a)(11) can be relevant to a qualifying company capital contribution, with its corresponding-interest retention and audited-statement conditions.
Article 2(j) does not by itself remove tax from every underlying asset transfer. Nor does it automatically determine the separate sale of old interests to a new investor.
A later disposal of original interests
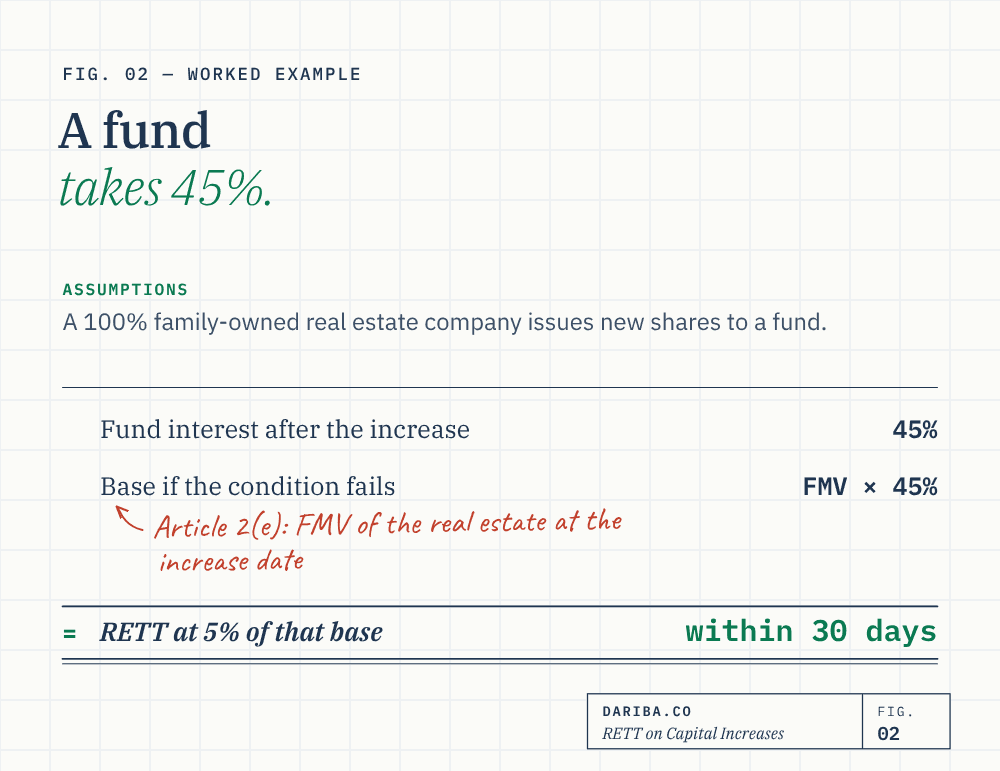
The retained fund-entry illustration includes a proposed 45% property-value benchmark on a later failure. That is a planning illustration, not a prescribed statutory base for every Article 2(j) case.
The guideline describes adverse treatment when the retention requirement fails, but the cited Article 2(j) does not itself supply a complete valuation, allocation and payment procedure for every later event. In particular, Regulations 5(a)(2) is framed around exemption-condition failures, while Article 3(c) concerns specified exemption retention protections. Their application here must be established, not assumed by analogy.
For an actual failure, identify the old and new interests, dates, relevant transactions, any applicable express treatment and the legally supported base. A separate sale may also need Article 2(i) analysis. Do not promise either an automatic 45% tax base, a universal 30-day-from-failure period or immunity because a subscription percentage was below 30%.
Keep a capital-event schedule
Retain the issue documents, before/after registers, original-interest identification and actual increase date. Review any sale, cancellation or restructuring against the applicable provision before completing it. A proposed event is an opportunity to resolve its treatment; it is not evidence that a breach has already occurred.
Key takeaways
- Existing owners' pro-rata subscription route preserves their percentages.
- The new-owner route requires retention of the pre-increase interests for five years from the increase.
- An accompanying property contribution needs its own analysis; the new-interest rule does not exempt the land automatically.
- Article 3(c) addresses exemption retention conditions and is not an express universal exception from Article 2(j).
- A later failure warrants review, but the exact taxable base and payment mechanism must not be invented from an exemption analogy.
- The ordinary 30% disposal rule is not an automatic override of the separate capital-increase wording.
Frequently asked questions
Must original owners retain the same percentage when a new investor subscribes?
Article 2(j)(2) requires retention of their pre-increase interests. Their percentage can fall because new interests are issued. That differs from the unchanged-percentage condition in the existing-owner route.
Does the rule automatically exempt property paid into the company?
No. It addresses ownership of new interests from the capital increase. A direct property contribution needs its own scope, value and actual exemption analysis.
Is every later retention failure automatically payable 30 days from breach?
The prior article imported the exemption-breach rule without establishing its application to this outside-scope provision. Identify the actual legal basis, transaction, value and payment trigger rather than treating that analogy as an express rule.
Sources
Reviewed against the Arabic RETT Law and Implementing Regulations on 20 November 2026. ZATCA's Detailed Guideline version 6 (May 2026) is explanatory; its English text does not override the Arabic instruments. Dariba is independent of ZATCA. General information, not advice on a specific transaction.