In brief
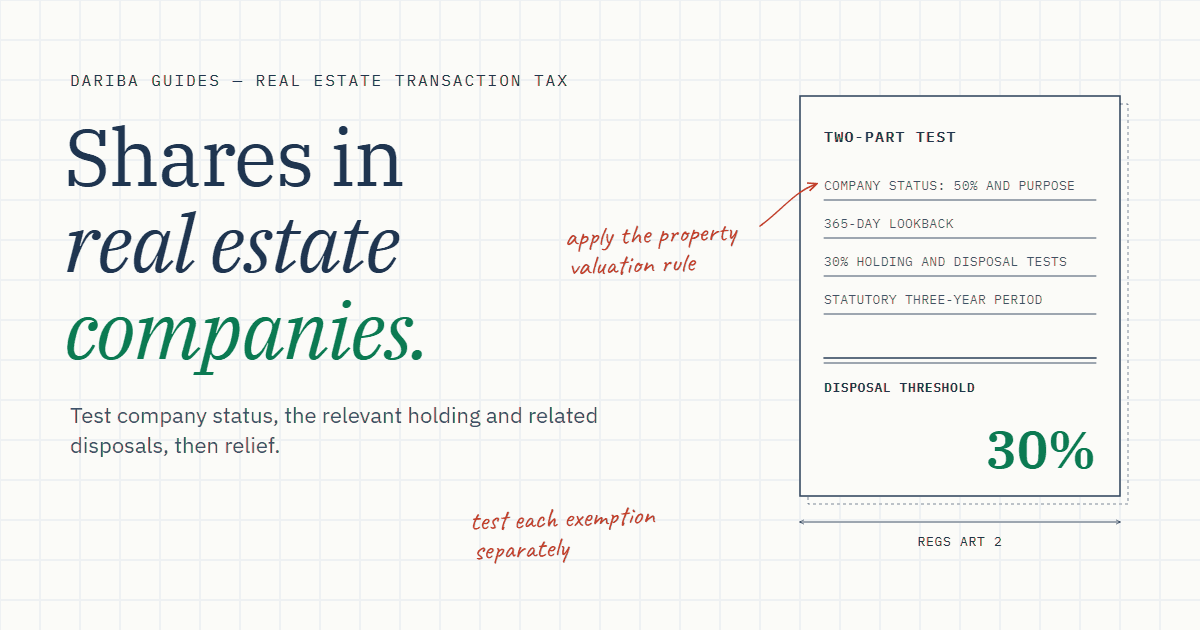
Law Article 1 and Regulations Article 2(h) define the relevant company, fund or entity by its Saudi property, revenue purpose and the specified FMV ratio/history. Meeting the definition does not by itself establish that a particular share disposal is taxable.
The “real estate company” definition is an important gate for RETT on interests in an entity. It does not independently make every share deal taxable. Read Article 1 of the Real Estate Transaction Tax Law with Article 2(h) of the Zakat, Tax and Customs Authority’s Implementing Regulations.
The four factual elements
| Element | What the provision requires |
|---|---|
| Entity and ownership | A company, fund or entity owning property directly or indirectly. |
| Location and purpose | Saudi property held to generate revenue through sale or leasing. |
| Ratio | The relevant property’s total fair market value is at least 50% of total asset fair market value. |
| Time | The ratio applies at the interest transfer or at any time during the preceding 365 days. |
An entity’s purpose of incorporation and its purpose in holding the property are different questions. The Law’s regardless-of-incorporation-purpose wording does not delete the revenue-purpose condition for the property.
The entity’s nationality or a label such as “trading company” is not itself the test. Equally, calling a factory owner an operating business does not establish the legal treatment of every rented, surplus, development or owner-used property in its portfolio.
Use FMV on both sides
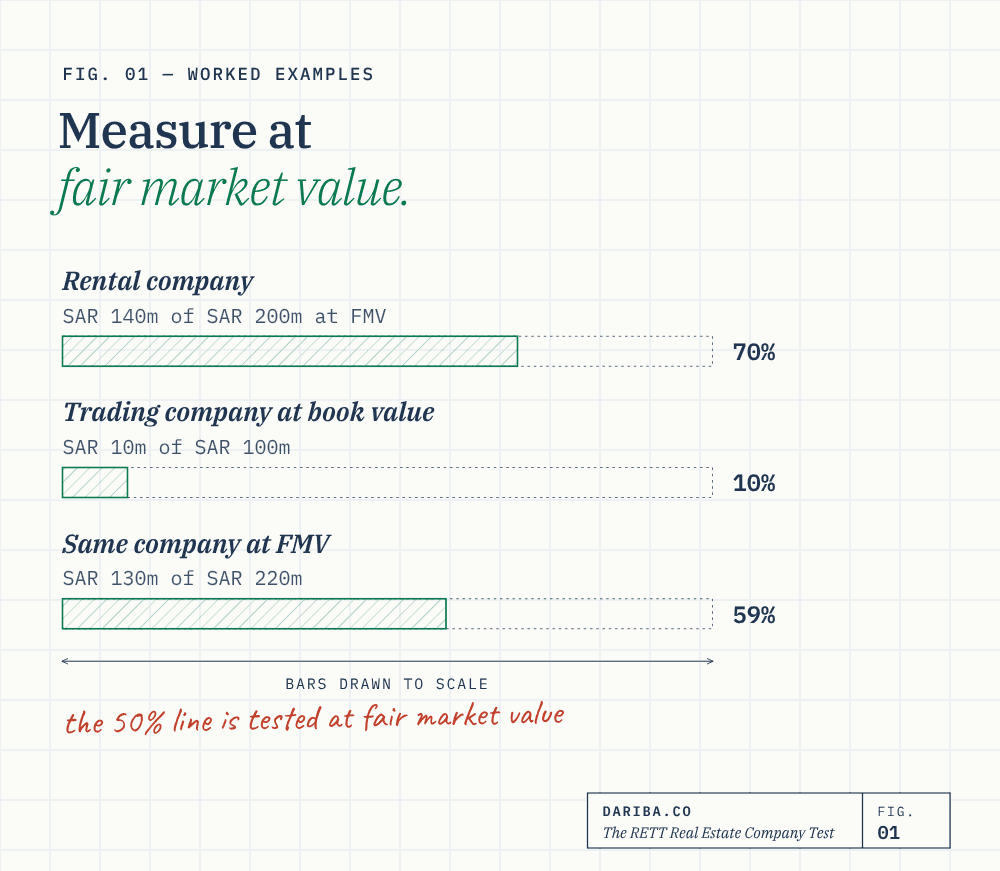
The retained diagram compares a rental portfolio and land recorded below current value. The following are Dariba calculations on those assumed facts.
Rental portfolio: relevant rental property of SAR 140 million within total assets at FMV of SAR 200 million gives 70%. The assumed ratio exceeds the threshold.
Book value versus FMV: land of SAR 10 million within SAR 100 million of book assets gives 10% in the accounts. If its FMV is SAR 130 million and total asset FMV SAR 220 million, the relevant ratio is approximately 59.09%, assuming the purpose and other requirements are met. A 10% book ratio does not answer the statutory FMV test.
The denominator and numerator must be supported on a consistent basis. Do not deduct corporate debt from a gross property value simply because the deal is priced using equity; the asset ratio and the later taxable-base rule are separate calculations.
Review the history
Suppose the ratio is 30% on the share-transfer date but was 60% two months earlier. If the actual conditions were met at that earlier point within the preceding 365 days, a low closing-date ratio does not by itself take the entity outside Article 2(h).
“365 days” is the operative period. Keep actual dates and evidence rather than substituting a fiscal year, an annual average or an assumption that only year-end accounts count.
Indirect and mixed holdings
Map indirect property holdings and the actual rights through the relevant entities. The wording includes indirect ownership, but it does not prescribe every calculation method for partly-owned chains or mixed assets. Explain the legal and valuation basis and avoid double counting the same property.
Do not turn uncertainty over an owner-used site into either automatic inclusion or guaranteed exclusion. Establish the actual purpose, rights and asset composition; where a conclusion needs an authoritative clarification, distinguish that unresolved point from what the express text already establishes.
The definition is not the tax charge
Once Article 2(h) is met, review the holding and related-disposal tests and actual exemptions. Particular securities and fund-unit provisions must also be considered where relevant.
If the transfer is taxable, Article 2(e)‘s valuation wording concerns property held directly or indirectly for any purpose. That taxable-base wording is not a reason to erase Article 2(h)‘s separate revenue-purpose condition.
Conversely, failure of this selected definition does not decide a separate direct property transfer or every other arrangement involving the same parties. Keep the company-definition conclusion, the actual disposal conclusion and the valuation calculation as separate parts of the file.
Key takeaways
- The entity's incorporation purpose is distinct from why it holds the Saudi property.
- The Article 2(h) numerator concerns Saudi property held for revenue through sale or leasing; the denominator uses total asset FMV.
- The threshold is at least 50% at transfer or at any time during the preceding 365 days.
- A book-value balance sheet and a transfer-date-only snapshot are insufficient.
- After the definition, apply the relevant holding/disposal rules, securities treatment and actual exemptions.
- An owner-occupied or mixed-property label alone does not answer every purpose and valuation question.
Frequently asked questions
Does meeting the 50% test make every share transfer taxable?
No. The definition is one gate. Apply the relevant holdings, related or concerted disposals and any actual exemption or specific securities treatment.
Does the company's incorporation purpose override the property purpose?
No. Law Article 1's regardless-of-incorporation-purpose wording must be read with the property revenue-purpose condition in the Law and Regulations. They concern different facts.
Can property be sold immediately before the share sale to avoid the definition?
Article 2(h) includes any time in the preceding 365 days, not just the transfer-date ratio. Review actual historical FMV and purpose evidence.
Sources
Reviewed against the Arabic RETT Law and Implementing Regulations on 20 November 2026. ZATCA's Detailed Guideline version 6 (May 2026) is explanatory; its English text does not override the Arabic instruments. Dariba is independent of ZATCA. General information, not advice on a specific transaction.