In brief
Official subdivision and qualifying partition are distinct Article 2(k) cases. Partition requires the prescribed deed, all owners recorded on one deed for the same property, a division reflecting their rights, and no consideration between owners.
Co-owners often want separate plots and deeds. The result under RETT depends on what happens to their property rights, how the partition is documented and whether consideration is due. “Splitting the land” can describe legally different arrangements.
What Article 2(k) does
Article 2(k) of the Implementing Regulations for the Real Estate Transaction Tax Law, issued by the Zakat, Tax and Customs Authority (ZATCA), distinguishes official subdivision through the competent authorities’ procedures from a qualifying partition of jointly owned property.
For partition, the provision requires an ownership deed issued by a notary public or accredited certifier, and all three of these conditions:
- All owners’ ownership is established in one deed for the same property.
- The property ownership after division reflects each owner’s rights recorded in that deed.
- No consideration is due from one owner to another in relation to the partition.
Meeting those conditions takes that qualifying partition outside the real estate transaction definition. It is different from charging a transaction and then applying an Article 3 exemption.
Subdivision and partition are different operations
| Operation | What to establish |
|---|---|
| Official subdivision | The property is subdivided through the competent authorities’ procedures. In ZATCA’s example the original owners continue to co-own each resulting plot in the same shares. |
| Partition ending co-ownership | Each owner takes an individual part. Test the prescribed deed and all three conditions, rather than assuming the subdivision procedure alone settles the result. |
| Transfers associated with either process | Identify any separate sale, gift, exchange or other transfer of ownership rights and apply its own scope and relief analysis. |
A new set of plot numbers does not itself prove ownership moved between persons. Equally, an official subdivision does not exempt an accompanying sale of a resulting plot.
ZATCA’s official examples
ZATCA’s Detailed Guideline for the Real Estate Transaction Tax, Version 6, section 3.3, Examples 4 and 5, printed page 14, provides two illustrations.
In Example 4, four persons each own 25% of land under one deed. The land is subdivided into three plots and three deeds through the competent authority, and all four continue to own 25% in each plot. The guideline treats this as outside the scope.
In Example 5, four brothers each own 25% of a 1,000 m² property under one deed. Through the prescribed procedures it becomes four equal 250 m² plots, with a separate deed for each brother and no compensation or financial consideration between them. The guideline treats that partition as outside the scope.
Those facts should be retained. The example does not establish a universal rule that equal square metres settle every unequal-value or unequal-rights arrangement.
Dariba examples: value, payment and actual rights
A matching division
Assume three siblings each own one third of the same SAR 9 million property under the required single deed. Each receives a plot worth SAR 3 million, the resulting rights reflect the recorded interests, the prescribed partition deed is issued and no consideration is due between them. On those assumptions, Article 2(k) can apply.
Unequal plots and a balancing payment
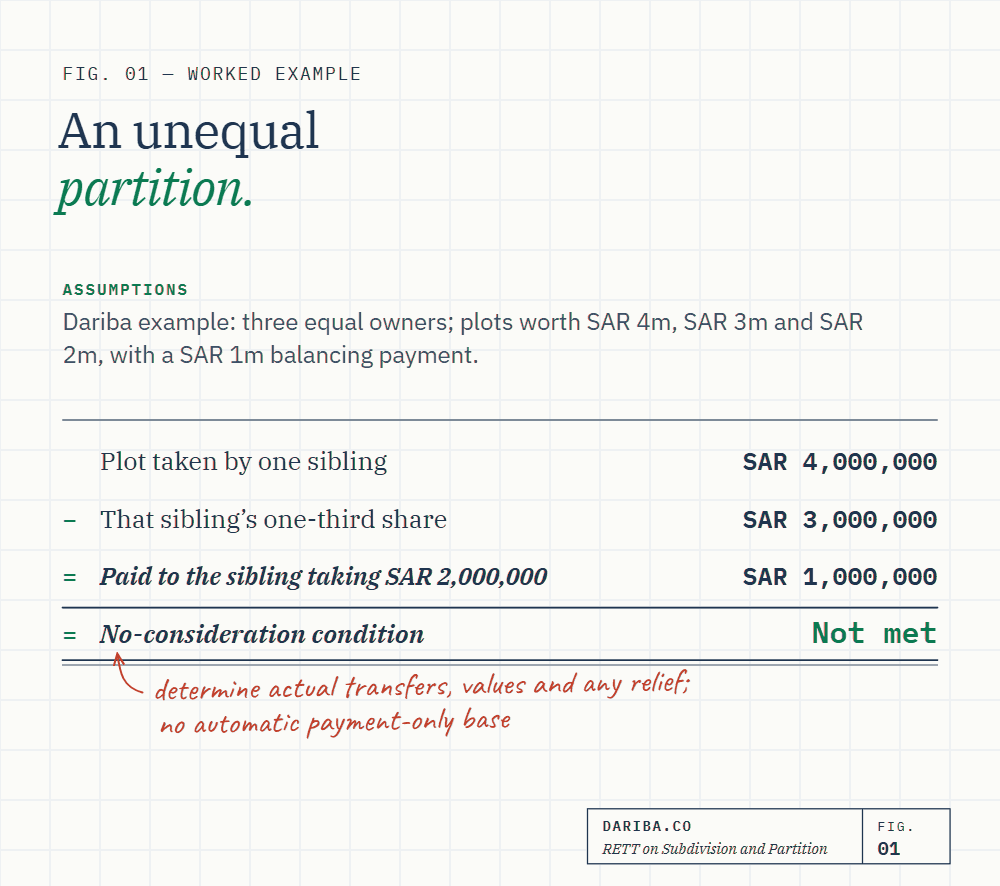
Assume instead the three resulting plots are worth SAR 4 million, SAR 3 million and SAR 2 million. The owner taking SAR 4 million pays SAR 1 million to the owner taking SAR 2 million.
The no-consideration condition fails. Article 2(k) does not then state that RETT is necessarily 5% of the SAR 1 million payment, nor that only an “excess” interest can be taxed. Analyse the actual rights transferred, the arrangements between all parties, the relevant property values and any other applicable relief.
Separate arithmetic illustration: if the completed legal and valuation analysis establishes a particular taxable property-interest transfer with a proper SAR 1 million base and no relief, its tax is SAR 50,000. That conditional calculation is not a statutory safe harbour for the unequal partition. The former diagram’s “at least SAR 50,000” conclusion has therefore been replaced.
Re-cutting plots can change the facts, but does not guarantee exclusion. The prescribed deed, reflected rights and absence of consideration still need to be established. Separately labelling a payment as a sale also does not, by itself, establish its tax base or cure the rest of the arrangement.
Equal area with different characteristics
If one resulting plot has valuable street frontage and another has restricted access, equal area may not settle whether the partition reflects the original rights. Retain evidence of those rights, the division methodology, values and any benefits or obligations assumed.
A difference in value is not automatically a finding of concealment under Article 6. Apply the actual rules for deceptive and hidden transactions to the evidence rather than treating every uneven partition as abuse.
If this exclusion does not apply
Owners holding different properties under separate deeds cannot simply treat an exchange as the same-property partition described in Article 2(k). Failure of that condition does not establish that every possible transaction must ultimately bear tax. Identify the actual transfers and test independent exemptions.
For inherited property, Article 3(a)(1) separately addresses a qualifying division of a deceased estate. Distinguish that process from an heir’s later purchase of another heir’s already allocated property. See the estate division guide.
Where a transfer is taxable, apply the appropriate consideration and FMV rules to the actual transaction. The practical sequence is to map the rights before and after, identify consideration, test Article 2(k), then determine any charge and independent relief.
Key takeaways
- Official subdivision does not itself establish that every associated transfer between owners is outside RETT.
- Qualifying partition requires the prescribed deed and all three Article 2(k) conditions.
- The resulting property rights must reflect the rights recorded in the original deed; equal area alone is not a universal test.
- A balancing payment defeats the no-consideration condition, but does not itself prescribe a tax base equal only to that payment.
- If Article 2(k) fails, examine actual property transfers, values and any independent relief, including a qualifying estate division.
Frequently asked questions
Does ZATCA's equal-area example mean valuation never matters?
No. Example 5 describes four equal owners receiving four equal 250 m² plots from a 1,000 m² property without compensation. Apply those actual facts alongside the requirement that resulting ownership reflects the original rights.
Is RETT automatically 5% of a partition balancing payment?
No. The payment can cause Article 2(k)'s no-consideration condition to fail, but that provision does not establish a universal payment-only tax base. Identify the actual transfers and applicable valuation and exemption rules.
Are inherited-property partitions always taxable if this exclusion fails?
No. A qualifying division of a deceased estate has a separate Article 3(a)(1) exemption. Establish its own facts and limits rather than treating failure of one route as failure of every possible relief.
Sources
Based on the RETT Law (Royal Decree No. M/84, effective 10 April 2025), the RETT Implementing Regulations (ZATCA Board Resolution No. 01-03-25 dated 24 March 2025, unofficial English translation) and ZATCA's Detailed RETT Guideline Version 6 (May 2026). The Arabic text prevails. This article is general information, not advice on any specific transaction. dariba.co is an independent knowledge platform and is not affiliated with ZATCA.