In brief
Article 2(l) supplies conditional treatment for linked financing transfers. The contracts must identify both transactions and the relevant parties, property and value; do not replace the stated conditions with either a universal product exemption or literal identity of seller, bank and customer.
Article 2(l) of ZATCA’s RETT Implementing Regulations addresses transactions taxed only once and includes specified linked financing transfers. Its protection depends on the actual facts and conditions, not a promise that every financed property can incur only one RETT charge throughout its life.
Read the financing conditions together
For the stated Murabaha, Ijarah-to-own and finance-lease arrangements, establish:
- The first real-estate transfer to the legally licensed financing entity is subject to tax.
- The financing contracts identify both transactions, their parties, the real estate and the value.
- The property’s description and value remain as included in the financing contracts.
The general unity-of-parties/property/value principle should not be applied in isolation to reject every financing chain because it contains a seller, bank and customer. ZATCA’s Detailed RETT Guideline, Version 6, section 5.2, printed page 49, expressly explains the treatment of identified different parties within the linked financing legs.
Conversely, a general economic description of one financed purchase does not replace the contract conditions or first-transfer tax evidence.
The official examples
Example 6, printed page 15, concerns a SAR 1 million apartment bought through a finance lease. The bank pays tax on the illustrated initial acquisition, and title passes to the customer at completion without a new charge on those facts.
The payment description is not a universal taxpayer rule. Identify the statutory transferor under Law Article 7 even where a bank or customer funds the payment.
Example 62, printed page 49, concerns an Islamic Ijarah with the developer paying 5% RETT on 5 December 2020 and the customer receiving final title in 2030. Keep that first-transfer tax fact and linked financing context. The example is not an unconditional assurance about any future arrangement.
Dariba illustration: the villa financing
Assume a SAR 2.5 million proper taxable property value, a legally licensed financier and a qualifying linked Ijarah whose Article 2(l) conditions are established. Assume total payments of SAR 3.6 million, including SAR 1.1 million of identifiable financing-term cost.
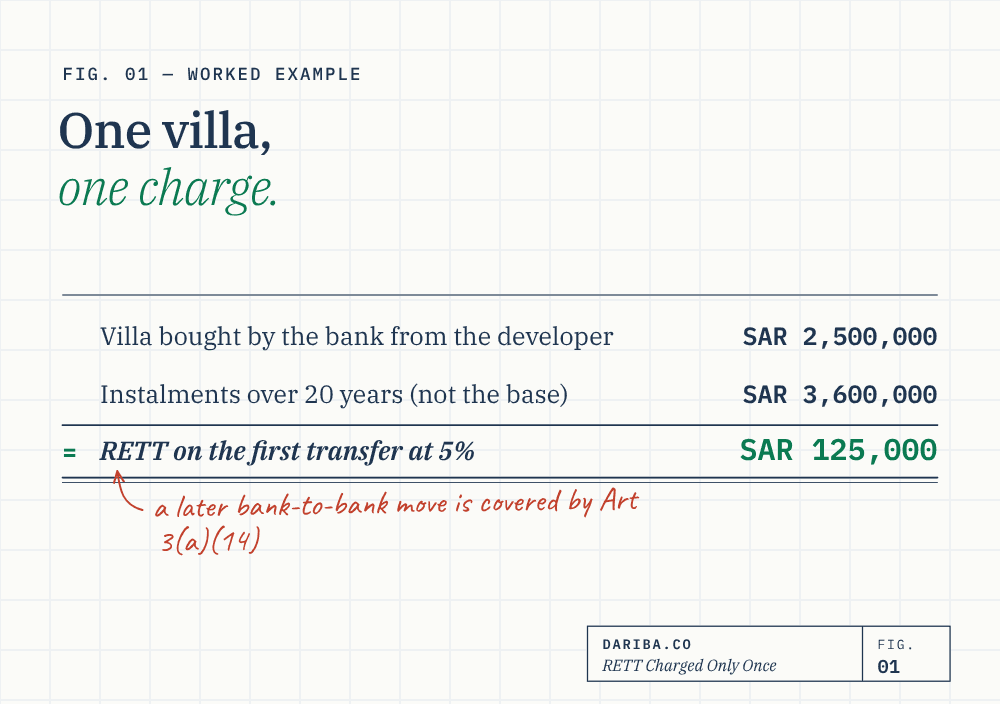
| Item | Illustrative amount |
|---|---|
| Proper property base | SAR 2.5 million |
| Financing-term cost within the assumed payment total | SAR 1.1 million |
| Total payments | SAR 3.6 million |
| Tax on the assumed proper property base at 5% | SAR 125,000 |
Law Article 2(2)‘s financing-term cost exclusion is a separate valuation rule. A 5% charge on the entire payment total would be SAR 180,000, but that calculation does not follow where the assumed licensed-financing exclusion applies. It would overstate this illustration’s charge by SAR 55,000.
Do not establish the property base solely by subtracting anything labelled profit from the payment total. The actual property consideration, fair-market-value position and nature of the financing cost must be supported.
Changes during financing
Read an amendment to identify what actually changed. A revised instalment schedule or financing cost is not automatically a revised property value. Equally, substituting a beneficiary, acquiring a different property or undertaking a new sale needs analysis against the actual conditions.
If the selected Article 2(l) route is not established, assess the resulting transaction and other relief; do not jump directly to a universal second charge. In particular, qualifying bank-to-bank refinancing can engage Article 3(a)(14), as shown in Examples 33–34. Neither automatic taxation nor automatic exemption follows merely from a change of bank.
Early settlement is also a facts-and-contract question. An earlier completion date does not itself appear as an independent disqualifying condition in Article 2(l), but the actual transaction must still meet the rule.
Distinguish old lease relief and keep evidence
The historical lease rule in Royal Decree M/84, Clause Fifth(1), uses the RETT inception date 14/2/1442 AH, 4 October 2020, for the stated contracts. It is distinct from both the current taxed-once route and the April 2025 Law commencement.
Register the actual transfers as required, retain the financing contracts and first-transfer tax evidence, and preserve the value/cost split and amendments. Article 11(f)‘s five-year record period runs from the relevant transaction date, not automatically five years after the financing ends.
See the Islamic-finance overview and temporary-security guide for the other routes.
Key takeaways
- The actual first-transfer tax and linked financing documents matter; Murabaha/Ijarah labels are insufficient.
- The guideline's financing treatment accommodates the identified different parties in the linked legs.
- An amendment to payment terms is not automatically a change in the underlying property's description or value.
- Failure of the selected taxed-once route does not automatically exclude all other relief.
- Refinancing may fall within Article 3(a)(14), but the bank-to-bank label alone establishes nothing.
- Example 62's first transfer was on 5 December 2020; preserve its facts rather than convert it into a universal future assurance.
Frequently asked questions
How can the parties be the same if the seller sells to the bank and the bank transfers to the customer?
The general unity principle must be read with Article 2(l)'s financing conditions and the guideline's specific financing explanation. Section 5.2 discusses identified different parties within linked financing transfers. The seller, bank and customer need not literally be one person; the actual chain must be documented and satisfy the relevant conditions.
Does any financing amendment automatically cause another RETT charge?
No. Identify what changed and its effect on the actual conditions, property, value and parties. A change in financing cost or repayment timing is not automatically a change in the property's stated value. If a route is not established, test the resulting actual transaction and any other relief.
Does the first-transfer rule automatically apply if the initial transfer was exempt?
Article 2(l)'s stated financing conditions include the first transfer being subject to tax. Do not assume this financing route has been established where that fact is absent. Determine the actual applicable relief and complete transaction chain instead of promising a general exemption for the final transfer.
Does Example 6 make every bank the statutory taxpayer?
No. It describes the bank paying tax on the illustrated sale. Who funds or processes payment is distinct from Law Article 7's identification of the responsible transferor and beneficial person.
Sources
- ZATCA — Real Estate Transaction Tax Law (Arabic), Articles 2(2)–(3), 5 and 7
- ZATCA — RETT Implementing Regulations (Arabic)Articles 2(l), 3(a)(14)–(15) and 11
- Royal Decree M/84, RETT issuing instrument (Arabic)Clause Fifth(1), PDF page 2: pre-14/2/1442 AH lease contracts
- ZATCA — Detailed RETT Guideline, Version 6, May 2026Sections 3.4, 4.2, 5.1.9–5.1.10 and 5.2; Examples 6, 9, 31–35 and 62
Reviewed against the controlling Arabic RETT Law, Implementing Regulations, the operative issuing decree and ZATCA's Detailed RETT Guideline Version 6 (May 2026). Guidance does not amend legislation. Historical transactions need their applicable facts and period. Dariba illustrations assume their stated values and eligibility; general information, not transaction-specific advice.