In brief
The treaty uses separate project, service and natural-resource thresholds. Its related-enterprise rule aggregates connected work and counts concurrent activity once.
A Croatian contractor and its related company might divide work on a Saudi installation between two contracts. Article 5(3) of the Saudi–Croatia Double Taxation Agreement directs them to review the full timeline when their local work is connected.
| Activity | Treaty provision | Duration test |
|---|---|---|
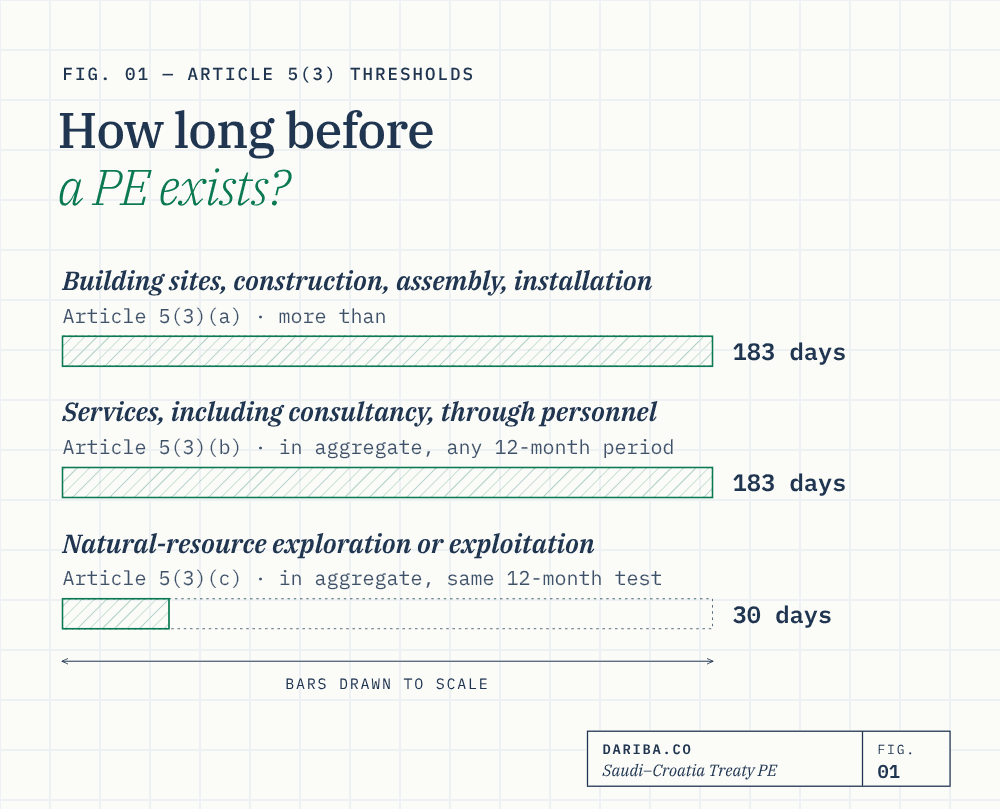
| Building sites, construction, assembly, installation and associated supervision | Article 5(3)(a) | More than 183 days |
| Services, including consultancy, provided through personnel | Article 5(3)(b) | More than 183 days in aggregate in any 12-month period beginning or ending in the fiscal year concerned |
| Activities connected with exploring or exploiting local natural resources | Article 5(3)(c) | More than 30 days in aggregate using the same fiscal-year-linked 12-month test |
Count overlapping work once
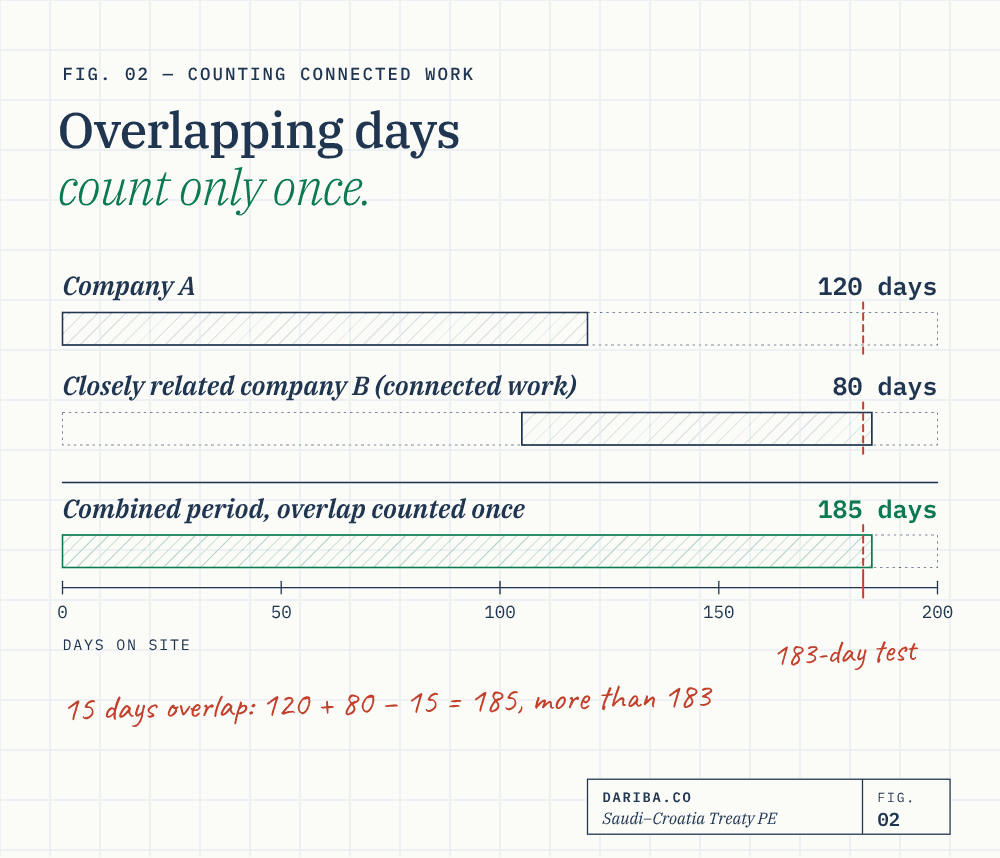
Article 5(3) aggregates connected activities by closely related enterprises in the same treaty state and counts concurrent work only once. If one company works 120 days and a closely related company does 80 days of connected work with a 15-day overlap, the combined period is 185 days. For work that fits the construction limb, that period exceeds 183 days. Check the connection between activities against the contracts, site records and responsibilities. Article 5(9) defines when parties are closely related.
Review local premises and signing practices
The fixed-place route and the activity exemptions can matter independently of the project timetable. Article 5(5) can remove an activity exemption where local activities are complementary functions of a cohesive business operation and the other conditions are met. Article 5(6) covers specified contracts routinely concluded without material changes after a local representative plays the principal role, as well as a separate local stock and delivery route. Review the independent-agent rule in Article 5(7).
Attribute profit to the establishment
Article 7 generally limits source taxation of business profits under that article to profit attributable to the permanent establishment as a separate enterprise. It provides for an appropriate corresponding adjustment in specified cases, identifies deductible expenses and restricts specified internal charges. Article 7(5) preserves domestic taxation of insurance and reinsurance income or profit. If covered profits are remitted to head office, check Article 10(6) in the withholding guide.
Key takeaways
- Article 5(3) sets a threshold above 183 days for specified projects and services and above 30 days for specified natural-resource work.
- Connected activity by closely related enterprises can count towards all three thresholds.
- Article 5(5) limits activity exemptions when complementary functions form a cohesive business operation.
Sources
- Saudi–Croatia Agreement for the Avoidance of Double Taxation with Respect to Taxes on Income and on Capital and the Prevention of Tax Evasion and AvoidanceArticles 5, 7, 14 and 30.
- ZATCA Treaty Register, Croatia ConventionApplication from 1 January 2026.