In brief
The agreement caps qualifying dividends and debt income at 5% and royalties at 10%. It separately addresses branch remittances and defined sovereign investments.
The Saudi–Croatia Double Taxation Agreement entered into force on 24 June 2025. Article 30 applies its withholding provisions to amounts paid from 1 January 2026. A Saudi payer should confirm which treaty provision covers the payment and whether the recipient qualifies for relief.
| Payment | Treaty provision | Source-state ceiling |
|---|---|---|
| Qualifying dividends | Article 10(2) | 5% of gross dividends |
| Qualifying debt-claim income | Article 11(2) | 5% of gross income |
| Qualifying royalties | Article 12(2) | 10% of gross royalties |
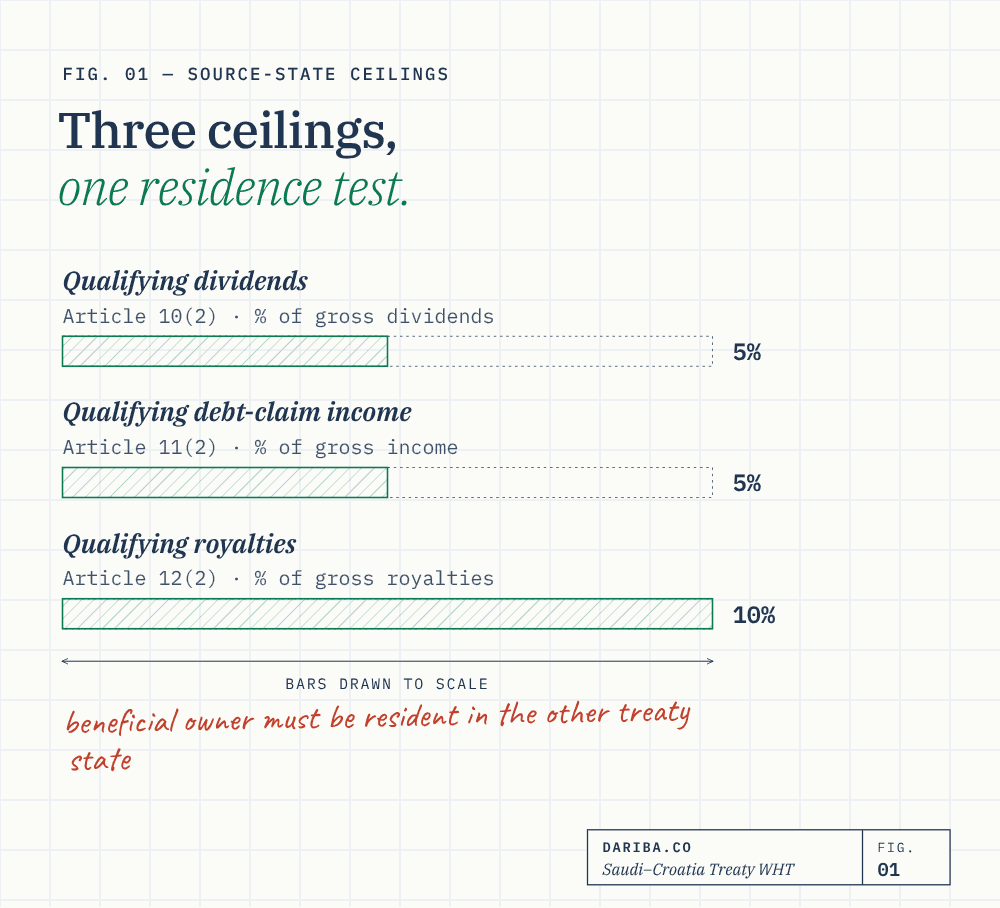
These ceilings require a beneficial owner resident in the other treaty state. Article 12(3) includes specified intellectual property, equipment rights and know-how. Review effective connection to a local permanent establishment or fixed base and apply the special-relationship rule to excess debt or royalty payments. For a fiscally transparent entity or arrangement, Article 1 looks at the extent to which a treaty state treats the income as its resident’s income.
Calculate branch remittances using after-tax profit
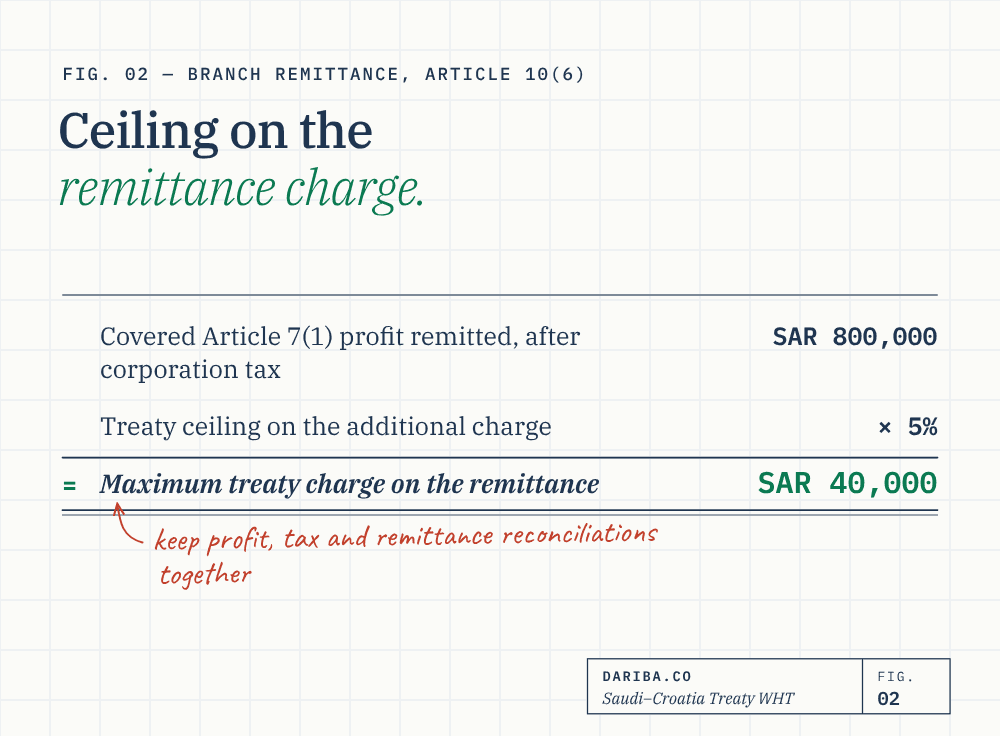
Article 10(6) permits an additional withholding charge under domestic law when covered Article 7(1) profits are remitted to head office. The ceiling is 5% of the covered profit after corporation tax imposed on that profit in the source state. For example, if a remittance consists of SAR 800,000 of covered profit after corporation tax, the treaty ceiling on that charge is SAR 40,000. Keep the profit, tax and remittance reconciliations together. See the permanent establishment guide for the profit attribution rules.
Verify the investor before applying Article 22
Article 22 assigns taxing rights over specified sovereign investments and their Article 10 and 11 income to the investing state. Its definitions identify covered public bodies, named investors, certain wholly owned entities and similar entities agreed by the competent authorities through an exchange of notes. For Saudi Aramco, the listed route requires at least 80% direct or indirect ownership by the persons identified in Article 22(2)(a). Determine the actual investment holder and trace the relevant ownership chain.
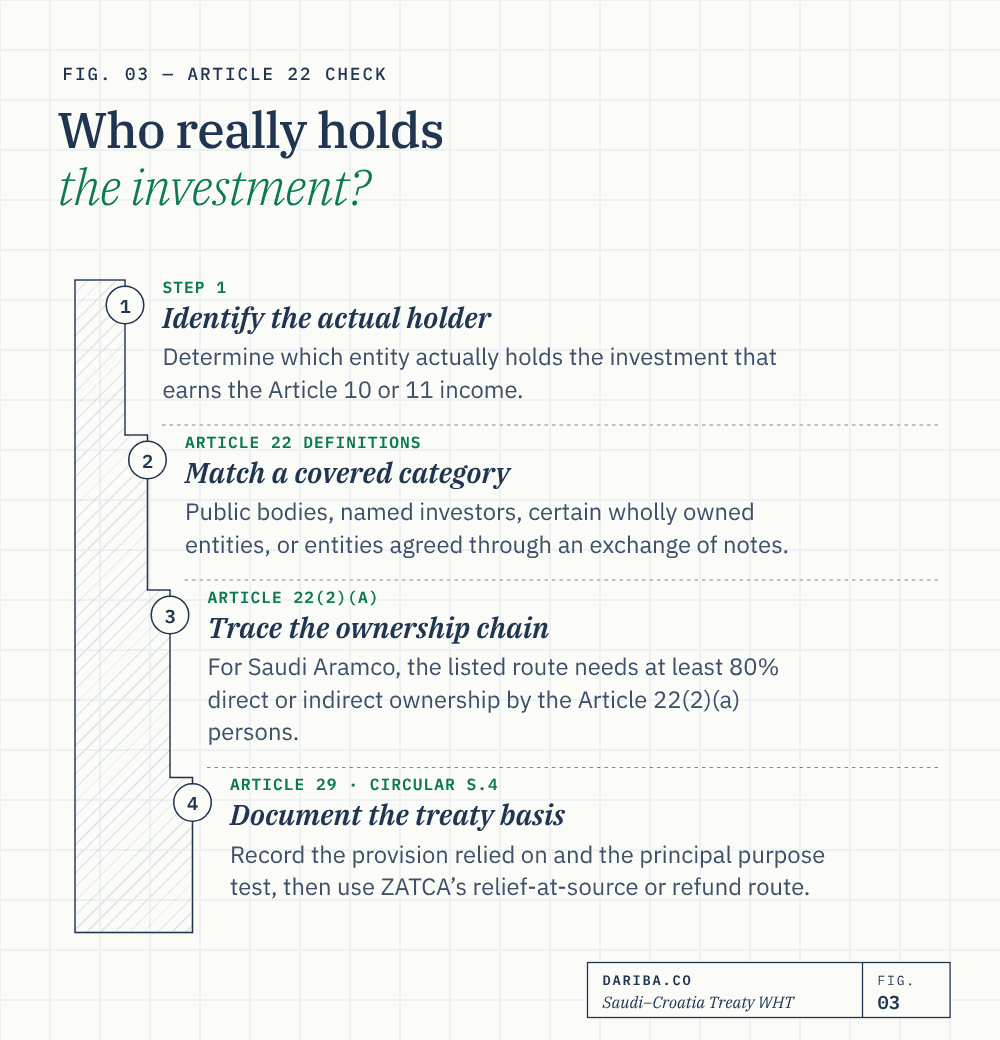
Document the treaty basis for the payment, including Article 29’s principal purpose test. Section 4 of ZATCA’s Tax Circular on Implementation of Withholding Tax Under the Double Taxation Agreement sets out the Saudi relief-at-source and refund routes.
Key takeaways
- The withholding provisions apply to amounts paid from 1 January 2026.
- Article 10(6) caps the additional withholding on qualifying branch profit remittances at 5% after corporation tax.
- Article 22 reserves taxation of specified investment income to the investing state.
- Article 29 sets the treaty’s principal purpose test.
Sources
- Saudi–Croatia Agreement for the Avoidance of Double Taxation with Respect to Taxes on Income and on Capital and the Prevention of Tax Evasion and AvoidanceArticles 1, 10–12, 22 and 29–30.
- ZATCA Treaty Register, Croatia ConventionEntry into force and application dates.
- ZATCA Tax Circular on Implementation of Withholding Tax Under the Double Taxation AgreementSection 4 on relief at source and refund claims.