In brief
Pakistan’s convention distinguishes company/government-related dividends from other dividends, contains specific debt-claim exemptions and limits qualifying royalties. Actual classification, PE and MLI conditions matter.
A Pakistan Payment Needs More Than a Country Rate
Start with the payment’s Saudi source and domestic income category. The Saudi–Pakistan convention then limits or allocates taxation for an entitled resident where its conditions apply. A country name on a bank instruction does not establish residence, beneficial ownership, classification, absence of a PE or relief procedure.
The convention was signed on 2 February 2006. Pakistan’s Federal Board of Revenue publishes both the original convention and a synthesis prepared jointly with Saudi Arabia showing MLI changes. The synthesis is an explanatory aid; authentic convention and MLI provisions, reservations and notifications control. The original convention’s Arabic and English texts are equally authentic.
Compare the Ceilings with the Actual Domestic Charge
The following are treaty measures for the stated qualifying cases. A ceiling does not raise a lower correctly established domestic Saudi rate.
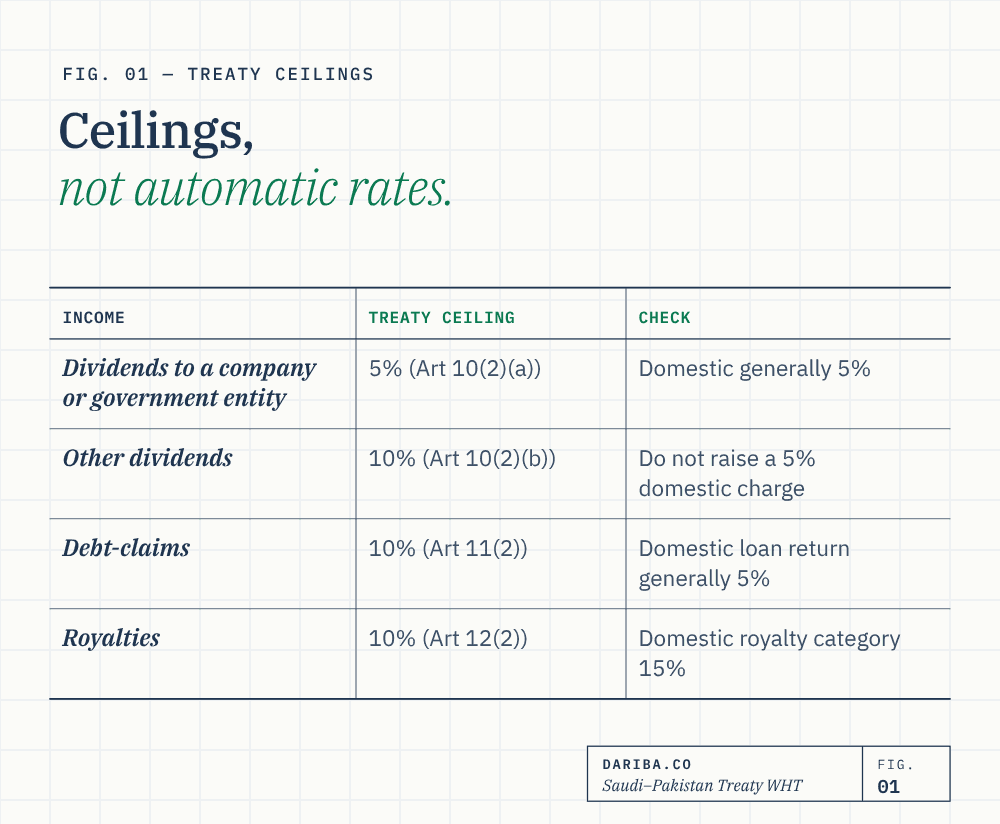
| Income | Convention treatment | Practical domestic comparison |
|---|---|---|
| Dividends to a qualifying beneficial owner that is a company or wholly government-owned entity | Article 10(2)(a): 5% of gross dividends | The ordinary domestic dividend category is generally 5% |
| Other qualifying dividends | Article 10(2)(b): 10% ceiling | Do not increase an applicable domestic 5% charge to the treaty ceiling |
| Debt-claim income | Article 11(2): 10% ceiling; paragraph 3 has specified exemption limbs | A correctly classified ordinary domestic loan return is generally 5% |
| Royalties | Article 12(2): 10% ceiling for the qualifying beneficial owner | Compare with the domestic 15% royalty category; equipment and other domestic categories require actual classification |
| Corporate service income | Article 7, subject to specific provisions and PE facts | Domestic technical, management and residual categories remain the starting point; treaty relief requires its own support |
Income Tax Law Article 68 and Implementing Regulations Article 63 supply the relevant domestic framework. See Saudi withholding tax for those categories.
Dividends Distinguish the Recipient’s Status
The 5% treaty ceiling applies where the beneficial owner is a company or an entity wholly owned by the government, under Article 10(2)(a). The ordinary paragraph does not impose a minimum ownership percentage borrowed from a different treaty. The other dividend cases have a 10% ceiling.
That government-related wording is a 5% dividend limb, not the Saudi–China agreement’s separate government dividend exemption. Do not transplant one country’s benefit into this convention because both recipients have public ownership.
Article 10(4) addresses a holding effectively connected with the specified PE or fixed base, moving the analysis to Article 7 or 14 as appropriate. Taxation of the distributing company’s profits also remains separate from the shareholder-level ceiling.
Debt-Claims Have Specific Exemption Limbs
Article 11(2) gives the ordinary 10% gross ceiling for the qualifying beneficial owner. That does not justify withholding 10% where the applicable Saudi domestic loan-return category is 5%.
Paragraph 3 separately concerns the specified government, wholly government-owned entity, central-bank and government-approved-loan cases. Establish the actual recipient or approval and the convention’s conditions. A commercial loan involving a public-sector connection does not establish an exemption by its label alone.
The definition includes the stated debt claims and securities income but excludes late-payment penalty charges. Effective PE/fixed-base connection and special-relationship excess amounts have separate consequences. Separate principal, actual financing return and independent fees rather than applying the same rate to every payment under a financing agreement.
Royalties Include Rights, Know-How and Equipment Use
Article 12(3) includes the specified copyright and intellectual-property rights, industrial/commercial/scientific equipment use and information concerning industrial, commercial or scientific experience. Its 10% ceiling depends on the beneficial-owner and other treaty conditions.
Classify the actual consideration. An independent technical service is not necessarily transferred know-how; a software label does not prove exploitation rights; equipment use may have a different domestic category from its treaty definition. A ceiling does not create a higher charge than the applicable domestic law.
Article 12(4) addresses effective PE/fixed-base connection. Paragraphs 5–6 address source and excess consideration from special relationships. Genuine pricing support therefore matters alongside residence and the named royalty article.
Dariba arithmetic illustration: assume SAR 200,000 is genuine Saudi-source royalty consideration, the domestic 15% category applies and all conditions for the 10% convention ceiling and procedure are met. Domestic WHT is SAR 30,000; the treaty ceiling is SAR 20,000, a difference of SAR 10,000. This is an original illustration, not an official worked case or a conclusion for a real software or mixed-services contract.
Services, Merchandise Exports and Insurance Differ
Article 7 generally applies the residence-state rule for enterprise profits unless business is carried on through a PE, with source taxation limited to attributable profits. Paragraph 10 preserves separately dealt-with income articles.
Article 7(3) specifically addresses profits from merchandise exports to the other state and distinguishes other activities in export contracts performed there. An equipment export with on-site installation therefore needs its genuine components and activities examined; a single invoice label does not make every element merchandise-export profit.
Paragraph 7 preserves the stated operation of domestic law concerning non-resident insurance profits, with its consultation condition if the law changes beyond minor respects. Do not promise zero WHT on every Pakistani insurer’s premium merely because no ordinary project PE is identified.
The Saudi–Pakistan PE guide explains the modified agency, activity and contract-splitting rules relevant to a corporate service claim. Independent personal services have their separate Article 14 framework.
Apply the MLI for the Relevant Tax Event
The joint synthesis identifies Saudi withholding-tax effect for relevant events on or after 1 January 2022, and other Saudi taxes for taxable periods beginning on or after 1 October 2021, subject to provisions with their separately stated timing. The Pakistan-side timing differs; a single general “MLI effective date” does not cover every case.
MLI Article 7’s principal-purposes test can deny benefits where obtaining them was one of the principal purposes of an arrangement or transaction, unless granting the benefit would accord with the relevant provisions’ object and purpose. A residence certificate does not displace that test or establish beneficial ownership by itself.
The PE changes also differ from China’s treaty position. Pakistan and Saudi Arabia’s matched treatment includes the broader agency rule, Option A activity-exemption conditions, anti-fragmentation and contract-splitting provisions. The actual payment file must reflect those facts before relying on enterprise-profit protection.
Retain the Classification, Presence and Relief Evidence
ZATCA’s treaty WHT circular explains that actual income qualification precedes selection of the treaty article. Preserve the contract and component values, payee identity, relevant residence evidence, beneficial-owner analysis where required, PE information, period and calculation, and the evidence needed for the actual relief route.
The relief-at-source and refund guide covers the general process. Do not assume that the existence of the convention automatically produces an exemption, that every certificate must have one universal advance date, or that a foreign tax credit is guaranteed. The result remains payment-specific and subject to the convention and procedure actually established.
Key takeaways
- Qualifying company or wholly government-owned dividend recipients have a5% ceiling; other cases have a10% ceiling.
- A treaty ceiling does not raise a lower domestic Saudi rate.
- Debt-claim exemptions require the actual government-related or approval conditions.
- The10% royalty ceiling requires the actual definition, beneficial owner and other treaty conditions.
- Merchandise exports, on-site activities and insurance have distinct Article7 provisions.
- Saudi MLI withholding timing starts from1January2022; other tax-period and provision timing differs.
Sources
- Pakistan tax authority: authentic Saudi–Pakistan agreement textArticles 4–5,7 and 10–12, language and final provisions; merchandise-export and insurance clauses retained.
- Pakistan tax authority: jointly prepared MLI synthesisReading aid for matched changes and effect dates. Authentic convention/Protocol and MLI prevail; visible original checked separately from extraction artefacts.
- OECD depositary: Pakistan deposited MLI positionCovered-agreement and selected MLI reservations/notifications matched with Saudi position. Agency, OptionA and contract-splitting choices matched.
- OECD depositary: Saudi Arabia’s deposited MLI positionMatched covered-agreement, reservations and notifications; unilateral choice alone does not modify a treaty.
- OECD: Multilateral Instrument, authentic English textApplicable benefit, PE and entry-into-effect provisions, subject to the parties’ reservations and notifications.
- OECD: current MLI signatories and partiesCurrent depositary listing and links to deposited positions; entry into force and entry into effect are distinct.
- ZATCA Tax Circular: Withholding Tax Implementation under Double Taxation AgreementsSection 3.2 distinguishes business profits, debt-claims, royalties, technical and personal services; actual treaty conditions and procedure govern.
- Saudi Income Tax Law, current Arabic publicationArticles 5 and 68: domestic source and withholding framework; treaty allocations require separate analysis.
- Saudi Income Tax Implementing Regulations, current Arabic publicationArticles 5 and 63: actual source/category, ordinary domestic rates and payment compliance conditions.
General information based on official treaty, MLI and Saudi sources reviewed on 29 October 2026. Authentic instruments, actual facts, payment or tax period, residence, beneficial ownership where required, presence and benefit conditions determine the result. Joint syntheses are reading aids. Dariba illustrations are original; no treaty entitlement, project status or procedural outcome is guaranteed.