In brief
The same marketplace may use several VAT workflows. Official Crafty, Bazaar, RiyadhCar, food-app and accommodation examples explain resale value, included margins, separate fees, supplier status, refunds and conditional recovery.
An online marketplace needs a VAT workflow that follows each transaction’s supplier and legal role. One platform can be principal for its own sales, deemed supplier for an unregistered resident seller, and disclosed intermediary for a registered seller. The practical challenge is connecting that classification to invoices, settlements, returns, refunds and input-tax evidence.
Build the transaction map before changing billing
Apply Article 47(2)–(4), Article 9 of the VAT Law and the actual supply/place rules. The deemed-supplier legal guide explains the different non-resident services and resident-unregistered rules and their exceptions. Do not treat every seller, fee or foreign booking as one category.
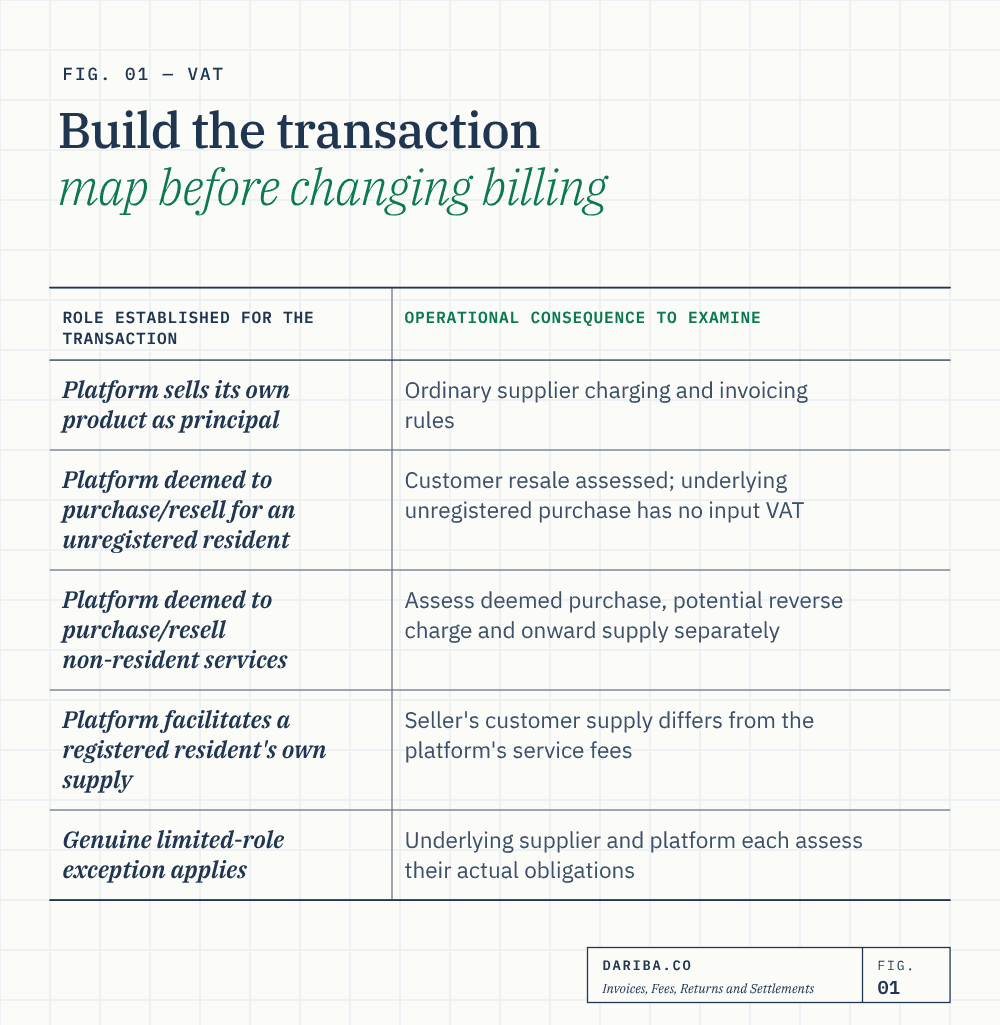
| Role established for the transaction | Operational consequence to examine |
|---|---|
| Platform sells its own product as principal | Ordinary supplier charging and invoicing rules |
| Platform deemed to purchase/resell for an unregistered resident | Customer resale assessed; underlying unregistered purchase has no input VAT |
| Platform deemed to purchase/resell non-resident services | Assess deemed purchase, potential reverse charge and onward supply separately |
| Platform facilitates a registered resident’s own supply | Seller’s customer supply differs from the platform’s service fees |
| Genuine limited-role exception applies | Underlying supplier and platform each assess their actual obligations |
This is Dariba’s operating map, not a substitute for the statutory tests. Seller status must be supported and valid at the relevant supply time; a platform’s standard contract does not make every row interchangeable.
Use official examples to reconcile gross sales and settlements
ZATCA’s Persons Liable to Pay Tax in Special Cases – Deemed Suppliers guideline, as retrieved on 22 October 2026, section 7.2, Example 6, pp. 35–36, describes Fatima selling pottery through Crafty. The sale price is SAR 1,800 excluding VAT; Crafty invoices SAR 2,070 including SAR 270 VAT, pays Fatima SAR 1,620 and retains the stated 10% commission within the deemed purchase/resale model.
Dariba analysis: the supplier settlement is not the customer taxable turnover. Reporting only the SAR 180 commercial margin as standard-rated sales would omit the actual SAR 1,800 resale value. The unregistered purchase also does not create an input VAT credit simply because the platform has a sales document.
Keep separate reconciliation columns for the VAT-exclusive resale, customer VAT, customer collection, deemed purchase/settlement, transaction margin and independent fees. A bank receipt or net payout alone cannot support the entire VAT return.
Distinguish included margin from separate services
Section 8.2, p. 48, treats the difference between deemed purchase and resale as the platform’s margin where it represents facilitation of that supply. It is already included in the customer resale and is not separately charged as the same commission again. The rule is conditional on that actual role and transaction.
Independent subscriptions, advertising or other services can remain separate supplies. Example 7, pp. 36–37, gives Bazaar’s SAR 150 net cup sale: SAR 15 commission and SAR 20 transaction delivery deduction leave SAR 115 paid to Hamza. These direct transactional items are included in the model described; additional inventory/packaging services outside the customer price require their own invoice. After Hamza becomes registered, the seller/platform invoicing changes.
Section 8.2, Example 8, pp. 49–50, provides a different useful illustration: RiyadhCar pays unregistered driver Ahmad SAR 32 from a SAR 40 net fare after an SAR 8 commission. The passenger also pays a SAR 1 booking service fee. Total taxable consideration is SAR 41, VAT SAR 6.15 and total SAR 47.15. Do not read the no-second-commission rule as eliminating VAT on that separate booking charge.
Split food and delivery according to the real suppliers
The guideline section 9.1, pp. 61–67, shows why a food app cannot use one supplier status for the whole order. A registered restaurant’s meal, an unregistered delivery provider’s service and the app’s own fees can have different invoicing responsibilities. An app directly supplying delivery as principal also needs that role identified.
Example 13, pp. 65–67, concerns registered Salad Café. The restaurant’s meal invoice is SAR 115 including SAR 15 VAT. The app separately invoices its SAR 20 service fee plus SAR 3 VAT to the café, and charges the customer SAR 5 delivery/processing plus SAR 0.75 VAT. It collects SAR 120.75 including the meal amount on the café’s behalf. The sample documents use 12 January 2027; that is an illustrative example date, not evidence of a transaction already occurring.
Dariba analysis: cash collection on behalf of the restaurant does not make its VAT the app’s output VAT or input VAT. The reconciliation should identify whose invoice and whose tax each amount represents. Payment handling and the legal supply can differ.
Review accommodation and multi-platform arrangements
Section 10, Example 15, pp. 70–71, describes Ahmad offering his furnished home for holiday stays through Staybooking.com. The platform confirms bookings, arranges collection and handles complaints. On the stated resident-unregistered facts, it is deemed supplier. The example does not make every permanent residential lease taxable merely because an online listing exists.
Closely related accommodation charges, genuine separate optional supplies and services supplied directly without platform involvement require their actual treatment. See the residential and serviced accommodation guides for the underlying classification.
Section 10.1, Example 16, p. 73, distinguishes BestRates’ comparison/redirection role from BookStay’s booking role. The section also addresses which platform contracts with the customer and any explicit identification of another responsible marketplace. Do not allocate the same customer supply to every intermediary in the chain simply because each receives a commercial fee.
Configure returns and input claims by legal leg
Sections 6.2, 7.2 and 8.2, pp. 23, 34 and 46–47, distinguish marketplace residence, customer registration and the deemed purchase. A resident platform’s imported-service purchase may require reverse charge on the net amount remitted to the non-resident underlying supplier, while the onward taxable resale uses full customer consideration excluding VAT.
Dariba illustration — original assumptions: a resident registered platform makes a wholly standard-rated resale for SAR 1,000 excluding VAT and has a qualifying deemed non-resident service purchase of SAR 700. Resale VAT is SAR 150; purchase reverse-charge output is SAR 105. If all input conditions permit deduction, the SAR 105 input offsets that purchase output, leaving SAR 150 net on these transactions. It is not a special scheme charging VAT only on the SAR 300 commercial margin.
For a non-resident platform supplying a Saudi registered taxable customer, customer reverse charge can still apply. Do not disable it merely because the platform is deemed supplier. Conversely, an unregistered resident underlying purchase has no deductible VAT. Section 8.3, pp. 54–55, also says an invoice for a registered seller’s direct customer supply does not become the platform’s input invoice just because it passes through the platform.
Distinguish cancellation from compensation and bad debt
Section 8.4, Example 10, pp. 57–58, concerns Rania’s uncompleted ServiceHub cleaning booking: a SAR 1,150 refund including SAR 150 VAT and the platform’s credit note for the cancelled supply. Match the actual cancellation, note and return treatment under Articles 40 and 54.
Section 9.2, Example 14, pp. 68–69, gives a different result when CoffeeHub correctly supplies coffee but the delivery provider spills it. The restaurant’s invoice remains valid and the app’s customer compensation does not automatically cancel the restaurant’s supply or VAT. A separately charged administration service to the delivery provider has its own treatment.
Unpaid consideration is another issue. Section 8.6, p. 60, refers to Article 40(7)‘s actual bad-debt conditions; a customer complaint, platform credit or failed collection is not automatically a bad-debt deduction. Free promotions also need the nominal-supply rules rather than an assumption that all free platform-funded items generate the same VAT.
Preserve the evidence and manage status changes
Section 7.5, p. 42, requires reasonable residence/registration verification and actual practice reflected in contracts. Retain supplier identity/TIN checks, effective status changes, terms, customer orders, invoices, credit notes, payout calculations and role decisions. Reconcile the transaction ledger to the return rather than forcing mixed supplies into one net commission total.
Sections 8.1–8.3, pp. 43–55, address registration, invoicing, returns, records and conditional input recovery. Resident and non-resident platforms can have different obligations, including the e-invoicing population. Apply current requirements to the actual operator rather than assuming every foreign platform follows the resident workflow.
Dariba recommends a documented review whenever the seller registers, the app takes over complaints or fulfilment, the customer becomes a registered business, or the contract model changes. These controls help implement the law; they are not an invented ZATCA certification procedure or a guarantee that every platform transaction is standard-rated.
Key takeaways
- Customer resale value, supplier settlement and retained margin are different amounts.
- No second VAT charge on the same included facilitation margin does not mean tax applies only to that margin.
- Independent platform services, registered-seller agency and customer booking charges require their actual treatment.
- A meal, delivery service and platform fee can belong to different suppliers and VAT obligations.
- Cancellation, compensation, promotions and bad debt require different legal analyses.
- Verify residence and active registration, retain the transaction chain and reconcile each legal leg to the return.
Sources
- Controlling Arabic VAT Implementing RegulationsTenth edition April 2025. Articles 15,17,39,47,49-54,63,66: actual free supplies, transfer conditions, valuation, distinct marketplace exceptions, deduction and documentation.
- Official Arabic VAT LawArticle 9 own-name acting on behalf of another: principal/agent analysis remains relevant independently of marketplace deeming.
- ZATCA Deemed Suppliers guidelineOfficial75-page file retrieved22October2026; cover has no edition/date. Sections 5-8 pp. 14–60, food section9 pp. 61–69, accommodation section10 pp. 70–73, transition section11 p. 74. Actual Arabic Article 47 controls discrepancies.
- ZATCA Input Tax Deduction guidelineThird version May2026. Actual entitlement, restricted costs, direct/shared inputs and evidence remain relevant to nominal, transfer and marketplace analyses.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.