In brief
Identify the actual tariff and agreement, then establish origin and the correct evidence/claim route instead of assuming a universal rate or certificate-only exemption.
Preferential Saudi customs treatment starts with the actual tariff line, import date and applicable agreement. A shipment dispatched from a partner country does not automatically acquire that country’s origin, and a certificate does not replace the underlying production, transport and verification conditions.
Nor should an importer apply a universal 5% starting duty without checking the goods. ZATCA’s integrated tariff identifies the applicable classification and rate; its official page records the GCC’s twelve-digit tariff implementation from 1 January 2025 and subsequent amendments.
Identify the tariff line and the correct preference route
Use the current Integrated Customs Tariff Inquiry, supported by the goods’ actual composition, function and classification. Record the rate and conditions applicable to the relevant import period. A past customs entry, generic product name or supplier’s quotation is insufficient to establish a current rate.
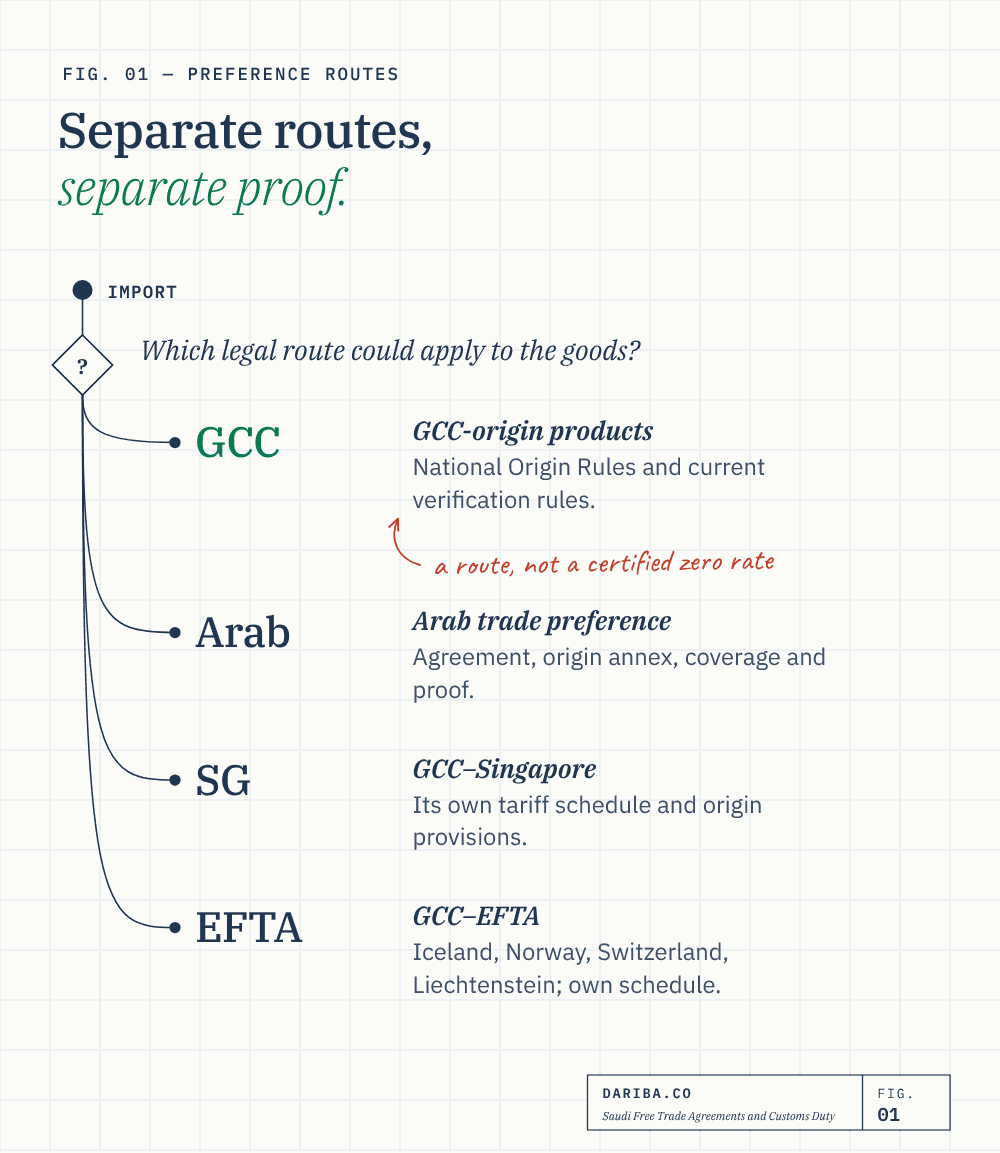
ZATCA publishes distinct instruments for GCC-origin goods, Arab trade preferences, the GCC–Singapore agreement and the GCC–EFTA agreement. These are separate legal routes with their own coverage, origin proof and schedules. EFTA’s listed partners are Iceland, Norway, Switzerland and Liechtenstein; do not infer a preference for an unexamined country merely from a regional description.
The table is a route-selection aid, not a certification that every product from those partners has a zero rate:
| Route | Required next enquiry |
|---|---|
| GCC-origin products | Saudi National Origin Rules and current verification rules |
| Arab trade preference | Applicable agreement, origin annex, product coverage and proof |
| GCC–Singapore | Its own tariff schedule and origin provisions |
| GCC–EFTA | Its own tariff schedule and origin provisions |
References: ZATCA Integrated Tariffs and inquiry service; official agreement pages identified in the sources.
Distinguish GCC origin from dispatch or prior customs payment
The National Origin Rules concern qualifying national products entering Saudi Arabia from GCC countries. They distinguish wholly obtained products from manufactured products using other materials. Industrial products require their actual value-added/localisation and other conditions.
Foreign goods do not become GCC-origin merely because they were warehoused, resold or customs-cleared there. Questions about prior duty payment, customs-union movement and settlement require their own customs analysis. They should not be presented as proof of manufacturing origin or an unconditional assurance of no further charge.
Free-zone products are specifically addressed in Article 15, including where local materials or previously duty-paid inputs are present. Article 31 also contains specified non-qualifying component/production and ownership connections. Passing a percentage calculation is not a substitute for those restrictions.
References: National Origin Rules Articles 1–5, 15 and 31.
Apply the value-added and workforce flexibility correctly
The ordinary manufactured-product framework uses a 40% value-added threshold and a 25% national-workforce localisation requirement for the industrial establishment. Article 3 provides specified compensating adjustments, with a 20% value-added floor and a 10% localisation floor. Those lower floors are not an independently qualifying pair.
The official Article 3 footnotes illustrate, among other cases, 15% localisation requiring 50% value added, and 50% localisation allowing the specified value-added minimum to reach 20%. The point is the required compensating excess, subject to the caps—not simply remaining above each minimum floor.
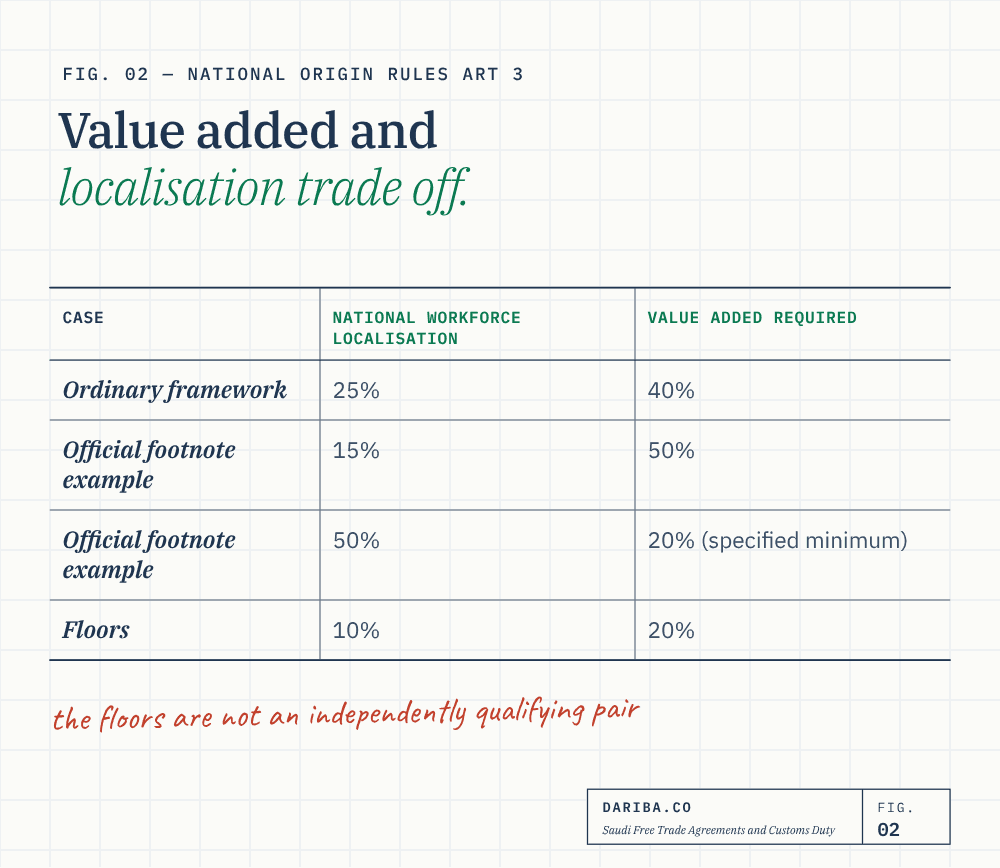
The GCC value-added and localisation guide explains the formula, all four official footnote examples, the evidence and the limitations. This origin “value added” is not VAT or an ordinary gross-profit-margin calculation.
References: National Origin Rules Articles 1, 3 and 5–6.
Verify sufficient processing and the direct transport conditions
Article 7 identifies operations insufficient to confer origin, including specified preservation, packaging, labelling and simple assembly operations. Their combination does not necessarily cure the problem. Article 8’s cumulation rules concern qualifying originating inputs and their evidence; importing materials from a GCC supplier does not itself establish cumulation.
Article 13 permits direct transport and the specified third-country transit where geographical reasons, customs control and permitted handling/storage conditions are met. Its documentary requirements support the actual route. The same article expressly addresses transport through free zones and invoices/documents issued from them. A mainland factory address alone cannot settle a transaction routed through a free-zone trader.
Exhibition goods have a separate Article 14 route, with conditions concerning original dispatch, display/sale, unchanged condition, use and customs control. Do not stretch the ordinary transit explanation to every exhibition or commercial resale.
References: National Origin Rules Articles 7–8 and 13–15.
Keep certificate validity and the claim period separate
Articles 16–19 concern the approved certificate, competent issuing authority and supporting records. Article 20 ordinarily makes the certificate valid for 180 days from issue, with its specific late-acceptance conditions: force majeure or compelling circumstances accepted by the importing authority, and the separate stated possibility for other late proof where the goods arrived before expiry. Article 21 requires the relevant exporter records to be retained for at least three years.
Articles 22–24 address retrospective issue, replacement copies and partial certificates in their stated circumstances; Article 27 addresses minor discrepancies and obvious formal errors where the required identity and reliability conditions remain satisfied. These are not permission to invent a certificate or disregard origin, but they make “every documentary defect permanently destroys preference at clearance” an overstatement.
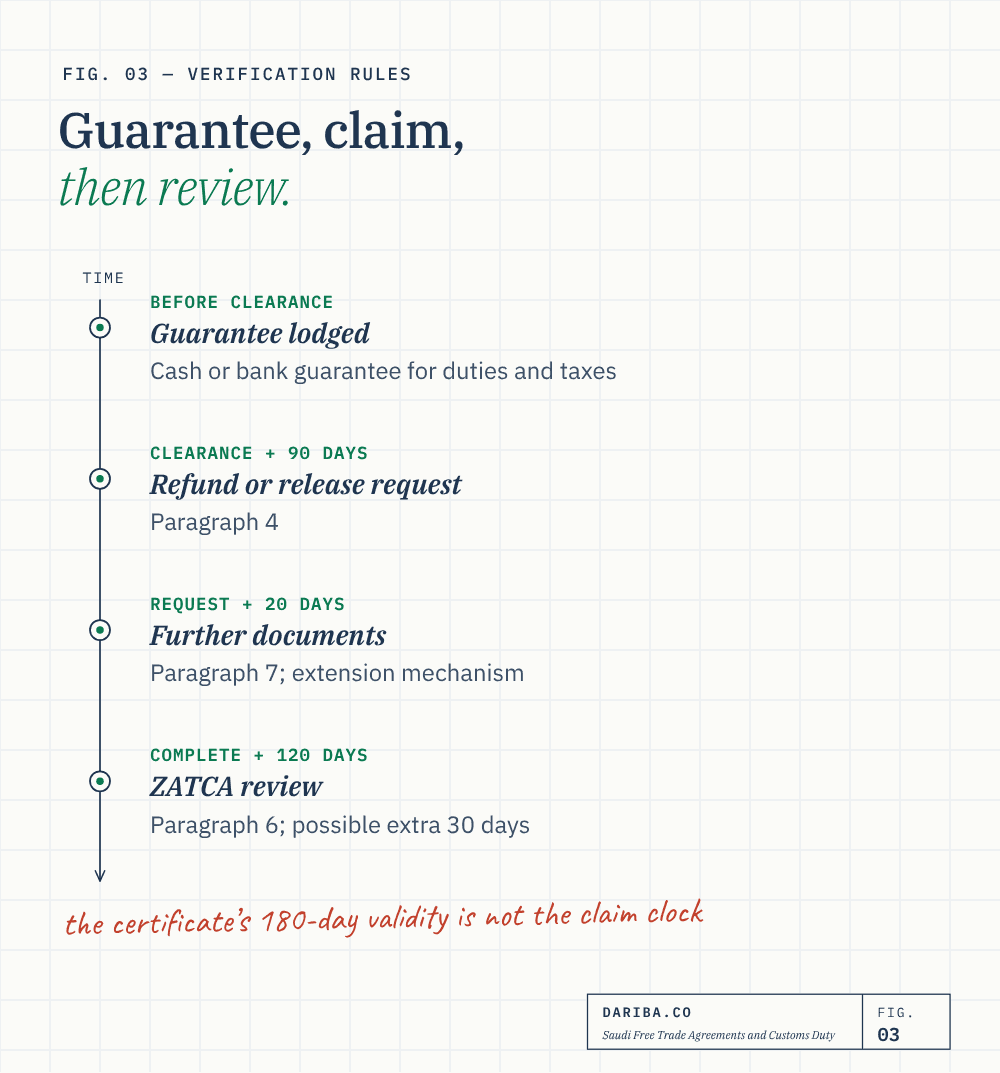
The separate verification procedure has a ninety-calendar-day period from customs release for the specified guarantee-refund/release request. Do not substitute the certificate’s 180-day validity for that claim clock, or assume that a retrospective certificate extends every procedural deadline.
References: National Origin Rules Articles 16–24 and 27; Verification Rules paragraph 4.
Follow the current guarantee and verification procedure
Under the ordinary Verification Rules route, the importer provides the prescribed cash or bank guarantee before clearance, covering the relevant customs duties and other taxes. The bank must meet paragraph 3’s Saudi-supervision condition. The guarantee is not the same as a final approval of origin.
Paragraph 4 allows the specified refund/release request within ninety calendar days of clearance, for one or multiple declarations. It excludes goods refused preferential treatment before clearance because the origin-marking or direct-shipping requirements were unmet. Paragraph 5 sets the minimum documents and supporting evidence, subject to an applicable paragraph 13 agreement discussed below.
Paragraph 6 gives the ordinary 120-calendar-day review period from submission of all required documents, with a possible additional thirty days. Paragraph 7 ordinarily requires requested further documents within twenty calendar days, with an extension mechanism and possible rejection for non-cooperation. Electronic requests, factory visits and authority-to-authority verification remain possible. Where reasonable doubt remains, paragraph 10 provides for refusal if the origin authority gives no response within three months or its response lacks sufficient information. That is an authority-verification rule, not an importer’s general filing extension.
References: Verification Rules paragraphs 1–12.
Test whether the September 2025 simplification actually applies
Paragraph 13, added by the decision published on 19 September 2025, permits reliance on the origin certificate, localisation certificate and supporting invoices in place of requirements under these Rules pursuant to an agreement between competent authorities. The competent authority in the origin country must retain the underlying supporting documents for the statutory periods.
Identify the actual agreement and which requirements it replaces in the arrangement being used. The amendment does not establish a universal three-document shortcut for every GCC shipment, automatically eliminate every guarantee, or waive the substantive National Origin Rules. Equally, an old checklist should not insist on a requirement displaced by a verified applicable agreement.
Dariba recommendation: record the agreement relied on alongside the import declaration and evidence of its applicable scope. This makes the simplified route reviewable without treating its existence as a conclusion on the goods’ origin.
References: current Verification Rules paragraph 13; Governor’s Decision 1447-99-303, published 19 September 2025.
Separate duty preference from other taxes and remedies
Customs preference does not itself determine import VAT, excise liability or the applicable trade-remedy rules. National Origin Rules Article 33 expressly addresses the relationship with anti-dumping, countervailing and safeguard measures in the specified production/input circumstances. A zero ordinary tariff conclusion should not be extrapolated into an exemption from every import charge.
The import-VAT guide and current excise overview address their separate frameworks. Preserve the actual customs value, tariff line, origin calculation, direct-shipping chain, certificate, guarantee/claim dates, competent-authority agreement where used and assessment outcome.
The result should be a conditional conclusion for the actual goods and route. This article does not certify a product’s HS classification, current preferential rate, every agreement’s full schedule or an importer’s refund entitlement.
Key takeaways
- Use the actual current tariff line and date rather than a universal five-percent assumption.
- GCC dispatch, prior duty payment and manufacturing origin are separate questions.
- The 20% value-added and 10% localisation floors do not form an independently qualifying pair.
- Direct shipping, sufficient processing and free-zone restrictions require their own evidence.
- Certificate validity, guarantee requests and further-document responses have different clocks.
- The September 2025 simplified route requires an actual competent-authority agreement.
- Customs preference does not itself determine VAT, excise or trade-remedy treatment.
Sources
- Saudi National Origin Rules, Ministerial Decision 3852 dated 22 Dhu al-Qidah 1442 AHArticles 1–8 and 13–33; Article 3 official footnote examples; ex-factory/input definitions, insufficient processing, cumulation, transport, certificates, record retention and other origin conditions.
- ZATCA Rules and Conditions for Verification of Proof of Origin, current amended textAdministrative Decision 24841 and the September 2025 amendment. Paragraphs 1–13: guarantees, ninety-day requests, evidence, 120/30-day review, twenty-day response and competent-authority-agreement simplification.
- ZATCA current National Origin Rules and verification instrumentsOfficial publication links to the National Rules and current amended proof-verification rules.
- ZATCA Integrated TariffsTwelve-digit GCC implementation from 1 January 2025 and current amendment links; this is not a universal five-percent rate.
- ZATCA Integrated Customs Tariff InquirySearch the actual tariff line by code/description/chapter/section for the relevant period.
- ZATCA Arab trade agreement and origin annexSeparate agreement/origin route; product and country eligibility require the actual instrument and period.
- ZATCA GCC–Singapore free trade agreementDistinct schedule and origin provisions; no universal zero rate certified here.
- ZATCA GCC–EFTA free trade agreementListed EFTA partners Iceland, Norway, Switzerland and Liechtenstein; actual schedules/origin conditions remain necessary.
- Umm Al-Qura: addition of paragraph 13 to proof-verification rules, 19 September 2025Governor’s Decision 1447-99-303; simplified evidence depends on an agreement between competent authorities and preservation of supporting records.
General information only. Apply actual tariff classification, origin, production, period, transport and procedural conditions under the controlling Arabic instruments and any verified competent-authority agreement. Official Article 3 examples and Dariba original illustrations are distinguished. This review does not certify an HS code, shipment, factory, full agreement schedule or refund entitlement.