In brief
Use actual legislation, dated qualified-status evidence and the group calculation to assess Saudi exposure and possible foreign collection.
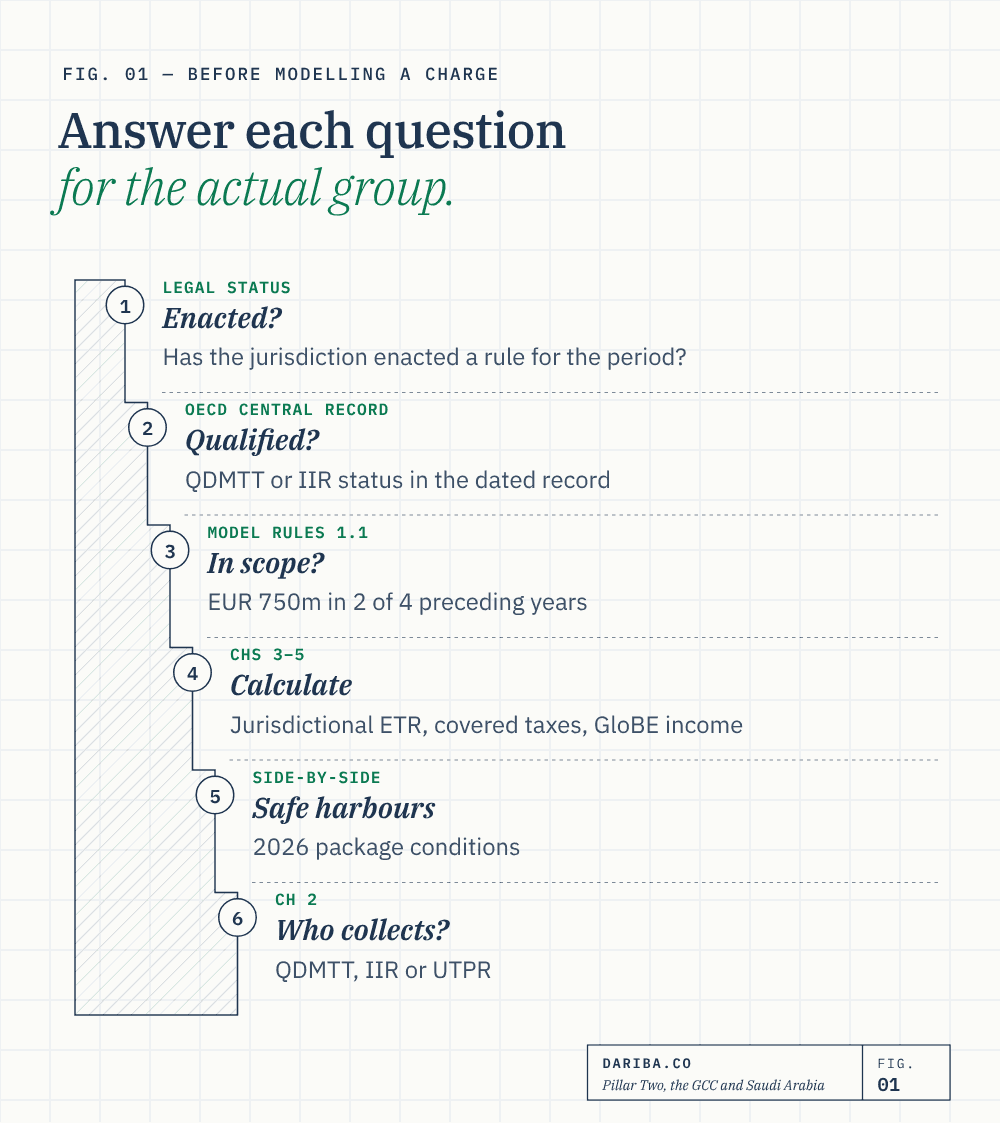
Pillar Two decisions require three separate questions: has a jurisdiction enacted a rule, does that rule have the relevant qualified status, and does an actual group meet its conditions for the period? OECD membership, a domestic incentive or absence from a qualified-status table cannot answer all three.
For Saudi operations, the commercial issue is whether the group’s actual structure and implementing laws produce a domestic or foreign top-up charge. The absence of an identified Saudi domestic minimum top-up tax is not a reliable basis for promising either a foreign charge or complete protection from one.
Distinguish Saudi implementation evidence from OECD membership
The OECD central-record page expressly explains that jurisdictions are not required to introduce the GloBE rules. It also warns that legislation’s absence from the qualified-status record does not establish that it is unqualified: the transitional process might not have been initiated or completed.
The official central record retrieved for this review is stated to be current as at 1 May 2026. It does not list Saudi Arabia in the relevant IIR or QDMTT tables. This is a dated observation about that record, not conclusive proof that no later Saudi law, draft or announcement exists. This review did not identify an operative Saudi DMTT instrument establishing a Saudi charge or filing deadline; an actual Saudi obligation should be supported by the legislation and its commencement before being asserted.
For a transaction or restructuring, obtain that local legal-status confirmation for the actual date. Neither participation in the international framework nor a general expectation of policy alignment is an enacted charging provision.
Reference: OECD central-record page, About; Updated Central Record, introductory qualifications and tables.
Read the GCC comparison as a dated qualified-status record
The same record identifies the following domestic minimum-tax legislation with a 1 January 2025 effective date and QDMTT Safe Harbour status shown as “Yes”, subject to its notes:
| Jurisdiction | Legislation identified by the OECD record |
|---|---|
| Bahrain | Decree-Law No. 11 of 2024 |
| Kuwait | Decree-Law No. 157 of 2024 |
| Oman | Royal Decree 70/2024 |
| Qatar | Law No. 22 of 2024 amending the Income Tax Law |
| United Arab Emirates | Cabinet Decision No. 142 of 2024 |
Qatar’s entry includes the record’s qualification that self-certification was based on draft secondary legislation. The table should not be presented as a fresh audit of every jurisdiction’s complete implementing regulations, filing portal or later administrative changes.
A QDMTT and an Income Inclusion Rule are also different. The separate IIR table and the relevant domestic law must be consulted before claiming that a particular GCC state collects foreign subsidiaries’ top-up tax. The effective date generally concerns the start of the relevant fiscal year, rather than automatically taxing every payment made after 1 January.
Reference: OECD Updated Central Record, Qualified Income Inclusion Rules and Qualified Domestic Minimum Top-up Tax Rules and QDMTT Safe Harbours, including footnotes.
Identify who could collect tax before modelling a shortfall
The GloBE architecture coordinates domestic minimum top-up taxation, the IIR and the UTPR. An IIR can charge a qualifying parent on relevant low-taxed constituent-entity income; the UTPR provides a further mechanism subject to its own allocation and application conditions. A qualified domestic charge can affect the remaining foreign top-up calculation and safe-harbour treatment.
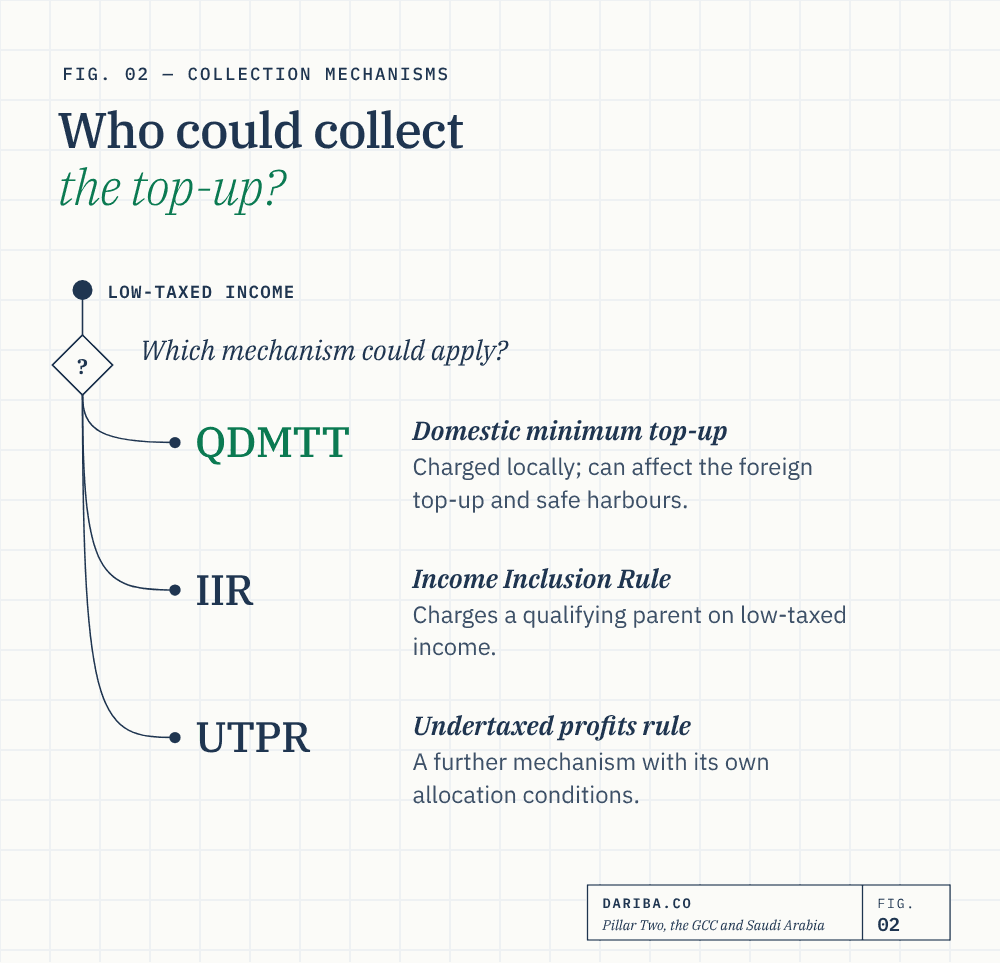
These are conditional legal mechanisms. They do not justify saying that every absence of domestic DMTT automatically transfers a fixed amount of tax to the ultimate parent’s country. Identify the implementing laws, ownership chain, qualification, elections, effective periods and relief available to this group.
The 2026 Side-by-Side Package adds further reasons to avoid that automatic conclusion. Its safe harbours depend on the specified regime and group conditions. The existence of an international agreement on a package does not itself prove a Saudi subsidiary’s entitlement under every foreign implementing law.
References: OECD GloBE Model Rules, Chapter 2 and Article 5.2; Side-by-Side Package, relevant safe-harbour provisions.
Confirm scope and the actual jurisdictional calculation
The Model Rules generally apply the EUR 750 million consolidated-revenue threshold in at least two of the four preceding fiscal years, with short-year and restructuring rules. Constituent-entity and excluded-entity definitions remain relevant. A broad statement that all cross-border businesses are affected—or that nothing can apply below that number under any domestic law—goes beyond that test.
The ordinary GloBE calculation uses adjusted covered taxes and net GloBE income on a jurisdictional basis, with special rules where required. The substance-based income exclusion affects excess profit; it is not a blanket exemption from group scope or all reporting. The de minimis and safe-harbour provisions also need their actual conditions.
Dariba recommendation: reconcile the Saudi jurisdictional calculation before comparing different GCC locations. A location comparison based only on quoted statutory percentages can conceal different tax bases, incentives, accounting adjustments, substance and implementing rules.
References: Model Rules Articles 1.1–1.5, Chapters 3–5 and Article 6.1; current applicable administrative guidance.
A simple illustration shows why the headline tax rate is insufficient
Dariba original illustration — assumed inputs only: net GloBE income is SAR 100 million and adjusted covered taxes are SAR 10 million, giving a 10% ETR. Assume a valid SAR 8 million substance-based income exclusion, no applicable safe harbour, no additional current top-up tax and no deductible qualified domestic top-up tax. The illustrative excess profit is SAR 92 million; the five-percentage-point gap to 15% produces SAR 4.6 million before allocating any charge under the applicable implementing rules.
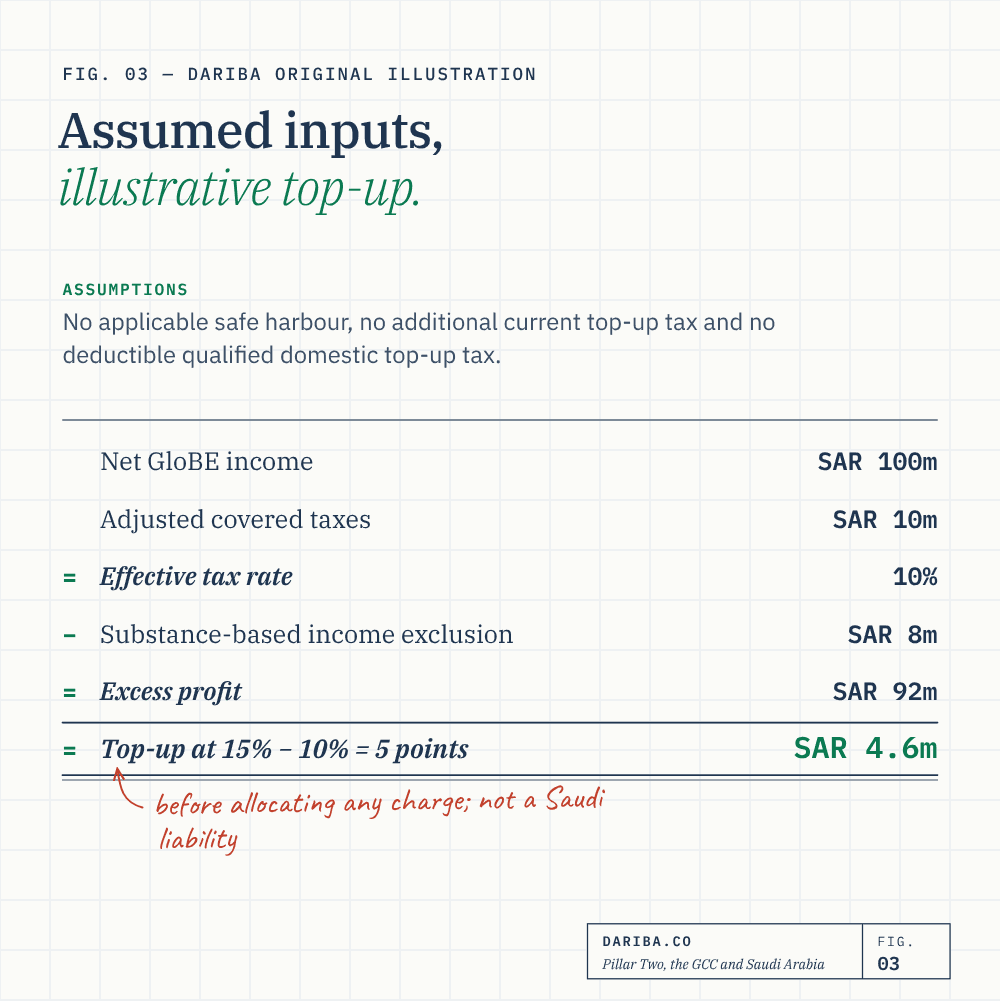
The example does not establish that a particular Saudi entity owes SAR 4.6 million, that every Zakat payment is a covered tax, or that an incentive causes a top-up charge equal to fifteen percentage points of accounting profit. Each assumption requires support, and other applicable rules can change the answer.
Saudi Zakat, CIT and incentive regimes should therefore be translated into the actual GloBE accounting and tax inputs. Zakat’s statutory base differs from an income-tax base. RHQ and zone benefits apply only within their own legal conditions and do not establish eligibility for an OECD safe harbour.
References: Model Rules Articles 5.1–5.3; Saudi RHQ incentive guide and special economic-zone guide.
Check the 2026 safe-harbour changes before promising an incentive outcome
The January 2026 package includes a Simplified ETR Safe Harbour, a one-year extension of the Transitional CbCR Safe Harbour, a Substance-based Tax Incentives Safe Harbour and Side-by-Side measures. Each has its own qualification and commencement conditions.
In particular, an expenditure-based or production-based incentive analysis is not settled by describing a Saudi corporate income-tax rate as preferential. Identify the actual incentive design and eligible expenditure or production, then test the package and its implementation. Do not promise that every Saudi tax holiday is protected or that every such holiday is neutralised.
The extended Transitional CbCR Safe Harbour window and the revised GIR reporting framework are different forms of relief. The Saudi group reporting guide explains their separate periods, the 15/18-month filing distinction and the reporting-year choice of GIR version.
Reference: OECD Side-by-Side Package, sections addressing the respective simplifications and safe harbours.
Preserve a dated decision file for the board and finance team
A useful conclusion identifies the group and reporting year, Saudi legal-status evidence, relevant foreign charging law, current qualified status, ETR and substance calculation, safe-harbour decision, and resulting filing/payment responsibilities. Distinguish confirmed facts from assumptions requiring further evidence.
Where the current source does not establish a Saudi enactment, state that limitation directly. Where a foreign charge depends on an IIR, UTPR or safe harbour, retain the applicable law and period-specific analysis. Where data is incomplete, show the sensitive assumptions rather than substitute an unsupported “no exposure” conclusion.
This approach gives management an actionable analysis: which facts affect the outcome, which authority could assess a charge and which obligations need attention. It does not turn a dated international status table into a Saudi legislative ruling.
Key takeaways
- OECD membership does not enact a Saudi minimum-tax charge or filing obligation.
- The retrieved qualified-status record is stated current as at 1 May 2026.
- Saudi non-listing in that record alone does not prove the absence of later legislation.
- The GCC table records qualified domestic rules and preserves the source footnotes.
- A foreign IIR or UTPR charge depends on actual implementation and group conditions.
- Jurisdictional ETR, substance and eligible relief affect the top-up calculation.
- A Saudi incentive licence does not by itself establish an OECD safe harbour.
Sources
- OECD GloBE Model Rules, December 2021Articles 1.1–1.5, Chapters 2–5, Articles 8.1 and 9.4.1. Fifteen-month ordinary and eighteen-month transitional information-return periods require actual domestic implementation.
- OECD GloBE Information Return, January 2025, revised January 2026Earlier-period return and explanatory guidance. Do not choose a reporting template solely from the calendar year in which filing occurs.
- OECD GloBE Information Return, September 2026Introduction paragraphs 3, 8–13 and 36.1: information return distinct from tax return/payment; separate simplified-reporting period; revised return for years commencing on or after 31 December 2025.
- OECD GloBE Side-by-Side Package, January 2026Simplified ETR, Transitional CbCR extension, Substance-based Tax Incentives and Side-by-Side safe harbours have their own conditions. Section 3 extends the CbCR window and preserves 17% for 2026/2027 starts.
- OECD Updated Central Record for Purposes of the Global Minimum Tax, May 2026Record stated current as at 1 May 2026. Qualified IIR and QDMTT tables and footnotes; non-listing does not itself prove non-enactment or lack of qualification.
- OECD Support for Central GloBE Information Return Filing and Exchange, 2024 Reporting Fiscal Year, May 2026Paragraphs 1–4, footnotes and Annex: specific central-filing/exchange support and participation conditions; not a universal filing extension.
- OECD central-record page, current official publication linksAbout expressly distinguishes qualified status and implementation; linked operative record retrieved for this review is dated 1 May 2026.
General information only. OECD model rules and guidance require actual implementation and period-specific application. This review distinguishes identified official status from proof of Saudi enactment and does not establish a Saudi GIR filing obligation. Dates and arithmetic labelled Dariba illustrations assume the stated period and conditions; no independent legal certification or individual tax conclusion.