In brief
Identify the implementing jurisdiction and reporting year before assigning a GIR deadline, local filing obligation or data request to a Saudi entity.
A Saudi entity can need to supply Pillar Two data to its multinational group even where a Saudi filing obligation has not been established. The legal obligation to file, the entity that files, the reporting period and the tax payment deadline must nevertheless be identified under the relevant implementing jurisdiction’s rules. The OECD framework does not itself impose a universal Saudi return.
The first practical question is which year is being reported. Eighteen months after 31 December 2025 is 30 June 2027. The widely discussed 30 June 2026 first-filing date relates to the relevant 2024 reporting year, not a full year ending in December 2025.
Establish group scope before requesting every Saudi ledger
Model Rules Article 1.1 generally tests consolidated ultimate-parent revenue of at least EUR 750 million in at least two of the four preceding fiscal years. Short fiscal years and restructurings require their additional rules. Articles 1.2–1.5 address the multinational group, constituent entities, permanent establishments and excluded entities.
A small Saudi subsidiary is not automatically outside an otherwise in-scope group. Conversely, a government, pension or investment connection does not automatically make every related operating company an excluded entity. Test the actual definitions and ownership/activity conditions. Do not confuse a Saudi entity’s standalone turnover with the consolidated group test, or assume that every domestic minimum-tax law must have exactly the same scope as the Model Rules.
Reference: OECD GloBE Model Rules, Articles 1.1–1.5 and 6.1.
Separate local filing from supplying group information
Model Rules Article 8.1 starts from filing in an implementing jurisdiction, with a designated local entity permitted to file on behalf of constituent entities. Central filing by the ultimate parent or designated filing entity can remove local GIR filing where the required qualifying exchange arrangement is in effect for the relevant year. The associated notification obligation must still be addressed.
The group therefore needs an obligation map: reporting year, implementing jurisdiction, filing entity, exchange entitlement and any local notification. A Saudi accounting team providing data for that exercise has not thereby become a Saudi GIR filer. Equally, filing a group return somewhere abroad does not, without the exchange and notification conditions, establish compliance in every other jurisdiction.
References: Model Rules Article 8.1(1)–(3); OECD GloBE Information Return, Introduction, central-filing discussion.
Calculate the deadline from the actual reporting year
Article 8.1.6 provides the ordinary fifteen-month GIR/notification period. Article 9.4.1 provides eighteen months for the reporting fiscal year that is the defined transitional year. Confirm the actual implementing legislation, transition status and any applicable relief before setting a deadline.
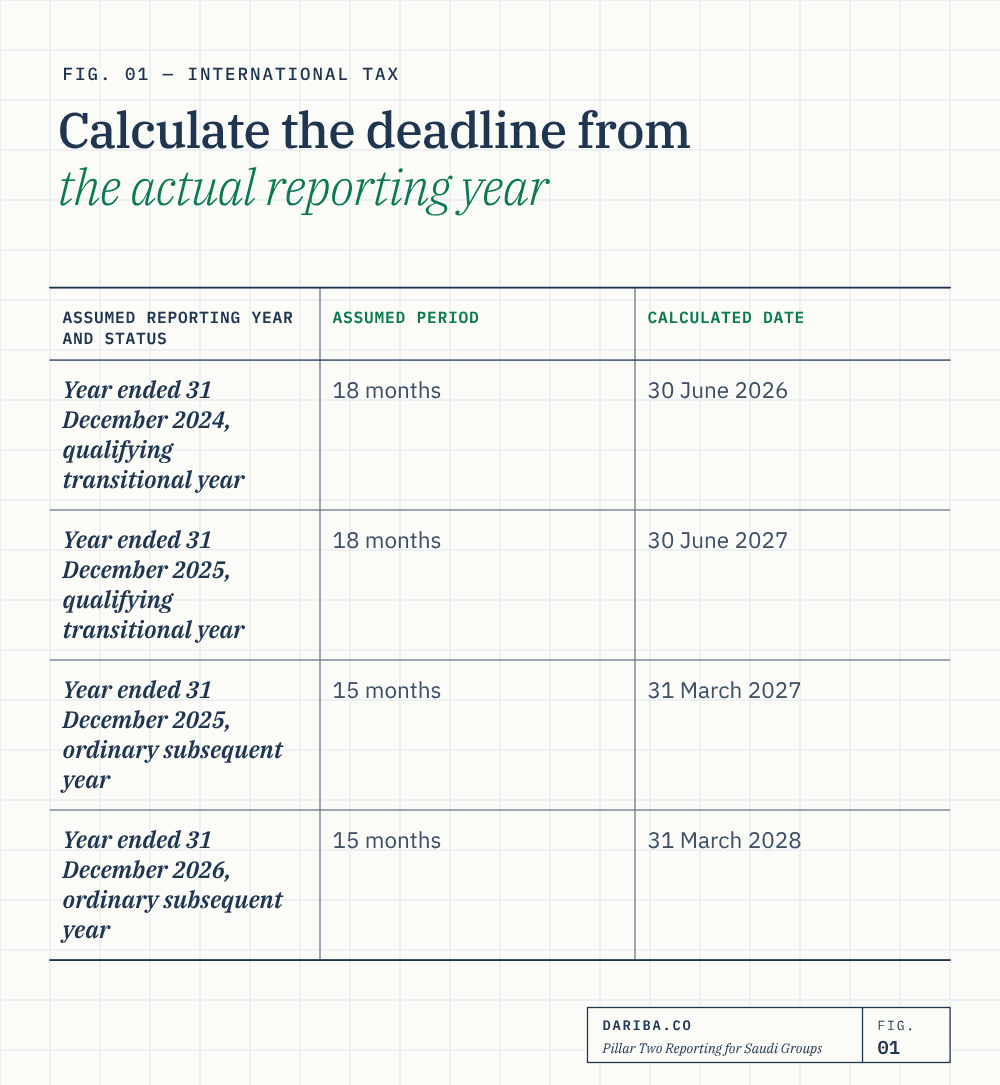
Dariba original date illustrations:
| Assumed reporting year and status | Assumed period | Calculated date |
|---|---|---|
| Year ended 31 December 2024, qualifying transitional year | 18 months | 30 June 2026 |
| Year ended 31 December 2025, qualifying transitional year | 18 months | 30 June 2027 |
| Year ended 31 December 2025, ordinary subsequent year | 15 months | 31 March 2027 |
| Year ended 31 December 2026, ordinary subsequent year | 15 months | 31 March 2028 |
These calculations do not establish that every group receives a new eighteen-month period whenever another country introduces rules. Nor does a GIR deadline establish the separate domestic top-up tax return or payment date. The OECD’s September 2026 GIR Introduction expressly separates the information return from declaring and paying tax.
References: Model Rules Articles 8.1.6 and 9.4.1; September 2026 GIR, Introduction, paragraph 3.
Read the 2024 filing support with its conditions
The OECD’s Support for Central GloBE Information Return Filing and Exchange (2024 Reporting Fiscal Year) explains the 30 June 2026 filing timetable and related exchange coordination. Its common understanding addresses delayed filing portals or exchange activation through mechanisms available under participating jurisdictions’ domestic laws.
Paragraphs 3–4 concern penalty waiver or non-enforcement of local filing before the relevant exchange deadline where timely central filing in a listed jurisdiction and the required local notification have occurred. The footnotes preserve jurisdiction-specific participation limits, and later local enforcement remains possible if the GIR is not exchanged as required.
This is useful relief to investigate for an affected 2024 filing. It is not a universal extension, an amnesty for an unfiled central GIR, or permission to ignore a 2025-year deadline. Retain filing acceptance and notification evidence rather than relying only on a tax adviser’s calendar entry.
Reference: OECD 2024 reporting-year common understanding, paragraphs 1–4, footnotes and Annex.
Select the GIR version by the reporting period
The September 2026 GIR, Introduction paragraph 36.1, says that its revised return is for fiscal years commencing on or after 31 December 2025. The January 2025 GIR remains relevant to earlier periods. The revised document also contains clarifying notes concerning existing data points; the period restriction should not be mistaken for permission to disregard those clarifications.
For a calendar year beginning 1 January 2025, the fact that filing occurs during 2027 does not by itself move the reporting year into the September 2026 return. A calendar year beginning 1 January 2026 meets the stated commencement boundary. Keep the reporting-template question separate from the technical schema and submission rules accepted by the filing administration, including the current transition instructions.
Dariba recommendation: record the fiscal-year start as well as its end in the reporting workbook. A filing-year-only label can select the wrong return version even when the deadline arithmetic is correct.
Reference: OECD GloBE Information Return, September 2026, Introduction paragraph 36.1; January 2025 GIR.
Do not confuse safe-harbour relief with reporting simplification
The January 2026 Side-by-Side Package extends the Transitional CbCR Safe Harbour to fiscal years beginning on or before 31 December 2027, excluding years ending after 30 June 2029. The simplified-ETR transition rate remains 17% for years beginning in 2026 and 2027. The other eligibility, data-quality and continuity conditions still require review; “CbCR filed” is not the test by itself.
The package’s Simplified ETR Safe Harbour has its own commencement and conditions. Its Side-by-Side and tax-incentive measures also require their particular qualification; a Saudi incentive licence alone proves none of them.
The September 2026 GIR’s simplified jurisdictional reporting framework is different again. It uses a separate window—years beginning on or before 31 December 2028, excluding years ending after 30 June 2030—and its own election and eligibility rules. Simplifying which entity-level adjustments are reported is not the same as deeming top-up tax to be zero. Record the relief claimed, legal basis, election and supporting calculations separately.
References: Side-by-Side Package, sections 2–3 and related safe-harbour provisions; September 2026 GIR, Introduction paragraphs 8–13.
Build a Saudi data file without treating headline rates as the answer
Identify the Saudi entities and PEs, group reporting accounts, local adjustments, current/deferred tax information, elections, ownership changes and relevant substance data. Reconcile amounts supplied to the group with the underlying books and local tax/Zakat positions.
Zakat is generally calculated on a statutory Zakat base; its headline percentage is not automatically a percentage of GloBE profit. Similarly, a domestic CIT rate or an RHQ/zone incentive does not itself determine adjusted covered taxes, jurisdictional blending or the available exclusions. Explain material differences rather than inserting the domestic headline rate into a group ETR cell.
The GCC and Saudi status guide addresses why enactment, qualification and collection need separate evidence. Dariba’s recommended deliverable is a dated obligation matrix and reconciled data pack, with unresolved classification or exchange questions assigned to a responsible reviewer. That control is advisory analysis, not an OECD-prescribed workbook or certification that the group’s tax liability is nil.
Key takeaways
- Eighteen months after 31 December 2025 is 30 June 2027, not 30 June 2026.
- The ordinary fifteen-month period and transitional eighteen-month period have different conditions.
- Supplying Saudi group data does not itself create a Saudi GIR filing obligation.
- Central filing requires the relevant exchange and notification conditions.
- The September 2026 revised GIR uses a reporting-year commencement boundary.
- CbCR tax relief and simplified GIR reporting have separate windows and eligibility rules.
- A local headline Zakat, CIT or incentive percentage is not the GloBE ETR.
Sources
- OECD GloBE Model Rules, December 2021Articles 1.1–1.5, Chapters 2–5, Articles 8.1 and 9.4.1. Fifteen-month ordinary and eighteen-month transitional information-return periods require actual domestic implementation.
- OECD GloBE Information Return, January 2025, revised January 2026Earlier-period return and explanatory guidance. Do not choose a reporting template solely from the calendar year in which filing occurs.
- OECD GloBE Information Return, September 2026Introduction paragraphs 3, 8–13 and 36.1: information return distinct from tax return/payment; separate simplified-reporting period; revised return for years commencing on or after 31 December 2025.
- OECD GloBE Side-by-Side Package, January 2026Simplified ETR, Transitional CbCR extension, Substance-based Tax Incentives and Side-by-Side safe harbours have their own conditions. Section 3 extends the CbCR window and preserves 17% for 2026/2027 starts.
- OECD Updated Central Record for Purposes of the Global Minimum Tax, May 2026Record stated current as at 1 May 2026. Qualified IIR and QDMTT tables and footnotes; non-listing does not itself prove non-enactment or lack of qualification.
- OECD Support for Central GloBE Information Return Filing and Exchange, 2024 Reporting Fiscal Year, May 2026Paragraphs 1–4, footnotes and Annex: specific central-filing/exchange support and participation conditions; not a universal filing extension.
- OECD central-record page, current official publication linksAbout expressly distinguishes qualified status and implementation; linked operative record retrieved for this review is dated 1 May 2026.
General information only. OECD model rules and guidance require actual implementation and period-specific application. This review distinguishes identified official status from proof of Saudi enactment and does not establish a Saudi GIR filing obligation. Dates and arithmetic labelled Dariba illustrations assume the stated period and conditions; no independent legal certification or individual tax conclusion.