In brief
Distinguish KAEC, Ras Al-Khair, Jazan, Cloud Computing and SILZ; apply qualifying-income, VAT, customs suspension and economic substance conditions.
Saudi special-zone incentives depend on the actual zone, licence, activity and transaction. KAEC, Ras Al-Khair and Jazan, the Cloud Computing SEZ and the Special Integrated Logistics Zone do not share one universal tax package. ZATCA’s current Tax and Customs Operations in Special Economic Zones procedural guide separates the first three zones from Cloud Computing; the logistics zone has its own framework and guideline.
Identify the zone before applying a rate
Chapter One of the SEZ procedural guide addresses KAEC, Ras Al-Khair and Jazan. Chapter Two separately addresses Cloud Computing. The Economic Substance Requirements Regulation of Special Economic Zones, Article 1, defines its four-zone scope; SILZ is not included in that definition.
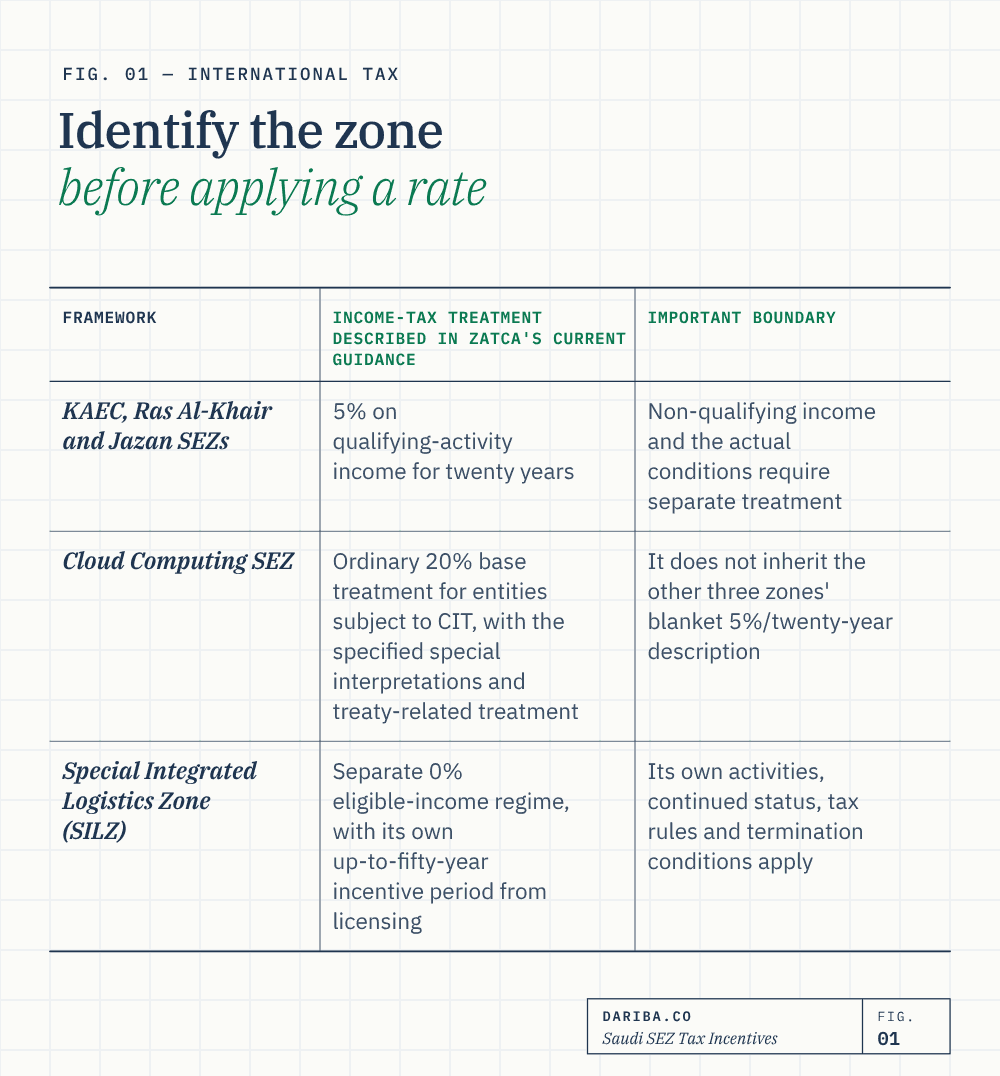
| Framework | Income-tax treatment described in ZATCA’s current guidance | Important boundary |
|---|---|---|
| KAEC, Ras Al-Khair and Jazan SEZs | 5% on qualifying-activity income for twenty years | Non-qualifying income and the actual conditions require separate treatment |
| Cloud Computing SEZ | Ordinary 20% base treatment for entities subject to CIT, with the specified special interpretations and treaty-related treatment | It does not inherit the other three zones’ blanket 5%/twenty-year description |
| Special Integrated Logistics Zone (SILZ) | Separate 0% eligible-income regime, with its own up-to-fifty-year incentive period from licensing | Its own activities, continued status, tax rules and termination conditions apply |
The SILZ treatment is described in its separate guideline, sections 4–4.1: the income-tax and withholding incentive period ends on the earlier of fifty years or the entity ceasing to exist in the zone, including licence cancellation or suspension. This comparison identifies the different frameworks; it does not certify a particular entity’s entitlement.
Review SILZ payments and relocated activities under its own rules
The Special Tax Rules for the Special Integrated Logistics Zone, Article 3, distinguishes the specified withholding categories and their conditions. In particular, royalties and technical or other service payments require the defined related recipient and ultimate-beneficiary analysis; paragraph (D) preserves non-prescribed activity, related mainland-payment and avoidance exclusions. An entity should not promise relief for every unrelated foreign supplier merely because its cost supports SILZ operations.
Article 5 separately restricts the stated relocations of existing mainland activity and payments facilitated for persons ineligible for relief. ZATCA’s SILZ guideline section 5 discusses transfer disclosure and fair market value, but these should not be represented as automatic clearance of every relocation under the published special rule.
The SILZ income and withholding guide explains the distinctions, separate activity accounts, relief period and a clearly labelled original mixed-base illustration. A new zone entity, licence or transfer-pricing disclosure alone does not establish every tax incentive condition.
Match the activity to the licence in the three geographically defined zones
The SEZ procedural guide, Chapter One, section 1, identifies different qualifying activities. Its examples include manufacturing and logistics in KAEC; shipbuilding, rig building and maritime services in Ras Al-Khair; and food processing, metal conversion and logistics in Jazan, alongside activities determined by relevant decisions.
Dariba recommendation: obtain the actual licence and activity classification, establish where the work is performed and distinguish qualifying from other income. A business address in a zone is not evidence that every contract signed by that entity earns the qualifying rate.
Apply the qualifying-income rate and keep non-qualifying income separate
Chapter One, section 2.1, describes 5% income tax on qualifying income for twenty years for the three zones, including the stated Saudi and equivalent GCC-owned licensed entities. Non-qualifying income follows the ordinary treatment described there and is calculated separately.
Official examples: section 2.1, Example 1, compares a UK parent’s mainland subsidiary taxed at 20% with its SEZ subsidiary undertaking exclusively qualifying activities taxed at 5%. Example 2 separately shows that a wholly Saudi-owned SEZ company is subject to the SEZ income-tax provisions while a mainland company owned by the same partners follows the applicable Zakat provisions.
Dariba analysis: ownership and zone status must be analysed together. Do not assume that a Saudi-owned licensed entity necessarily follows the same Zakat route as an otherwise similar mainland company. Equally, the example’s exclusively qualifying business does not establish a 5% result for every mixed-activity entity.
Mixed income needs a supported computation
Chapter One, section 2.5.3.1, requires separate calculation of non-qualifying income and its expenses where possible. Where qualifying and non-qualifying profits cannot be segregated, it states a formula for the base subject to the ordinary 20% rate: the licensed entity’s tax base multiplied by non-qualifying income divided by total income.
Dariba illustration — the stated formula only: assume that route applies, the supported total tax base is SAR 2 million, total income is SAR 10 million and non-qualifying income is SAR 1 million. The base allocated to 20% is SAR 200,000, giving SAR 40,000 tax on that component before any applicable credits or further adjustments. This illustration does not approve an unsupported income classification or establish the tax on the remaining component without checking its eligibility.
Dariba recommendation: maintain separate activity accounts where possible and document why any fallback allocation is used. Do not allocate costs simply to move profit into the lower-rate category. Related-party pricing and the actual tax-base adjustments still matter.
Withholding relief does not remove reporting or anti-avoidance conditions
Chapter One, section 2.2, describes the licensed-entity exemption from withholding and remitting tax on the amounts addressed under Income Tax Law Article 68 and Regulations Article 63, while expressly retaining action against evasion or avoidance. The section also requires a detailed annual declaration of non-resident payments.
Official example: section 2.2, Example 3, compares dividends paid to a UK parent. It applies no withholding to the SEZ subsidiary’s distribution on the stated qualifying-activity facts and 5% to the mainland subsidiary’s distribution. Preserve those facts rather than infer that any payment routed through any zone entity must be exempt.
Section 2.5.3.2 gives the annual WHT-statement period as no later than 120 days after the licensed entity’s financial year ends. Check actual payment scope, the applicable instrument and the reporting requirement even where the tax withheld is nil. Cloud Computing and SILZ require their own withholding analyses.
Customs suspension is different from a permanent zero duty
Chapter One, section 2.4, describes customs-duty and VAT suspension for the qualifying goods and procedures. Goods brought from outside the Kingdom and later re-exported can avoid collection under the stated conditions, but removal into the local market ends suspension and can trigger import VAT, customs duties and clearance requirements.
Dariba analysis: a customs-suspension benefit can improve cash flow and support re-export operations without making every later mainland sale duty-free. Trace the goods, customs declaration, suspension status, movement and final destination. The earlier shorthand “0% customs on all equipment and inputs” is too broad for this framework.
VAT depends on the goods movement and its conditions
Chapter One, sections 2.3.2.1–2.3.2.3, distinguish qualifying supplies within or between zones, mainland-to-zone supplies, zone-to-mainland movements and goods arriving from outside the Kingdom. The described zero-rate and outside-scope treatments require the stated customs-suspension and qualifying-activity conditions.
For example, section 2.3.2.1, Examples 4–5, shows zero-rated goods supplies within a zone and between the specified zones where the conditions are met. Section 2.3.2.3, Example 8, instead illustrates a qualifying overseas goods movement into the zone treated outside the scope while liability is suspended. Zero rating and outside scope are different classifications and should not share one undifferentiated return code.
Section 2.3.2.4 keeps services under the ordinary service rules. A service to an SEZ customer is not automatically zero-rated because goods under suspension receive special treatment. Establish the supply, applicable rate and any reverse-charge obligation separately. Maintain the location and movement evidence described in section 2.5.3.3.
Meet the annual economic substance requirements
The Economic Substance Requirements Regulation, Articles 3–4, applies to licensed entities undertaking qualifying activities in its defined zones. Article 4(a) requires annual compliance from the first financial year in which qualifying activities are carried on: appropriate premises and assets; adequate full-time employees physically present in the zone, including the specified contracted-company personnel; proportionate operating expenditure in the zone; and direction and management from within it.
The management requirements include at least one relevant director resident in the Kingdom, appropriately qualified management and actual strategic decisions recorded in meeting minutes, with the prescribed board or equivalent quorum in the Kingdom. Do not replace those requirements with a universal assumption that a licence, a registered address or occasional remote approval is sufficient.
Dariba recommendation: maintain a yearly evidence pack linking functions, personnel, premises, costs and decisions to the licensed activity. Substance is an ongoing factual test; the appropriate resources for one activity are not automatically appropriate for another.
Intellectual property has additional conditions and an income exclusion
Article 4(b) adds requirements for IP activities: at least 50% of the relevant directors resident in the Kingdom; a detailed commercial business plan for holding the IP assets in the zone; employee experience, contracts, qualifications and tenure information; strategic decisions and risk management and assumption within the zone; and an activity not confined to marketing IP assets.
Article 5 separately ties qualifying IP activities to the competent authority’s classification and excludes incentives and exemptions for income from the stated IP-marketing activities. The exclusion should not be reduced to the proposition that every other form of IP income automatically qualifies.
Dariba analysis: distinguish legal ownership from the actual people making decisions and controlling risks, and identify the particular income category. Adding a resident director alone does not satisfy the entire IP test. Nor should the 50% director condition for IP be presented as the universal minimum for every non-IP licensed entity.
File the annual substance disclosure and preserve ordinary compliance
Article 6 requires an annual substance declaration using ZATCA’s prescribed form and procedures. Article 7 applies the penalties issued by the competent authority for substance violations; it does not itself supply one universal penalty amount or an automatic loss-of-incentive date for every case.
Chapter One, sections 2.5.2–2.5.3, also addresses tax registration, a separately registered mainland branch without the parent’s zone incentives, annual CIT filing and payment, WHT statements and applicable VAT obligations. The CIT return and payment period is generally 120 days after year end under that section, and benefiting from an incentive does not remove the return obligation.
Dariba recommendation: maintain separate calendars for CIT, WHT, VAT and the substance disclosure. Check applicable registration exceptions and their conditions rather than assume that every zone licence completes all tax registrations or eliminates all filing.
Cloud Computing needs its own contract and treaty analysis
Chapter Two of the procedural guide explains that the Cloud Computing SEZ is not confined to one physical site: its licensed data centres may operate across the Kingdom. Sections 3.1–3.2 describe the ordinary tax framework and specified special treatment concerning payment character, OECD-based interpretation, permanent establishments, treaty procedures and related-party expenses.
Section 3.2, Example 15, distinguishes the specified own-business software-copying payment’s character under the guide’s Cloud Computing treatment from the ordinary practice described there. This is a particular classification example, not an exemption for all software, intellectual property, services or foreign vendors.
Dariba recommendation: establish the rights granted, parties, residence, treaty and actual operations before calculating withholding or PE exposure. The guide’s Pillar Two references are conditional on application of those rules in the Kingdom; they do not, by themselves, prove that a domestic minimum tax has been enacted or that every incentive produces the final group effective tax rate.
Model the actual framework rather than the headline
Compare qualifying income, non-qualifying income, substance expenditure, goods movements, withholding, VAT, customs cash flows and filing costs under the actual licence. Keep the RHQ incentive separate as well: it has its own eligible activities, substance rules and thirty-year framework.
A useful investment conclusion identifies the available benefit, its legal conditions and the events that change it. It should not assume that all zones share the same CIT rate, every import is permanently duty-free or every service supplied inside a zone is zero-rated.
Key takeaways
- The zones do not share one universal tax package.
- Cloud Computing does not inherit the three zones' 5% rate.
- SILZ follows a separate incentive framework.
- Customs suspension differs from permanent duty exemption.
- Goods and services require separate VAT analysis.
- Annual substance and additional IP conditions need evidence.
Sources
- ZATCA Tax and Customs Operations in Special Economic Zones, current procedural guideChapter One, sections 1–2.5, and Chapter Two, sections 1–3.2: separate zone treatments, mixed income, examples, VAT, customs suspension and compliance.
- Economic Substance Requirements Regulation of Special Economic Zones, Board Resolution 03-02-26Articles 1–9: four-zone scope, annual substance, management, additional IP conditions, disclosure and penalties; controlling Arabic checked.
- ZATCA General Guideline for Zakat, Tax and Customs Regulations on the Special Integrated Logistics Zone, second edition May 2026Sections 4–4.1: the distinct eligible-income regime and fifty-year or earlier-ending incentive period. This reference does not certify every SILZ condition.
- GACA Special Tax Rules for the Special Integrated Logistics Zone, official English textArticles 1–7 and 8(A): definitions, eligible income, withholding categories/exclusions, period, anti-avoidance, accounts, administration and treaty residence. Article 5 relocation wording must be reconciled with current guidance before a case-specific relief conclusion.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.