In brief
Classify the actual drink, preserve final-volume precision and support product data before applying the 2026 excise tiers or a claimed exclusion.
Saudi Arabia’s sweetened-beverage excise model, effective from 1 January 2026, uses the drink’s total sugar content and ready-to-drink volume. A correct recipe classification is essential, but it is only the first step: a zero rate does not necessarily remove registration, goods-registration, records or return obligations.
Read the current Implementing Regulations and December 2025 definitions/dilution decision alongside ZATCA’s explanatory guideline. Parts of that guideline describe the change prospectively; the later legislation and decision supply operative details that were still described as forthcoming.
Establish whether the product is a sweetened beverage
The definitions decision, Fourth, covers a product with added sugar or other sweeteners produced for consumption as a beverage, whether ready to drink or supplied as a concentrate, powder, gel, extract or another convertible form. Honey and other natural sweetening ingredients are not automatically outside that definition.
An important distinction follows. A drink’s natural sugar alone does not necessarily bring it into the sweetened-beverage category. Once added sugar or another relevant sweetener brings a drink within scope, its total sugar—natural, added and sugar from other sweeteners—determines the tier. Mixing qualifying natural juices or concentrates is not itself the addition of a sweetener where the ingredients contain no added sugar or other sweeteners.
Artificial sweetener quantity is not added to total sugar for this calculation. Where artificial sweeteners and added sugar/other sweeteners coexist, assess the actual total-sugar content; a “diet” name is insufficient evidence of the artificial-only tier.
References: definitions decision, Fourth and Sixth; guideline, “Definition of sweetened beverages” and “Sugar and other/artificial sweeteners”, pp. 6–8.
Apply the tier to total sugar per 100 millilitres
| Tier | Relevant classification | Excise per litre |
|---|---|---|
| 1 | Sugar-free, containing artificial sweeteners only | SAR 0 |
| 2 | Low total sugar: less than 5 g per 100 ml | SAR 0 |
| 3 | Medium total sugar: 5–7.99 g per 100 ml | SAR 0.79 |
| 4 | High total sugar: at least 8 g per 100 ml | SAR 1.09 |
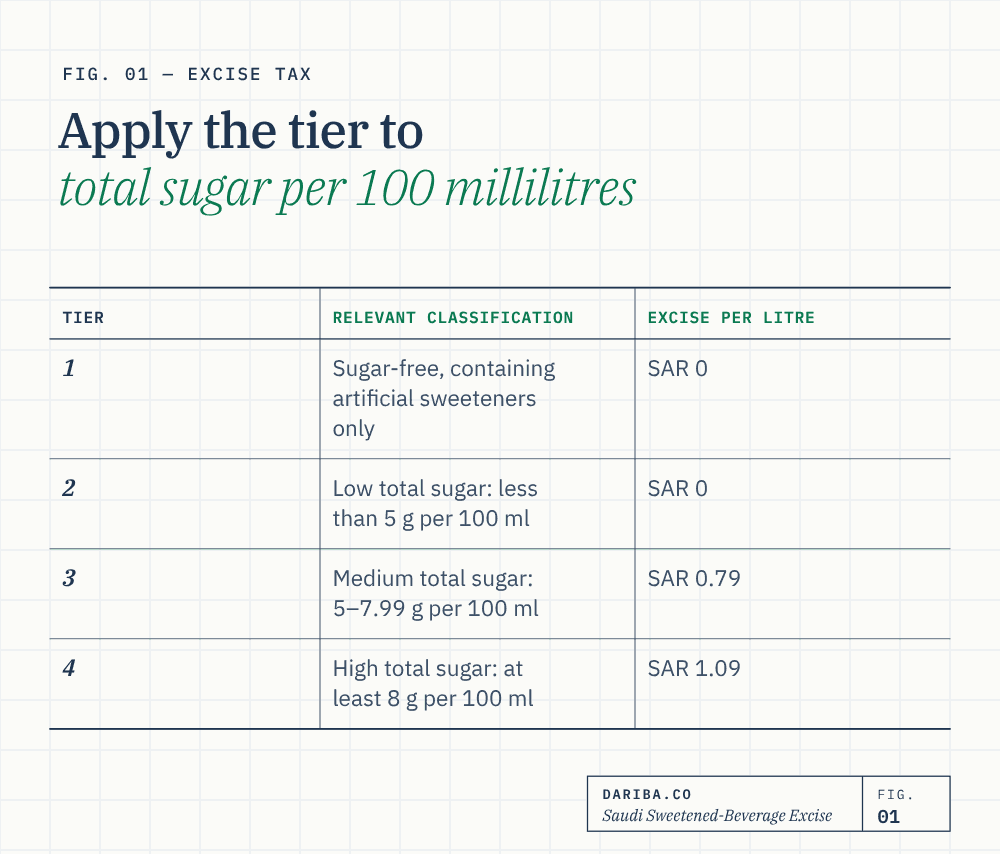
Establish the product’s actual composition and qualification before using the table. Exactly 5 g is not below the tier-2 boundary; exactly 8 g falls in tier 4. Do not invent a rounding tolerance around a boundary or change a laboratory result merely to fit the preferred rate.
ZATCA’s guideline expressly states that tiers 1 and 2 remain excise goods and relevant compliance requirements continue. Their zero rate is therefore different from exclusion from the definition. The current Article 2 classification and Article 3 rates should govern over an older general webpage retaining a separate 50% carbonated-drink category.
References: Implementing Regulations Articles 2–3; guideline, rate table and general clarifications, p. 6.
Use the official examples without rounding a shipment prematurely
The guideline’s Example 1, p. 12, contrasts an artificial-only 330 ml drink with a high-sugar 330 ml drink. The latter’s illustrated excise is approximately SAR 0.36. Example 2, p. 13, holds the 200 ml container size constant across low-, medium- and high-sugar drinks, illustrating zero, approximately SAR 0.16 and approximately SAR 0.22 respectively. These are official examples supporting the classification and volume analysis.
Dariba original shipment illustration: a qualifying tier-4 drink in a 330 ml can gives SAR 1.09 × 0.33 = SAR 0.3597 before rounding. For 50,000 cans, total volume is 16,500 litres and the unrounded aggregate excise calculation is SAR 17,985. Multiplying a display-rounded SAR 0.36 by every can instead produces SAR 18,000, a SAR 15 difference.
This arithmetic illustrates why the accounting system should preserve sufficient precision and use the required reporting-unit and rounding rules. It does not prescribe a statutory invoice or return rounding method. At the same 330 ml volume, a qualifying tier-3 drink gives SAR 0.2607 before rounding; compare identical volumes when evaluating reformulation rather than attributing a container-size change to the recipe alone.
References: Implementing Regulations Article 4; guideline, Examples 1–2, pp. 12–13.
Keep energy drinks and excluded products separate
Energy drinks remain a separate category subject to the 100% ad valorem treatment; reducing sugar does not, by itself, move an energy drink into a zero-rate beverage tier. The current decision’s energy definition and product marketing must be examined. Carbonation alone, conversely, is no longer a separate excise category: the actual sweetened-beverage definition matters. Flavouring without a relevant sweetener is not itself a substitute for that definition.
The decision, Fifth, excludes specified natural juices without added sugar/other sweeteners; qualifying milk/dairy and plant-based alternatives; infant products; specified nutritional/medical products; natural-person preparation for personal or other non-commercial use; and qualifying restaurant/similar-place preparation served in an open, unsealed container for immediate consumption. The milk and plant-alternative conditions include the specified at least 75% content of the ready-to-drink product. The nutritional/medical exclusions refer to their actual technical standards.
These are detailed product/use exclusions, not three universal exemptions based on a marketing label. A 60%-milk sweetened drink does not satisfy the 75% condition merely because its front label says “milk drink”. An exclusion for an open drink prepared at a restaurant also does not automatically exempt a previously released taxable concentrate used to make it.
References: definitions decision, Third–Sixth; guideline, excluded-beverage discussion, p. 9.
Calculate concentrates from the supported final yield
Article 4(3) applies the appropriate tier to the litres of final ready-to-drink beverage produced using the stated dilution instructions. Both final total sugar and final volume matter; the concentrate’s bottle volume alone is insufficient.
The decision’s dilution methodology requires supporting records. If packaging lacks the relevant instructions or nutrition information, ZATCA may accept other evidence at its discretion. It may instead apply an alternative ratio where the specified missing-evidence, inconsistent-comparator or reasonable-doubt conditions arise, using comparable products’ objective characteristics.
Where sufficient information is unavailable to establish an alternative, the decision permits a default conversion based on at least six units of diluent to one unit of concentrate, with scope to increase it, and classification of the resulting drink in tier 4. Six diluent units plus one concentrate unit must not casually be described as six final units. The decision also preserves its specific liquid-concentrate rule where the nutrition data shows artificial sweeteners only or less than 5 g total sugar per 100 ml.
Dariba original illustration: supported instructions yield 100 litres of a qualifying medium-sugar final drink. Excise is 100 × SAR 0.79 = SAR 79. That assumes the yield and tier are substantiated; it is not a default ratio or a tax calculation on 100 litres of undiluted input.
References: Implementing Regulations Article 4(3)–(4); definitions decision, “Methodology for calculating the dilution ratio”, First–Sixth.
Register the goods and update changes before the next release
Article 22 bis requires the importer, producer or other person releasing excise goods for consumption to register those goods before release. Supply the information and evidence needed for calculation and classification. Notify changes when known and, at the latest, before the next release of those goods.
Where information is incorrect or reasonably doubted, ZATCA can amend registration using the highest rate or available information, require an update, request laboratory/supporting evidence or seek testing by the competent authority. Laboratory reports used as proof must meet all specified accreditation, technical-detail and relevant-standard requirements. A generic manufacturer statement should not be represented as automatically satisfying those conditions.
Failure to register or update also permits the stated protective registration/amendment or assessment response. ZATCA must notify the decision, with the objection right preserved. Dariba recommendation: connect formulation approval, product registration, stock codes and the next-release date so that reformulation does not leave the customs and finance systems using different tiers.
Reference: Implementing Regulations Article 22 bis(1)–(7).
Treat historic stock refunds as conditional and time limited
Article 60(7) provides a specified refund route for registered persons who released goods for consumption and hold qualifying unsold stock when a legislative rate reduction takes effect. It requires application within ninety days of that effective date, prior payment of the tax, a claim limited to the difference, supported reduction of retail prices and the prescribed application/evidence. ZATCA may request further information and considers the request under Article 54.
The guideline’s refund-service screenshots explain navigation; they do not extend that deadline or establish that a new application remains timely in October 2026 for the January change. Nor does every later commercial recipe change reopen that statutory transition route.
Maintain the release, ownership/possession, unsold-stock, paid-tax and price-reduction trail. For the separate import, licensed-person return, payment and correction rules, see the Saudi excise overview.
References: Implementing Regulations Article 60(7); guideline, refund-service walkthrough, pp. 18–21.
Key takeaways
- Total sugar determines the tier once the actual sweetened-beverage scope conditions are met.
- Zero-rate tiers remain excise goods with relevant compliance duties.
- Energy drinks remain separately subject to 100% ad valorem excise.
- Official Examples 1–2 illustrate container volume and sugar classification.
- The original 50,000-can illustration gives SAR 17,985 before rounding, not SAR 18,000.
- Concentrates use supported final ready-to-drink yield and the current dilution methodology.
- Goods registration, timely changes and laboratory evidence have express statutory conditions.
- The historic ninety-day stock-refund route is not reopened by an online service or every recipe change.
Sources
- Saudi Excise Tax Law, current amended Arabic textArticles 3–7 and 10: actual release, registration activity and warehouse licensing framework.
- Saudi Excise Tax Implementing Regulations, current Arabic compilation incorporating December 2025 amendmentsArticles 1–4, 8, 15–18, 20–22 bis and 60(7). Current compilation has 52 pages; use amended operative text rather than old summaries.
- ZATCA amendments to the Excise Tax Implementing Regulations, December 2025Comparison document distinguishes previous/current wording. Carbonated category removed; revised beverage rates, declaration/payment deadlines and goods registration.
- ZATCA definitions of excise goods, dilution methodology and retail-price criteriaSecond–Sixth definitions and exclusions; dilution methodology First–Sixth, including evidence discretion and minimum six-diluent-to-one-concentrate default where its conditions are met.
- ZATCA Explanatory Guideline on Applying the Tiered Volumetric Approach to Sweetened BeveragesRates and zero-tier compliance pp.4–8; exclusions p.9; official Examples 1–3 pp.12–14; historic refund-service navigation pp.18–21. Prospective passages read with the later operative legislation and decision.
- ZATCA announcement: Excise Implementing Regulations amendments effective 1 January 2026, 30 December 2025Confirms actual commencement of the tiered total-sugar methodology; not reliance on an old general-rate webpage.
General information only. Apply the actual goods, composition, release date, activity and controlling Arabic law, amended regulations and decisions. Zero-rate excise goods differ from excluded goods. Official ZATCA examples and Dariba original illustrations are distinguished; historic refund-service screenshots do not extend statutory deadlines. Mechanical validation is not independent legal certification.