In brief
The current waiver covers specified older tax penalties subject to Resolution 1117. Returns due on or after 1 July 2026, evasion and Article 45 fines require separate treatment; approved instalments can extend beyond December.
ZATCA’s current penalty-waiver window ends on 31 December 2026, but that date does not make every unpaid penalty eligible. For the return-related fines covered by Ministerial Resolution 1117, Clause Three, the underlying return must have been due before 1 July 2026. A business can therefore have an eligible older liability and an excluded newer liability on the same statement.
The useful exercise is to classify each penalty, identify its underlying return and due date, and establish the payment or approved instalment route. The initiative removes qualifying penalties subject to its conditions; it does not cancel the principal tax.
Separate the relief window from the return cutoff
Resolution 1117 Clause One extends the initiative for six calendar months from 1 July 2026. ZATCA’s 29 June 2026 extension announcement confirms the end date of 31 December 2026. These are the current implementation dates, not a general suspension of tax deadlines.
Clause Three covers specified late-payment, late-return and VAT return-correction fines connected with returns due before 1 July 2026. The test concerns when the return was legally due, rather than when the taxpayer discovers the error, files the correction or receives an assessment.
A return for an earlier accounting period can still fall outside the date test if its actual filing deadline was on or after 1 July. Conversely, a later reassessment does not itself move an older return’s due date into a new period. Establish the applicable deadline, including any legally effective extension, from the actual filing record.
Apply the particular penalty route
| Penalty category | Relevant current route |
|---|---|
| Late registration | Clause Two: registered taxpayer, all required returns filed and the stated principal-tax payment or instalment conditions |
| Late filing and late payment | Clause Three: qualifying return due before 1 July 2026 and the stated principal-tax conditions |
| VAT return correction | Clause Three: the same return-deadline and payment conditions; evasion remains excluded |
| VAT Law Article 45 penalties | Expressly excluded in ZATCA’s 29 June announcement |
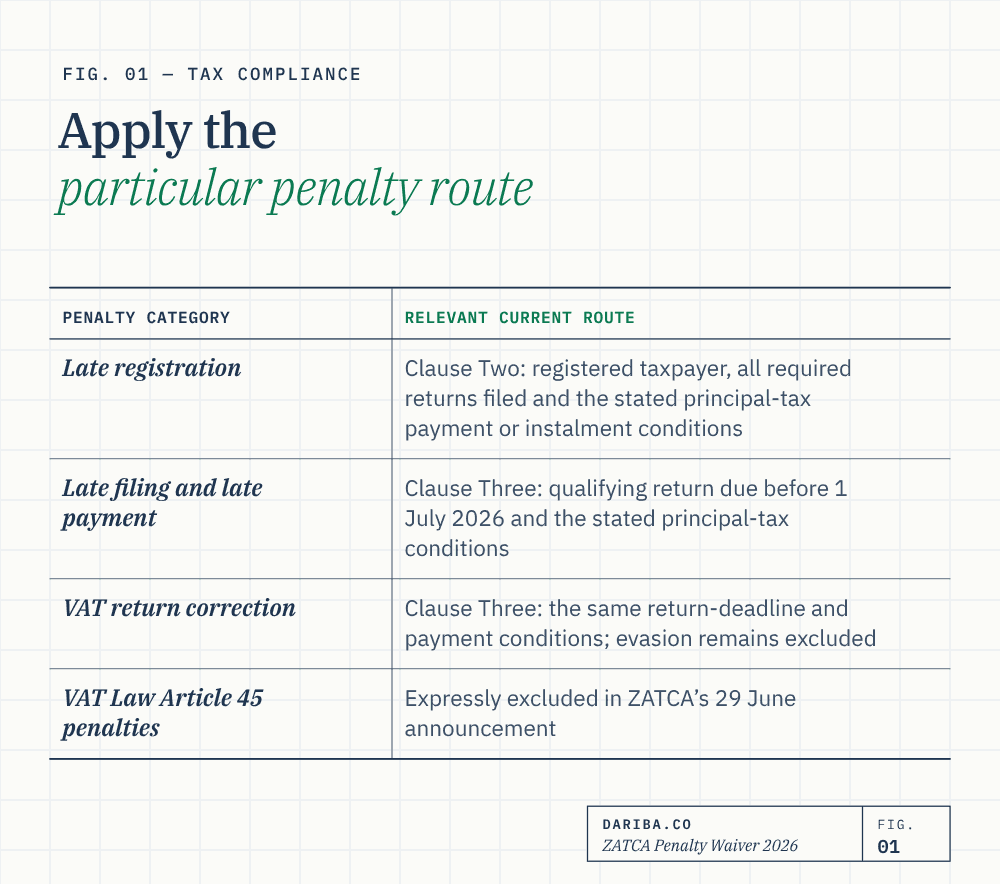
Clause Two’s late-registration route should be examined on its own terms. Do not impose a single invented violation-date test on every category merely because Clause Three contains a return cutoff.
The decision applies across the relevant tax systems. VAT, withholding tax and corporate income tax liabilities should each be reconciled to their own returns and penalty classifications. This tax initiative does not itself establish a waiver of Zakat obligations or customs penalties.
Include qualifying reassessments without treating every error as eligible
Clause Three expressly covers fines arising either from a taxpayer action or from an assessment or reassessment by ZATCA. A liability is not disqualified solely because the Authority, rather than the taxpayer, identified the underpayment.
That does not remove the other conditions. The return must satisfy the specified deadline test, the fine must be a covered type, and the related principal tax must be dealt with through the permitted route. Clause Five excludes fines arising from tax-evasion violations, including the categories otherwise described in Clauses Two to Four.
A correction should explain the transaction, period, error and evidence accurately. Calling an adjustment an “honest mistake” in correspondence does not determine its statutory classification. The VAT error-correction guide addresses the underlying correction process; waiver eligibility is an additional review.
Keep the current exclusions visible
ZATCA’s 29 June announcement excludes evasion-related fines, VAT Law Article 45 fines, fines paid before the initiative’s effective date, and fines linked to returns due after 30 June 2026. The last item corresponds to Clause Three’s before-1-July test.
Article 45 includes record-retention failures, obstruction of officials and other contraventions of the VAT Law or Regulations. The specific legal basis of an e-invoicing or field-inspection fine therefore matters. An older announcement describing Article 45 relief for an earlier extension is not evidence that the same fine is covered by the current extension.
The current decision is also not a general refund entitlement for penalties already paid. Where a paid penalty or a disputed classification is involved, establish the applicable legal route separately rather than book an expected refund from the December deadline alone.
Use the instalment route within its actual conditions
Clauses Two and Three permit the relevant principal tax to be paid during the stated period beginning 1 June 2022 and ending with the initiative, or an instalment request to be submitted during that period, with compliance with the plan approved by ZATCA. Registration and filing conditions still apply to the relevant route.
Clause Four expressly extends the late-payment relief to principal tax included in an approved instalment plan with payments due after the initiative ends. An approved plan can therefore continue beyond December; the entire principal need not necessarily be paid by 31 December where that permitted route applies.
An application is not an approved repayment schedule. Retain the request, approval, covered debt and due dates, and meet every required instalment. Clause Four provides for late-payment fines associated with unpaid principal if the taxpayer fails to comply during or after the initiative. A plan should be assessed for affordability before it is relied on as the relief route.
The VAT payment-plan guide explains related payment procedures. Initiative-specific relief still requires the current decision’s conditions; ordinary permission to pay by instalments should not be assumed to settle every waiver question.
Reconcile mixed eligible and excluded balances
Dariba original illustration: assume a registered company has filed all required returns. Its verified statement contains SAR 100,000 principal tax, SAR 15,000 of unpaid covered return-related fines on returns due before 1 July 2026, and SAR 5,000 of fines on returns due after 30 June. Assume no evasion or Article 45 fine, and that the payment and all other conditions are met.
The potentially qualifying amount is SAR 15,000, not the full SAR 20,000 penalty balance. If that amount is relieved, the assumed remaining balance is SAR 100,000 principal plus SAR 5,000 excluded fines, or SAR 105,000. This is an eligibility illustration using assumed assessed amounts, not ZATCA’s example or a calculation of statutory penalty rates.
A second company may obtain relief on the same eligible older fines through a qualifying approved instalment plan. Its cash-payment timing would follow that plan; the illustration does not promise approval or remove the obligation to pay excluded balances.
Complete the evidence and monitor the approved outcome
Build a schedule showing tax type, return period, actual due date, assessment reference, penalty type and legal basis, principal debt, amounts already paid and the proposed treatment. Separate the filing record from the payment record and retain the approved plan where relevant.
Submit the required returns and payments or instalment request in time to address errors before the initiative closes. Then reconcile the Authority’s account and actual penalty treatment. A submission receipt or an expected accounting reversal is not proof that the correct balance has been relieved. For uncertain cases, obtain clarification through ZATCA’s official channels, including 19993, while preserving relevant objection or appeal deadlines.
Clause Six also states that, if a further extension becomes necessary after 31 December 2026, the specified Clause Three fines on returns due on or after 1 July 2026 will not be covered by that extension. Waiting for another announcement is therefore not a supported strategy for bringing newer returns into this relief.
Use the CIT penalties guide and e-invoicing penalties guide to establish the underlying exposure. The final waiver conclusion should identify the covered amount, satisfied conditions, excluded balance and any approval or classification still outstanding.
Key takeaways
- The current implementation window ends on 31 December 2026.
- Clause Three return-related fines require a return due before 1 July 2026.
- Qualifying assessments and reassessments can be covered; evasion remains excluded.
- The current ZATCA announcement excludes VAT Law Article 45 fines.
- An approved instalment plan can extend beyond December, subject to compliance.
- Principal tax, excluded fines and actual account treatment must be reconciled.
Sources
- Saudi VAT Law, controlling Arabic textArticle 45 identifies VAT contraventions whose fines are excluded by the current ZATCA extension announcement; Article 46 preserves collection of the underlying tax.
- Umm Al-Qura, Ministerial Resolution 1117 extending the penalty-waiver initiativeClauses One–Seven: six-month extension from July 2026, registration/return conditions, assessments, instalment relief, evasion exclusion and fixed return cutoff.
- ZATCA, official penalty-waiver extension announcement, 29 June 2026Confirms 31 December 2026 expiry, return due-date cutoff, Article 45 and paid-penalty exclusions, and approved instalment conditions.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.