In brief
ZATCA’s Wave 25 criteria use VAT-subject revenue exceeding SAR 187,500 in any listed year from 2022 to 2025, with notified integration by no later than 1 February 2027. Earlier obligations, actual architecture and production readiness remain relevant.
ZATCA’s 24 July 2026 Wave 25 announcement targets taxpayers whose revenue subject to VAT exceeded SAR 187,500 in 2022, 2023, 2024 or 2025. It states that targeted taxpayers will be notified to integrate their e-invoicing solutions with Fatoora by no later than 1 February 2027.
The decision is an integration requirement for the relevant taxpayers, rather than a new tax rate. Businesses should establish their actual inclusion and notified date, then verify that every relevant invoice-generation channel can operate under Phase Two.
Apply the threshold to each specified year
The announcement uses an exceeded test and lists the four years separately. One qualifying year can bring a taxpayer within the announced criteria; a fall in later revenue does not erase that earlier result. Do not test only the latest year or replace the criteria with a four-year average.
Exactly SAR 187,500 does not exceed the stated threshold. That narrow observation does not prove that a taxpayer has no integration obligation: an earlier wave, an actual notification or another applicable requirement must still be considered.
Reconcile the relevant VAT-subject revenue figure for each year to the taxpayer’s returns and supporting accounts. Accounting turnover, cash collected and VAT-subject revenue are not automatically identical. Document the treatment of exempt supplies, adjustments and amounts that are tax rather than revenue instead of assuming that a headline sales figure answers the test.
Distinguish the taxpayer from its outlets and notification
The criteria concern the targeted taxpayer. Do not split one taxpayer’s revenue across branches to manufacture several smaller threshold tests. At the same time, a separate company, a branch and a member of a VAT group should not be assumed to have identical onboarding or notification treatment.
E-Invoicing Regulation Article Three establishes the relevant person scope, including resident taxable persons and the specified persons issuing invoices on their behalf, with the stated non-resident exclusion. The Wave 25 revenue announcement should be applied within that framework.
Retain the actual ZATCA notice and confirm the legal person, VAT registration and integration date. The announcement describes direct notifications and says later waves will be notified at least six months before their integration dates. A public article or a future wave announcement is not a replacement for the taxpayer’s own correspondence.
A business already required to integrate under an earlier wave cannot use the later Wave 25 date to postpone its existing obligation. Where the revenue analysis and notification appear inconsistent, seek clarification promptly while continuing the obligations already applicable to the business.
Use a year-by-year original illustration
Dariba original illustration: assume a taxpayer within the e-invoicing framework has the following correctly classified VAT-subject revenue and has not been given an earlier integration date.
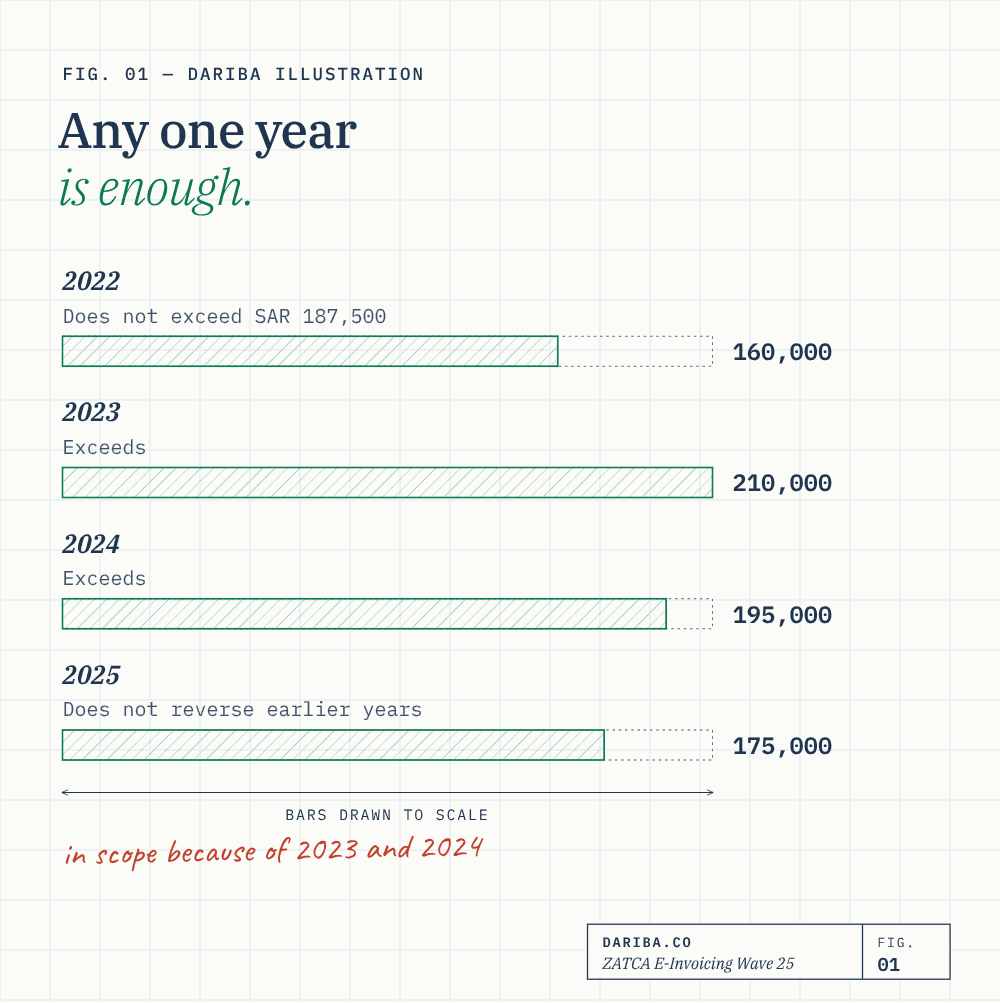
| Year | Assumed revenue | Exceeds SAR 187,500? |
|---|---|---|
| 2022 | SAR 160,000 | No |
| 2023 | SAR 210,000 | Yes |
| 2024 | SAR 195,000 | Yes |
| 2025 | SAR 175,000 | No |
The taxpayer meets the announced revenue criterion because of 2023 and 2024. The SAR 175,000 latest-year figure does not reverse the earlier qualifying years. This is Dariba’s illustration, not an example supplied by ZATCA, and assumes the revenue classification and taxpayer scope are correct.
By contrast, adding several years that are individually below the threshold does not itself satisfy the announcement’s any-year test. A company’s actual earlier notification or other obligation still requires separate review.
Build both clearance and reporting workflows
The implementation controls Clause Two(3) distinguish standard Tax Invoices and associated notes, which follow clearance before customer sharing, from Simplified Tax Invoices and notes, which follow the prescribed stamping and reporting process within no more than 24 hours of generation.
Integration therefore involves more than connecting one sales report at month-end. Identify the actual invoice types, credit and debit notes, issuing systems, required fields, structured transmission, returned responses and customer delivery. A successful simplified-invoice report does not demonstrate that standard invoices are cleared correctly.
ZATCA’s Detailed Technical Guideline, section 3.5, describes central and branch-based architectures. Use the actual generating and signing design to determine unit and credential arrangements; the number of checkout screens alone is not a universal certificate count. The solution-requirements guide explains these controls and the different stamp responsibilities.
Select and test a compliant implementation
ZATCA’s Solution Providers Directory expressly says its list is indicative and does not constitute approval of the listed solutions. A taxpayer can use a compliant solution from an unlisted provider. Vendor inclusion should not replace evidence that the deployed version, configuration and business workflow meet the requirements.
Dariba recommends assigning responsibility for the revenue review, notification, system inventory, master-data corrections, onboarding, production testing and archive access. Agree a realistic implementation schedule with the provider or internal team. There is no basis for promising that every business will complete integration within a fixed number of days or must spend a particular number of weeks in a sandbox.
The technical guideline sections 2.1.4–2.1.5 describes optional compliance-validation and integration-sandbox resources. They are useful for testing document and interface behaviour. Required onboarding and production credentials remain separate steps; a sandbox success is not evidence that the production environment is ready.
Test standard and simplified invoices, notes, warnings, rejections, interruptions and recovery. Include each actual issuance channel and the records needed to reconcile transactions to the VAT return.
Manage penalties and the current waiver separately
The May 2024 Arabic classification guideline, e-invoicing item 8, provides a specific warning and escalation schedule for failure to connect the relevant systems from the applicable date, subject to its stated Authority-system-fault qualification. Other failures have different categories and schedules. Do not estimate the exposure by attaching one generic fine to every invoice or month.
The current 29 June 2026 waiver announcement expressly excludes VAT Law Article 45 fines. It should not be presented as a guarantee that an integration failure can be corrected without penalty. The e-invoicing penalties guide and current waiver guide explain the separate tests.
For an interruption, follow the applicable incident notification and recovery procedure under implementation controls Clause Seven(5). Preserve the records and actual Authority responses. A provider’s assurance that the service will be fixed does not establish that the taxpayer’s notification or backlog obligations have been met.
Verify readiness before the notified date
The evidence file should show why the taxpayer is in scope, its actual deadline, every relevant system, correct production onboarding, tested document routes and the process for retaining and reconciling records. Record defects and their resolution, rather than treating a purchase order as completion of compliance.
After integration, monitor accepted documents with warnings, rejections, reporting queues and changes in unit or VAT registration details. Phase Two is an ongoing operating process. The Phase Two guide and clearance-versus-reporting guide provide the connected analysis.
Key takeaways
- The announcement tests 2022, 2023, 2024 and 2025 separately.
- Revenue must exceed SAR 187,500; one qualifying year is sufficient for the stated criterion.
- A later revenue decline does not erase a qualifying earlier year.
- Retain the actual taxpayer notification and any earlier integration date.
- Verify production onboarding and both standard and simplified document routes.
- The provider list and current penalty waiver do not guarantee solution approval or relief.
Sources
- ZATCA E-Invoicing Regulation, Arabic textArticle Three scope and non-resident exclusion; Articles Five–Seven technical framework, authority and implementation.
- ZATCA e-invoicing implementation controls, current Arabic publicationClauses Two, Three, Five and Seven and Annex One: document routes, security, retention, integration and incidents; controlling Arabic text.
- ZATCA E-Invoicing Detailed Technical GuidelineSections 2.1, 3.5, 4.2–4.3 and 5–6: optional testing, unit/CSID scenarios, response handling, signing and actual QR tags.
- ZATCA Simplified Guideline for Classification of General VAT Violations, second edition, May 2024E-invoicing table items 8–18, recurrence rule and restaurant examples: category-specific warning, intervals, escalation and system-fault qualifications.
- ZATCA Wave 25 selection announcement, 24 July 2026Revenue subject to VAT exceeded SAR 187,500 in 2022, 2023, 2024 or 2025; notified integration by no later than 1 February 2027.
- ZATCA Solution Providers Directory and express disclaimerIndicative directory does not constitute approval of the listed solutions; compliant unlisted solutions are permitted.
- ZATCA penalty-waiver extension announcement, 29 June 2026Current extension ends 31 December 2026 and expressly excludes VAT Law Article 45 fines; earlier e-invoicing relief is not assumed to continue.
General information only. Actual supplies, facts, applicable periods and controlling Arabic legislation determine the result. Official examples are distinguished from Dariba analysis and original illustrations. Seek advice or clarification where the arrangement or source material leaves a specific issue unresolved.